You stopped operating in March.
The clinic has been handed over safely.
The last renewal notice went unanswered on purpose.
For the first time in thirty one years, there is absolutely no policy in your name.
It felt like the natural end of a sequence.
However, a legal envelope suddenly arrives fourteen months later.
It is about a clinical procedure from 2023.
You were fully insured in 2023.
You are absolutely not insured right now.
Consequently, that second fact is what strictly decides your legal fate.
Therefore, understanding run off cover for doctors India is the conversation that strictly belongs before a last renewal.
Why Stopping Creates A Dangerous Gap At All
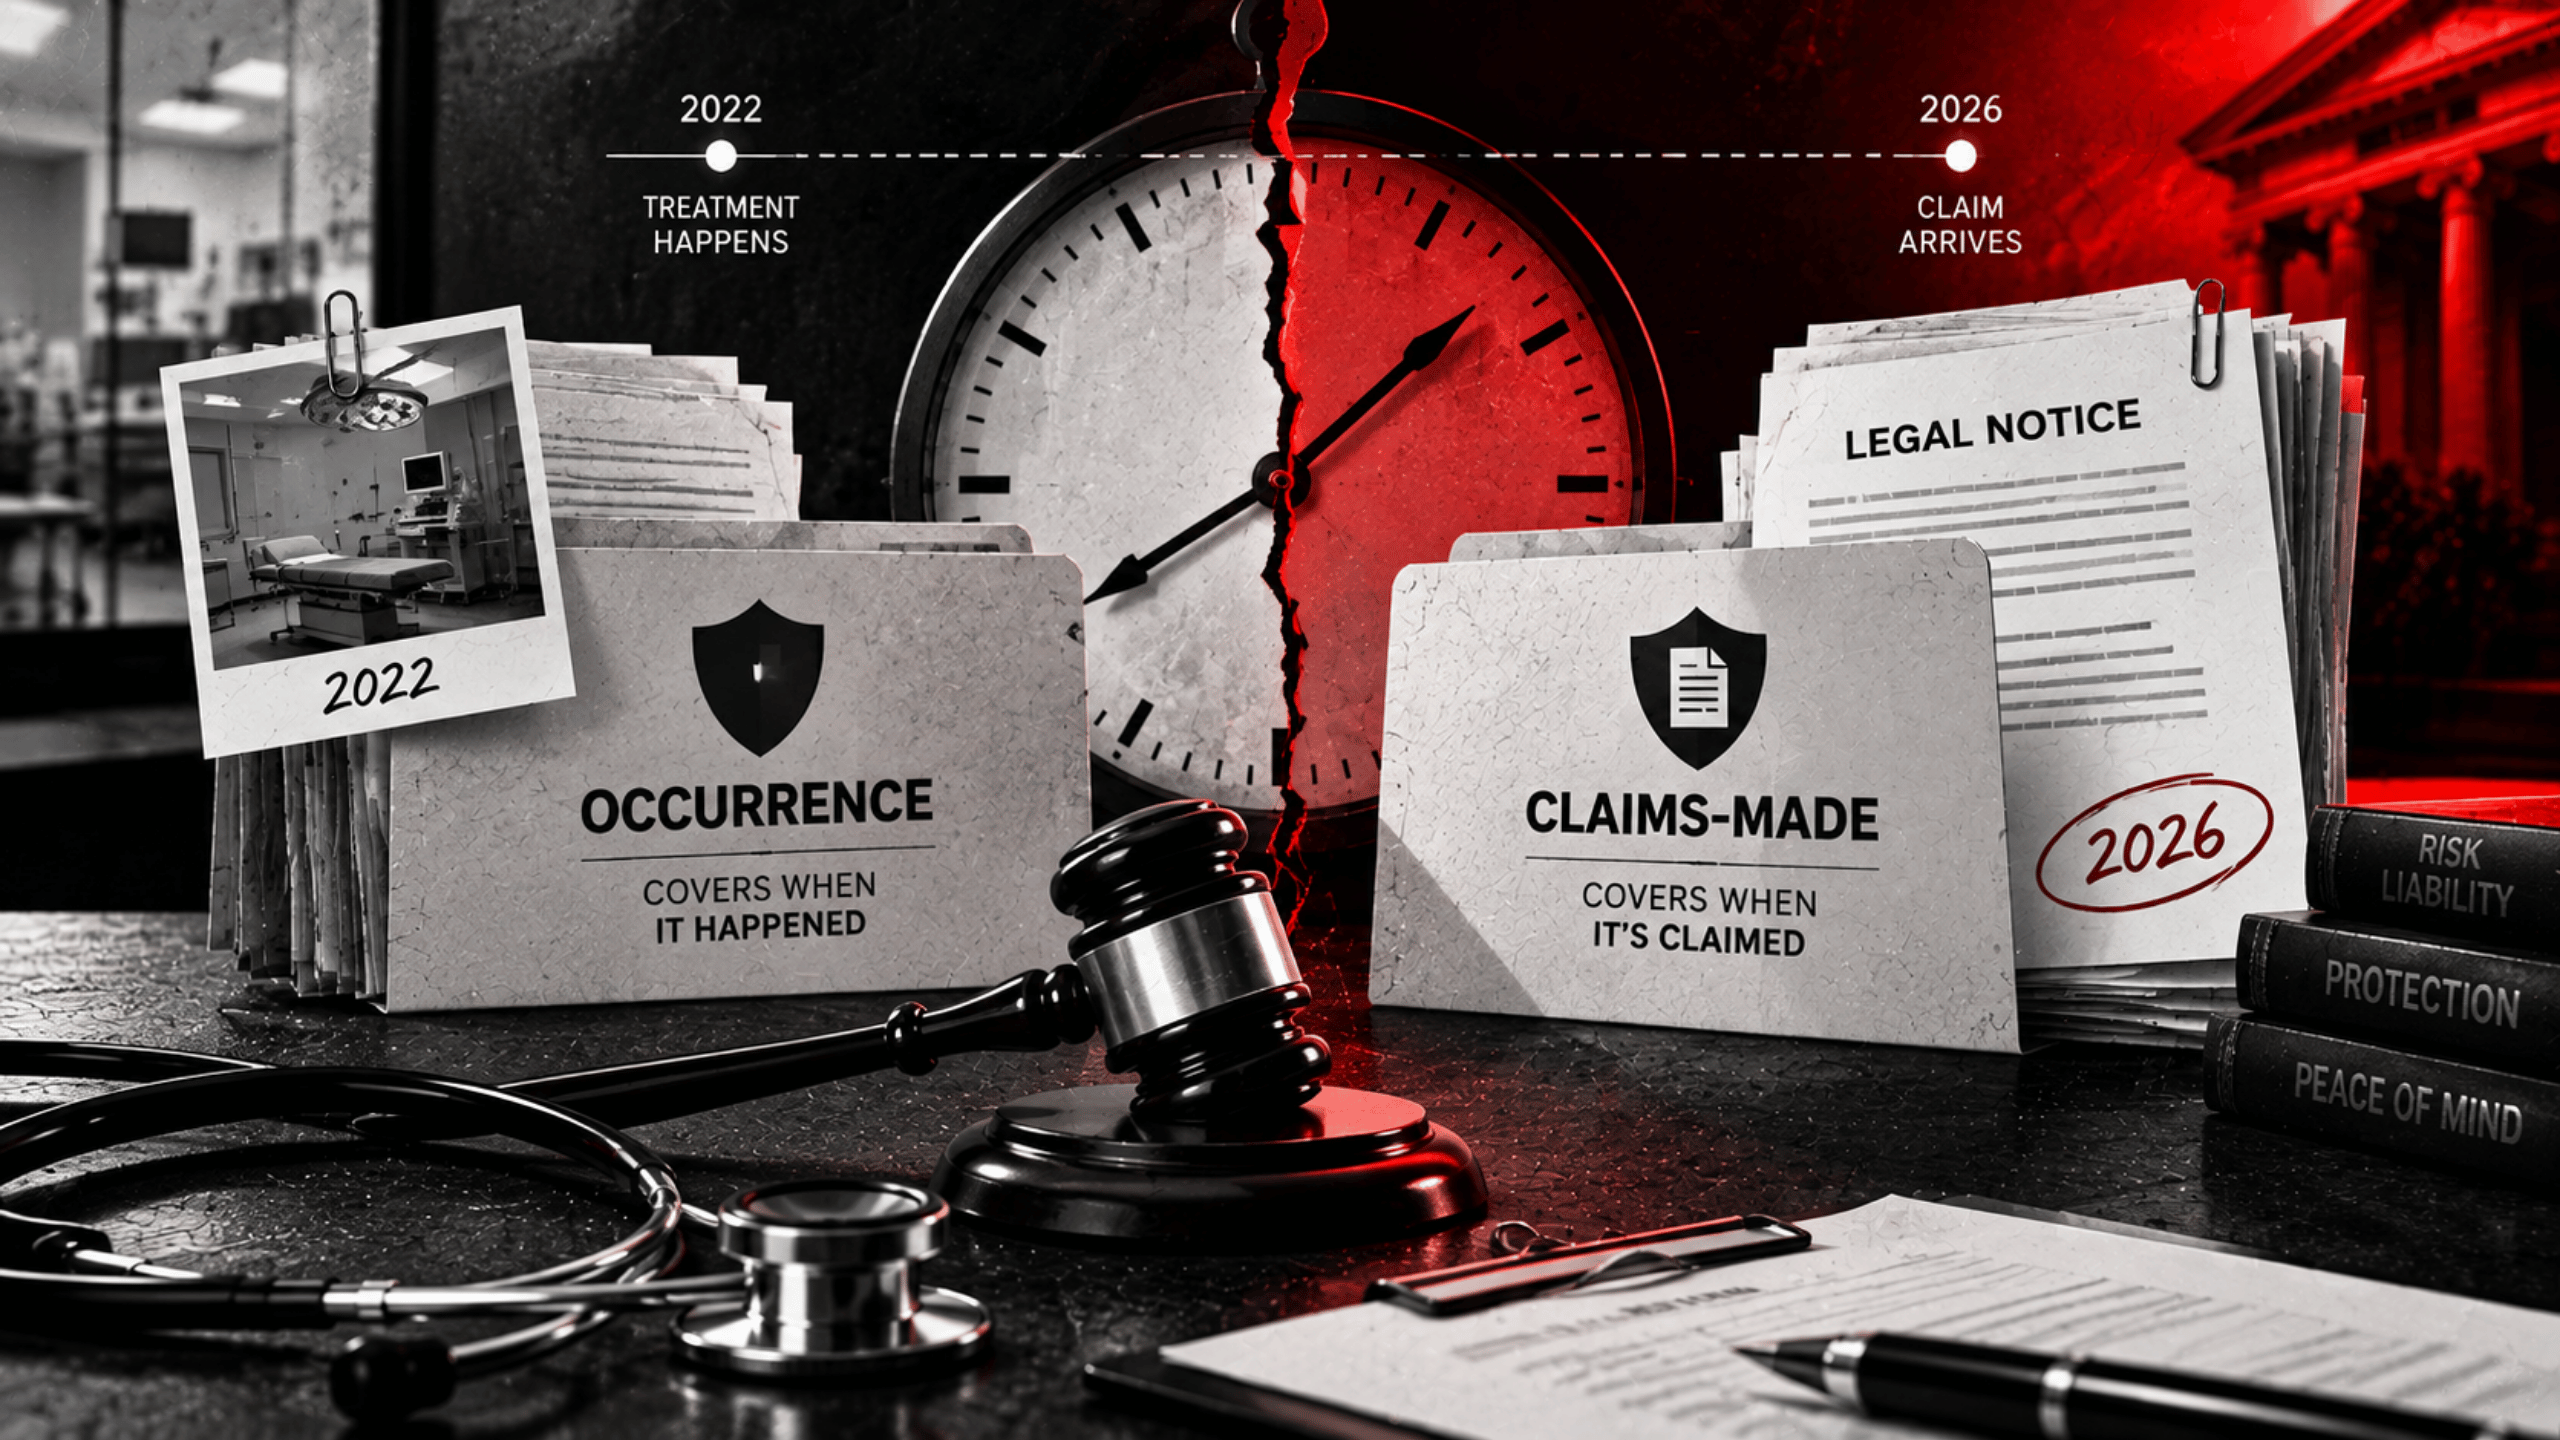
Claims made cover strictly responds to the legal claim, absolutely not to the past treatment. Specifically, the policy that answers is the one actively in force on the exact day a claim is first made against you in writing.
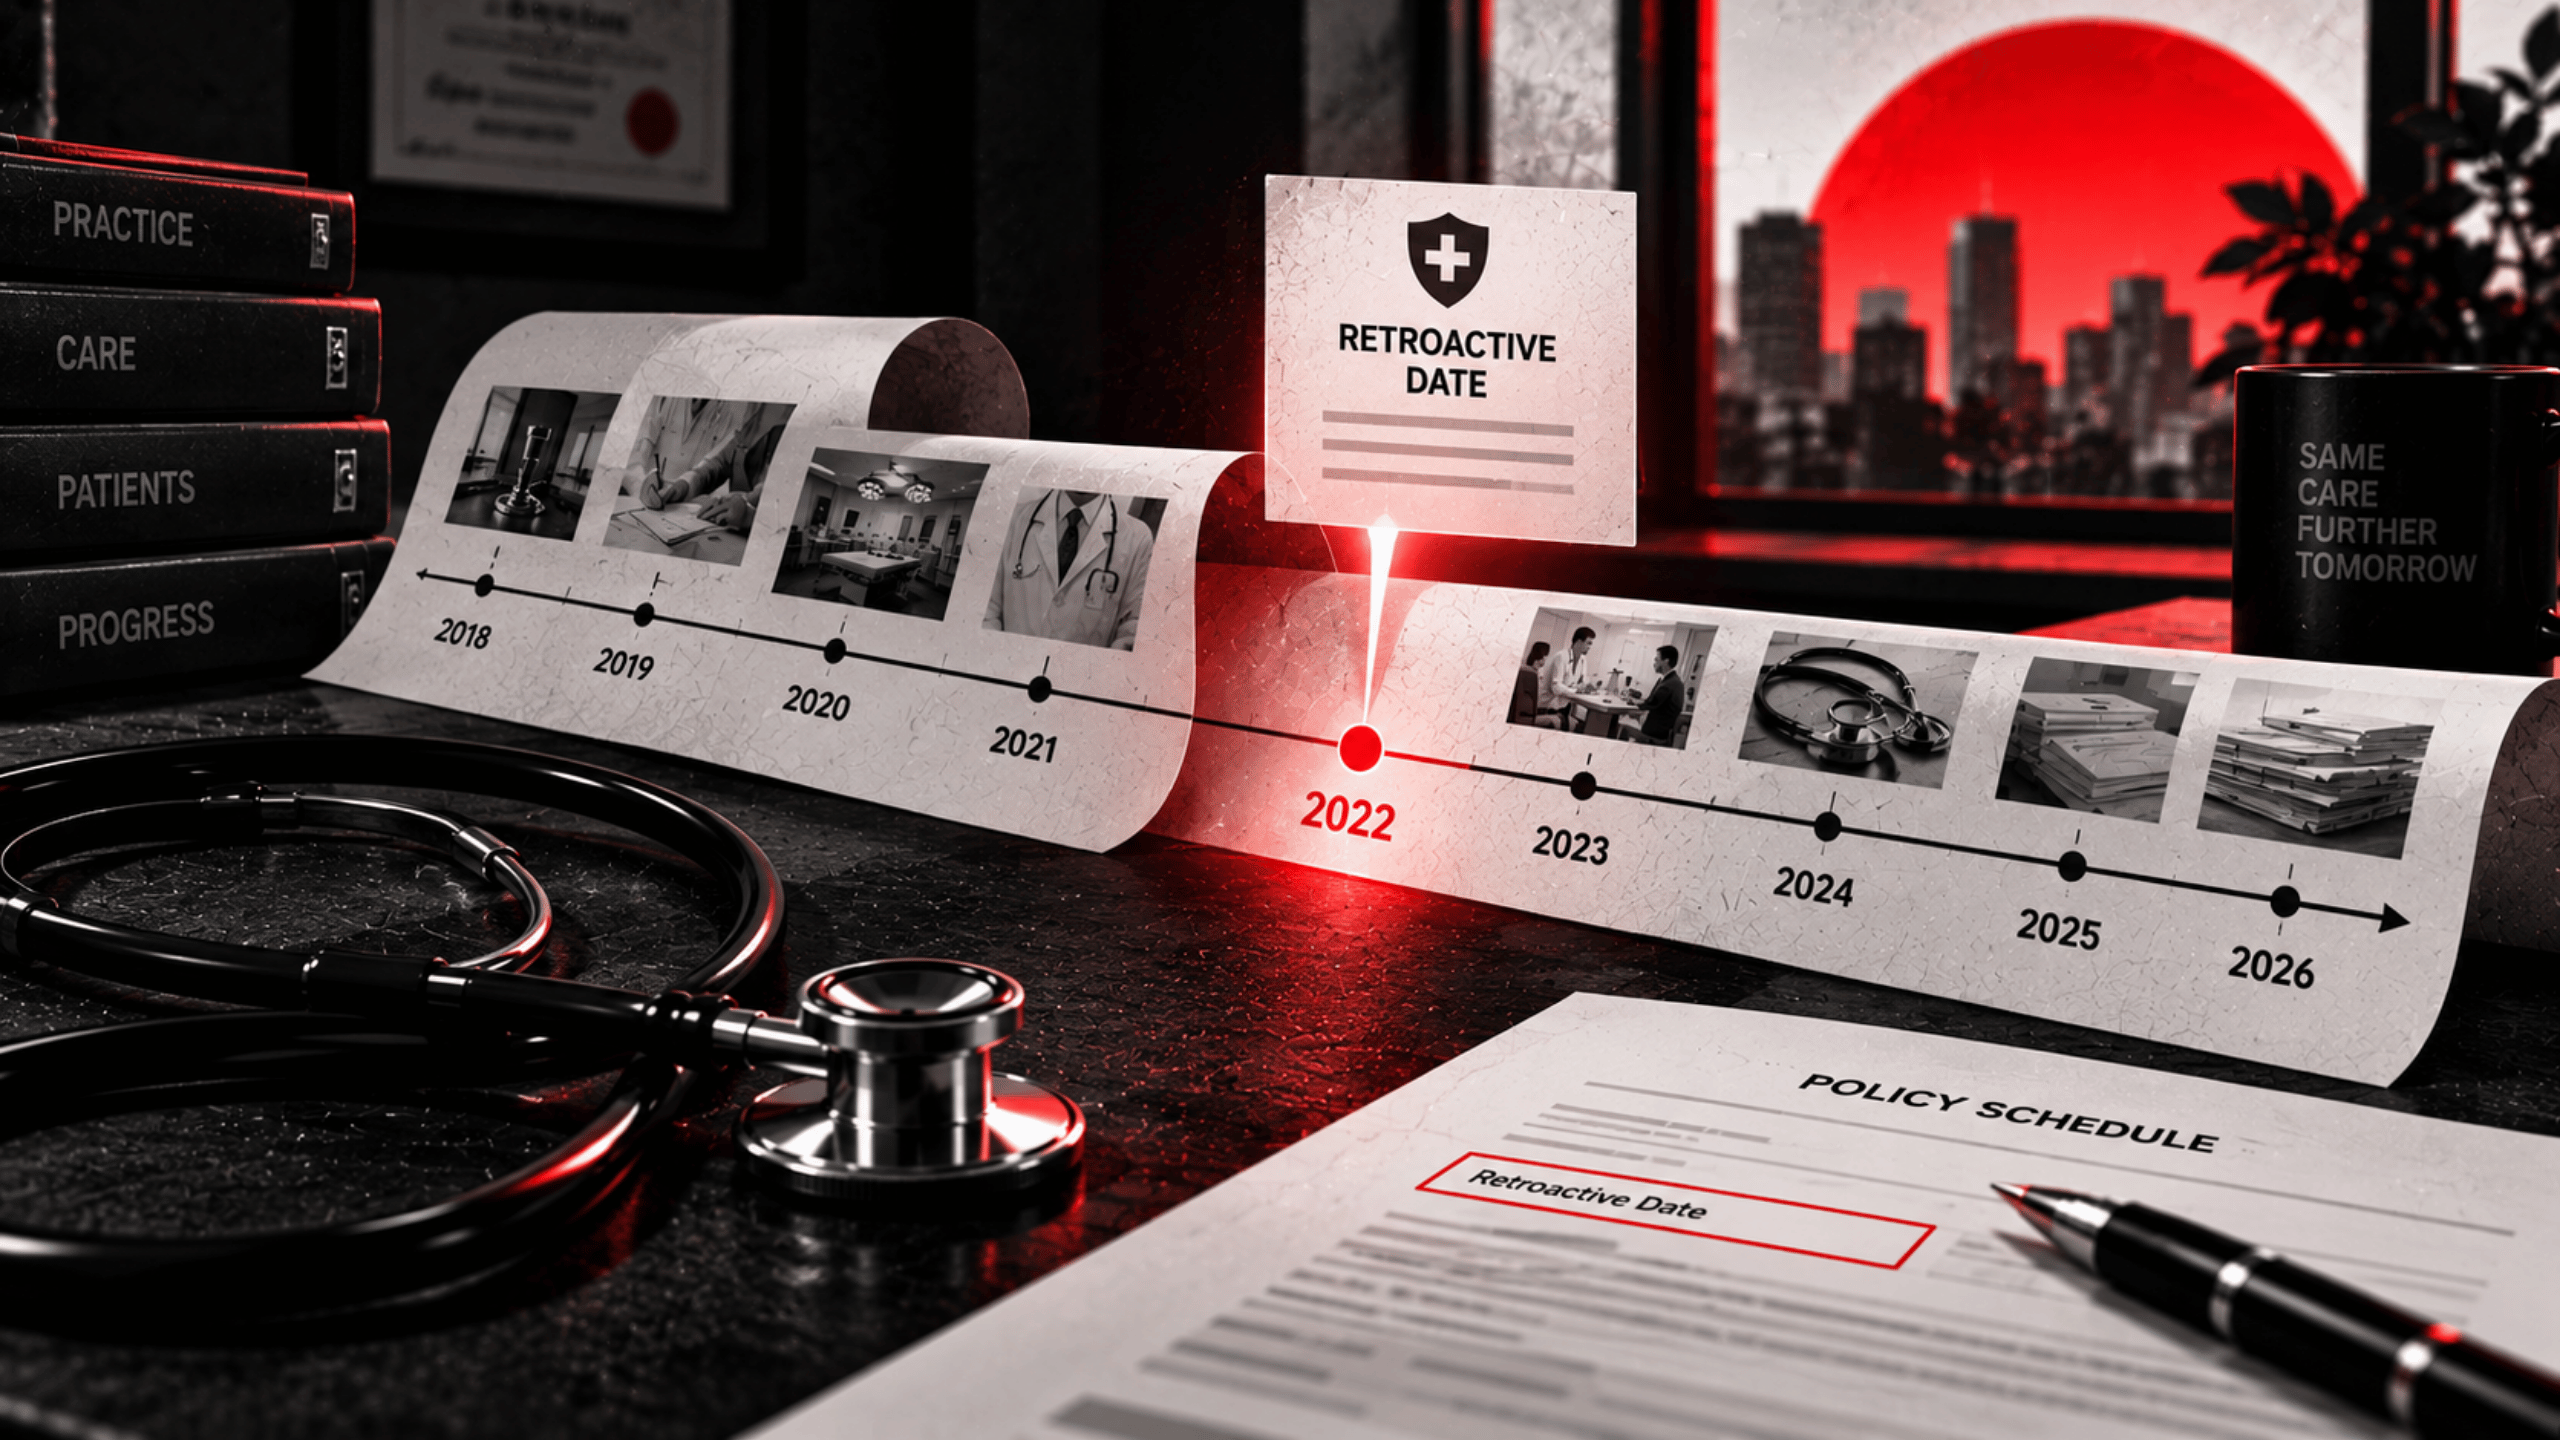
So while you are actively practising and renewing, the system works perfectly. Each year’s policy safely picks up claims about earlier years. However, this only applies as long as your retroactive date reaches back far enough.
Stop renewing and the protective chain ends completely. The past treatment strictly stays in the past where it always was. Conversely, there is absolutely no live policy standing actively in front of it. Nothing about your 2023 cover being highly valid in 2023 helps you today. Specifically, it is absolutely not the active policy being legally asked to respond right now.
You must understand standard contract principles under the Indian Contract Act to grasp this timeline.
What Indian Policies Actually Provide
Here it is strictly worth being precise rather than blindly optimistic. Specifically, a lot of what circulates online about run off cover for doctors India is written entirely for other global markets.
Indian professional indemnity wordings commonly contain an extended claim reporting clause. In some wordings, it clearly allows a limited notification window after policy expiry or cancellation. Specifically, one major insurer’s doctors wording states a strict period not exceeding ninety days. During this tight window, you may officially notify claims relating strictly to incidents that occurred within the active policy period. However, these must be claims you absolutely could not report before expiry.
Claims actively notified in that specific window are generally treated as made on the exact last day of the policy. Furthermore, they are treated strictly within the financial limits that already actively applied.
That is simply a notification window. It is absolutely not a multi year tail. Durations of two to seven years routinely appear in online guidance. However, those describe medical practice in completely other countries. Therefore, they should absolutely not be blindly assumed to apply to a policy issued in India.
Always verify statutory insurance definitions directly through the Insurance Regulatory and Development Authority of India (IRDAI) portal.
The Vital Question To Ask Your Insurance Provider
Which is exactly why finding proper run off cover for doctors India is best treated as a direct question to your own insurer.
It is absolutely not a ready product you simply go shopping for online. Specifically, what exists, and on what exact terms, is highly specific to the wording you already hold today.
Because contractual provisions differ drastically between insurers and between filings, the useful step is not to read more articles. Conversely, it is to actively ask, clearly in writing, right before your final renewal lapses. Ensure you follow National Medical Commission (NMC) professional guidelines regarding risk management while transitioning.
- What does my wording provide after expiry: Ask for the extended reporting or notification clause by exact name, and how long it strictly runs.
- Is any run-off arrangement actively available: Ask directly whether the specific insurer offers any tail cover for claims reported strictly after you permanently stop practising.
- What would it cost, and for exactly how long: If something is actually available, get the exact term and the premium clearly in writing.
- What happens if I simply reduce rather than stop: A consulting only practice may clearly allow continued cover on completely different terms.
Why Timing Strictly Decides Your Protection
Whatever is actively available will almost certainly need to be officially arranged while your policy is still entirely live. Once medical cover has permanently lapsed, your legal options narrow sharply. Furthermore, absolutely nothing can be applied retrospectively to a risk period that is already completely over.
So the vital decision belongs exactly a year before you intend to stop. Specifically, it belongs alongside everything else you are actively winding down. Therefore, do not leave it for the exact month you finally hand over the clinic keys. It is the exact same conversation as your last renewal, simply held slightly earlier and with one extra critical question included in it.
If you are strictly reducing your practice rather than ending it entirely, say so immediately. Continuing on revised terms is highly often completely simpler than desperately arranging anything after the fact. Consequently, it keeps the vital chain of cover entirely unbroken while your risk exposure naturally tapers.
The Final Takeaway On Your Career Retirement
Your clinical practice firmly ends on a specific date you actively choose.
However, your legal risk exposure ends strictly on a date patients quietly choose.
Ask your insurer exactly what happens after your last scheduled renewal. Do this actively while there is still an active renewal to actually ask about. Ultimately, securing appropriate run off cover for doctors India safely protects your hard earned retirement savings forever.
5 FAQ SECTION
What is run-off cover?
Broadly, it is an arrangement allowing claims to be reported strictly after you completely stop practising. This applies strictly to treatment given while you were actively insured.
Do Indian indemnity policies include anything like it?
Indian wordings commonly contain an extended claim reporting clause. This allows notification of qualifying claims for a highly limited period, often ninety days, strictly after expiry.
Is a multi year run-off policy available to doctors in India?
This must absolutely be confirmed directly with your specific insurer. Extended tail durations quoted online routinely describe other global markets, absolutely not the Indian market.
When exactly should I arrange my tail cover?
Strictly before your final active policy completely expires. Such arrangements generally must be finalized while your professional cover is still live and active.
Why does my old policy not simply cover old treatments?
Because claims made cover responds strictly based on when the formal claim is made against you. It absolutely does not respond based on when the historical treatment physically happened.