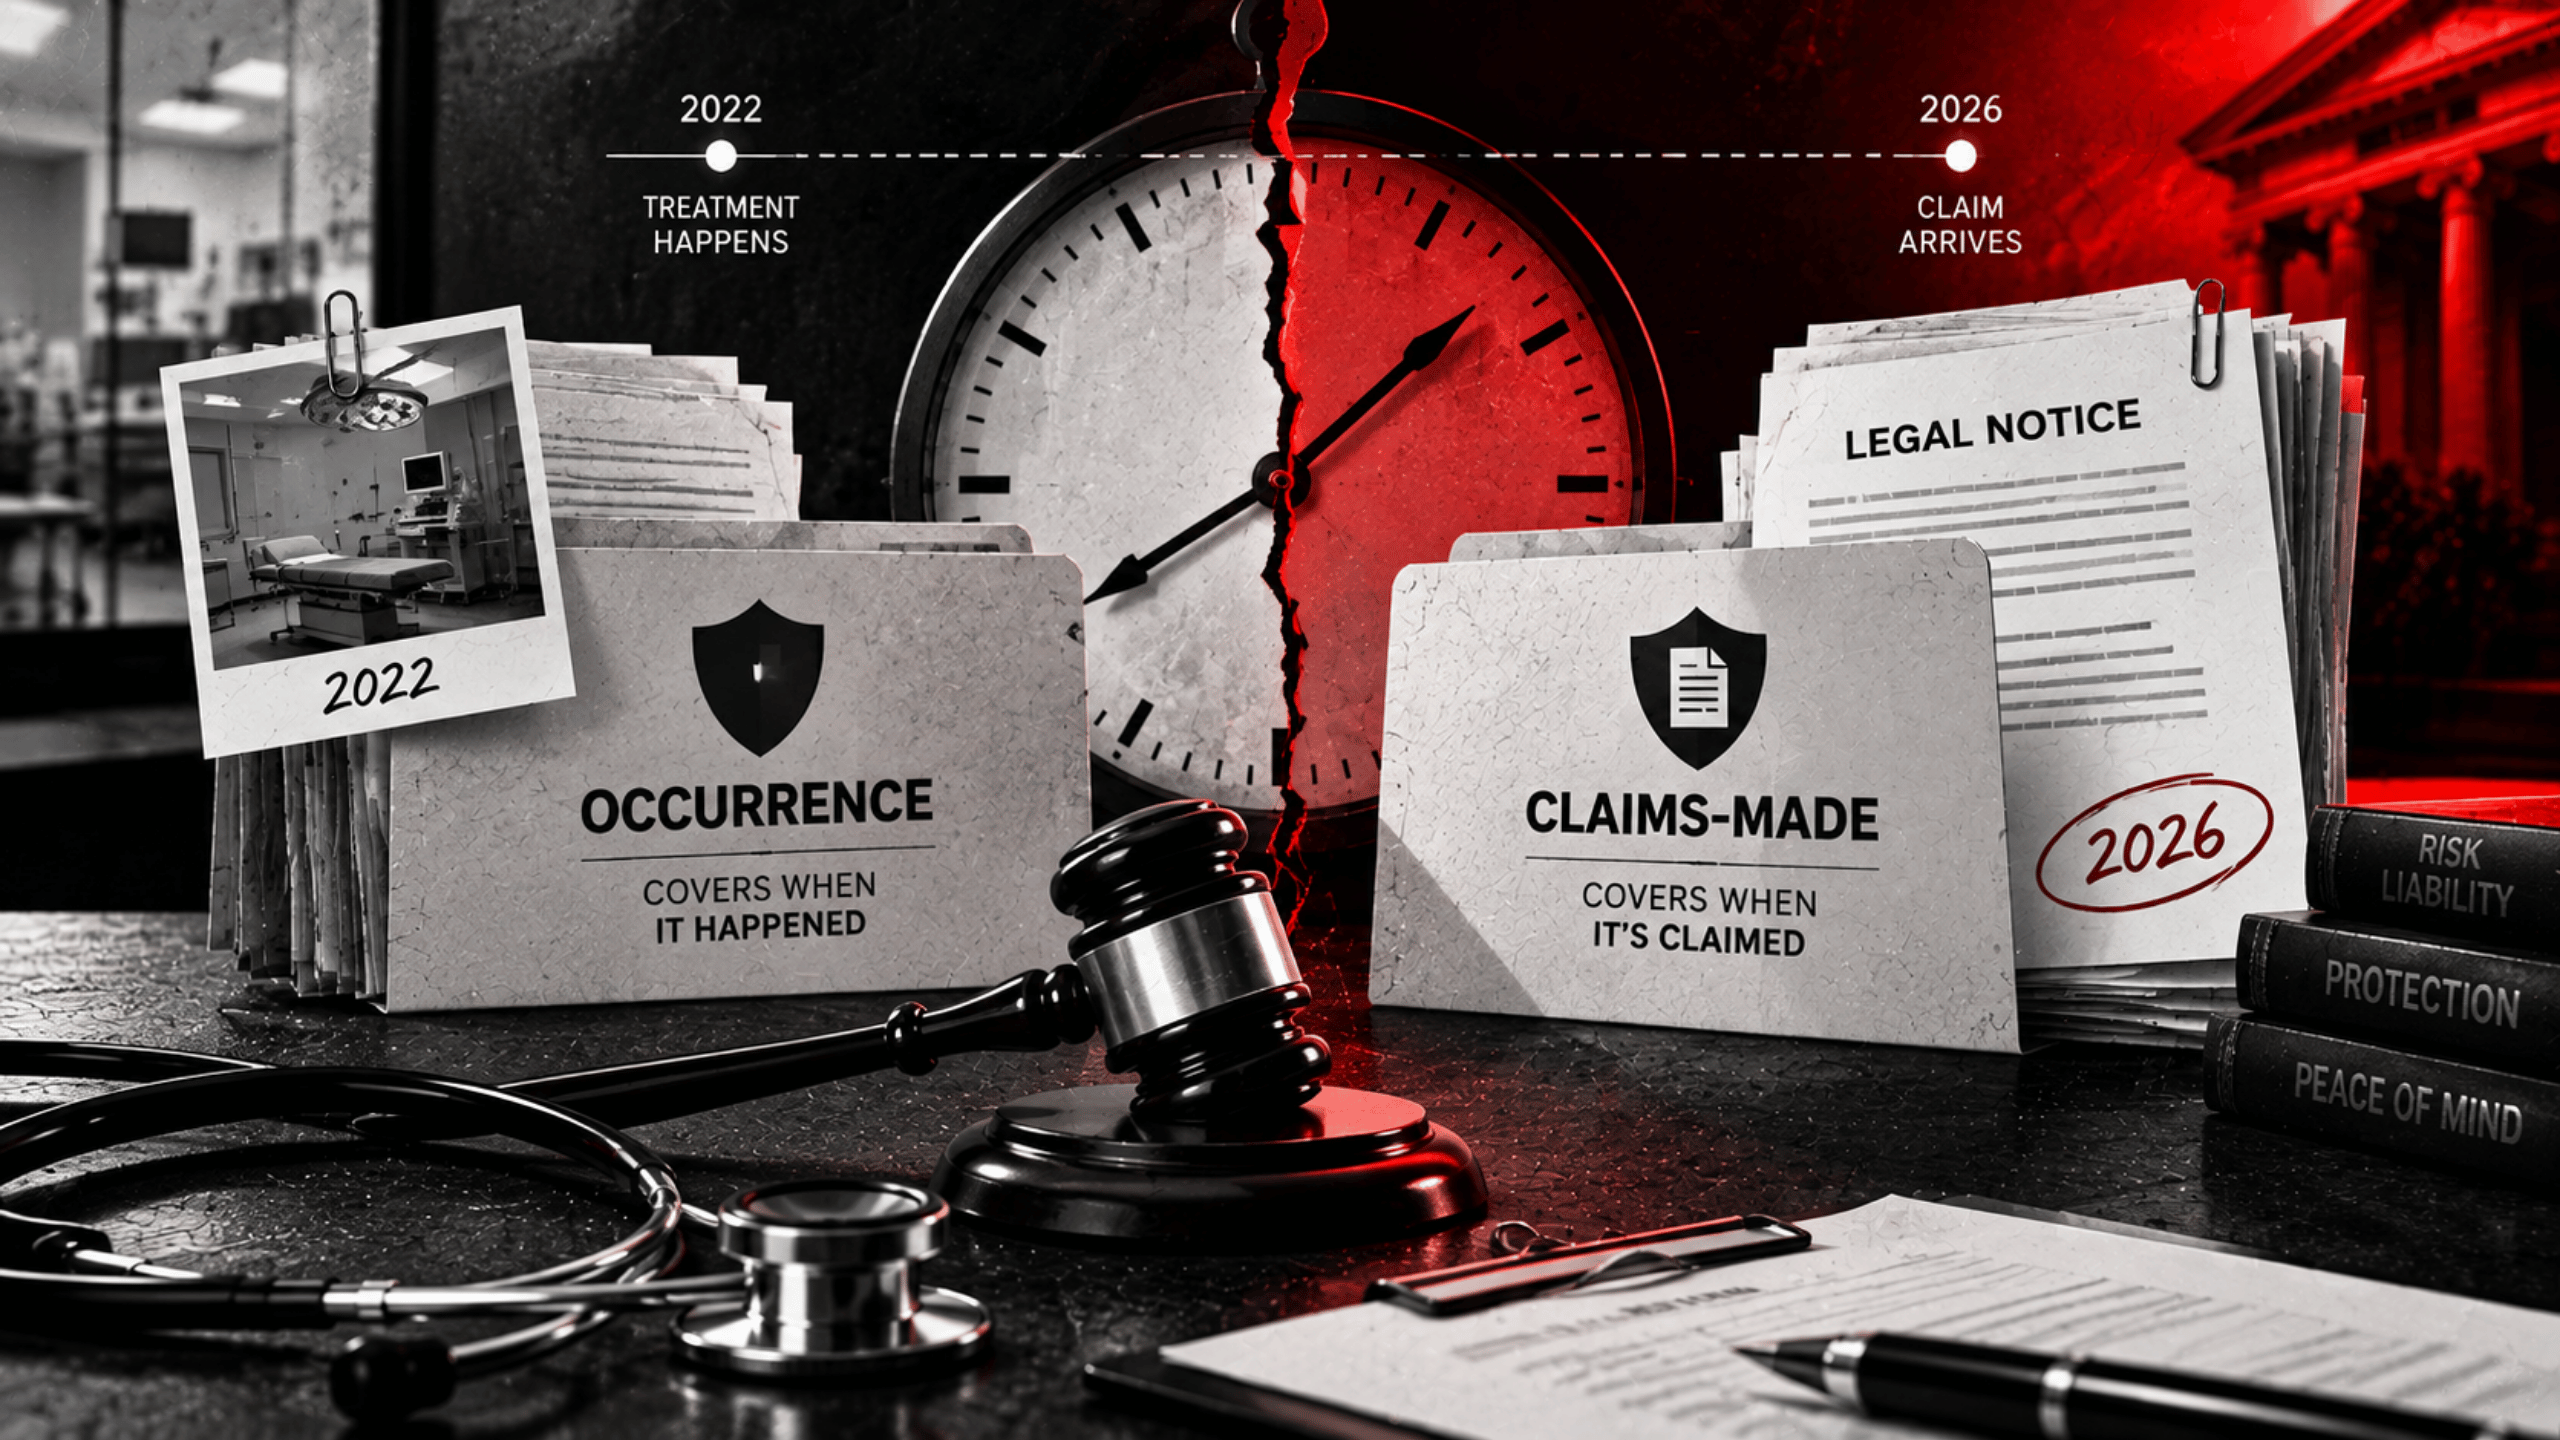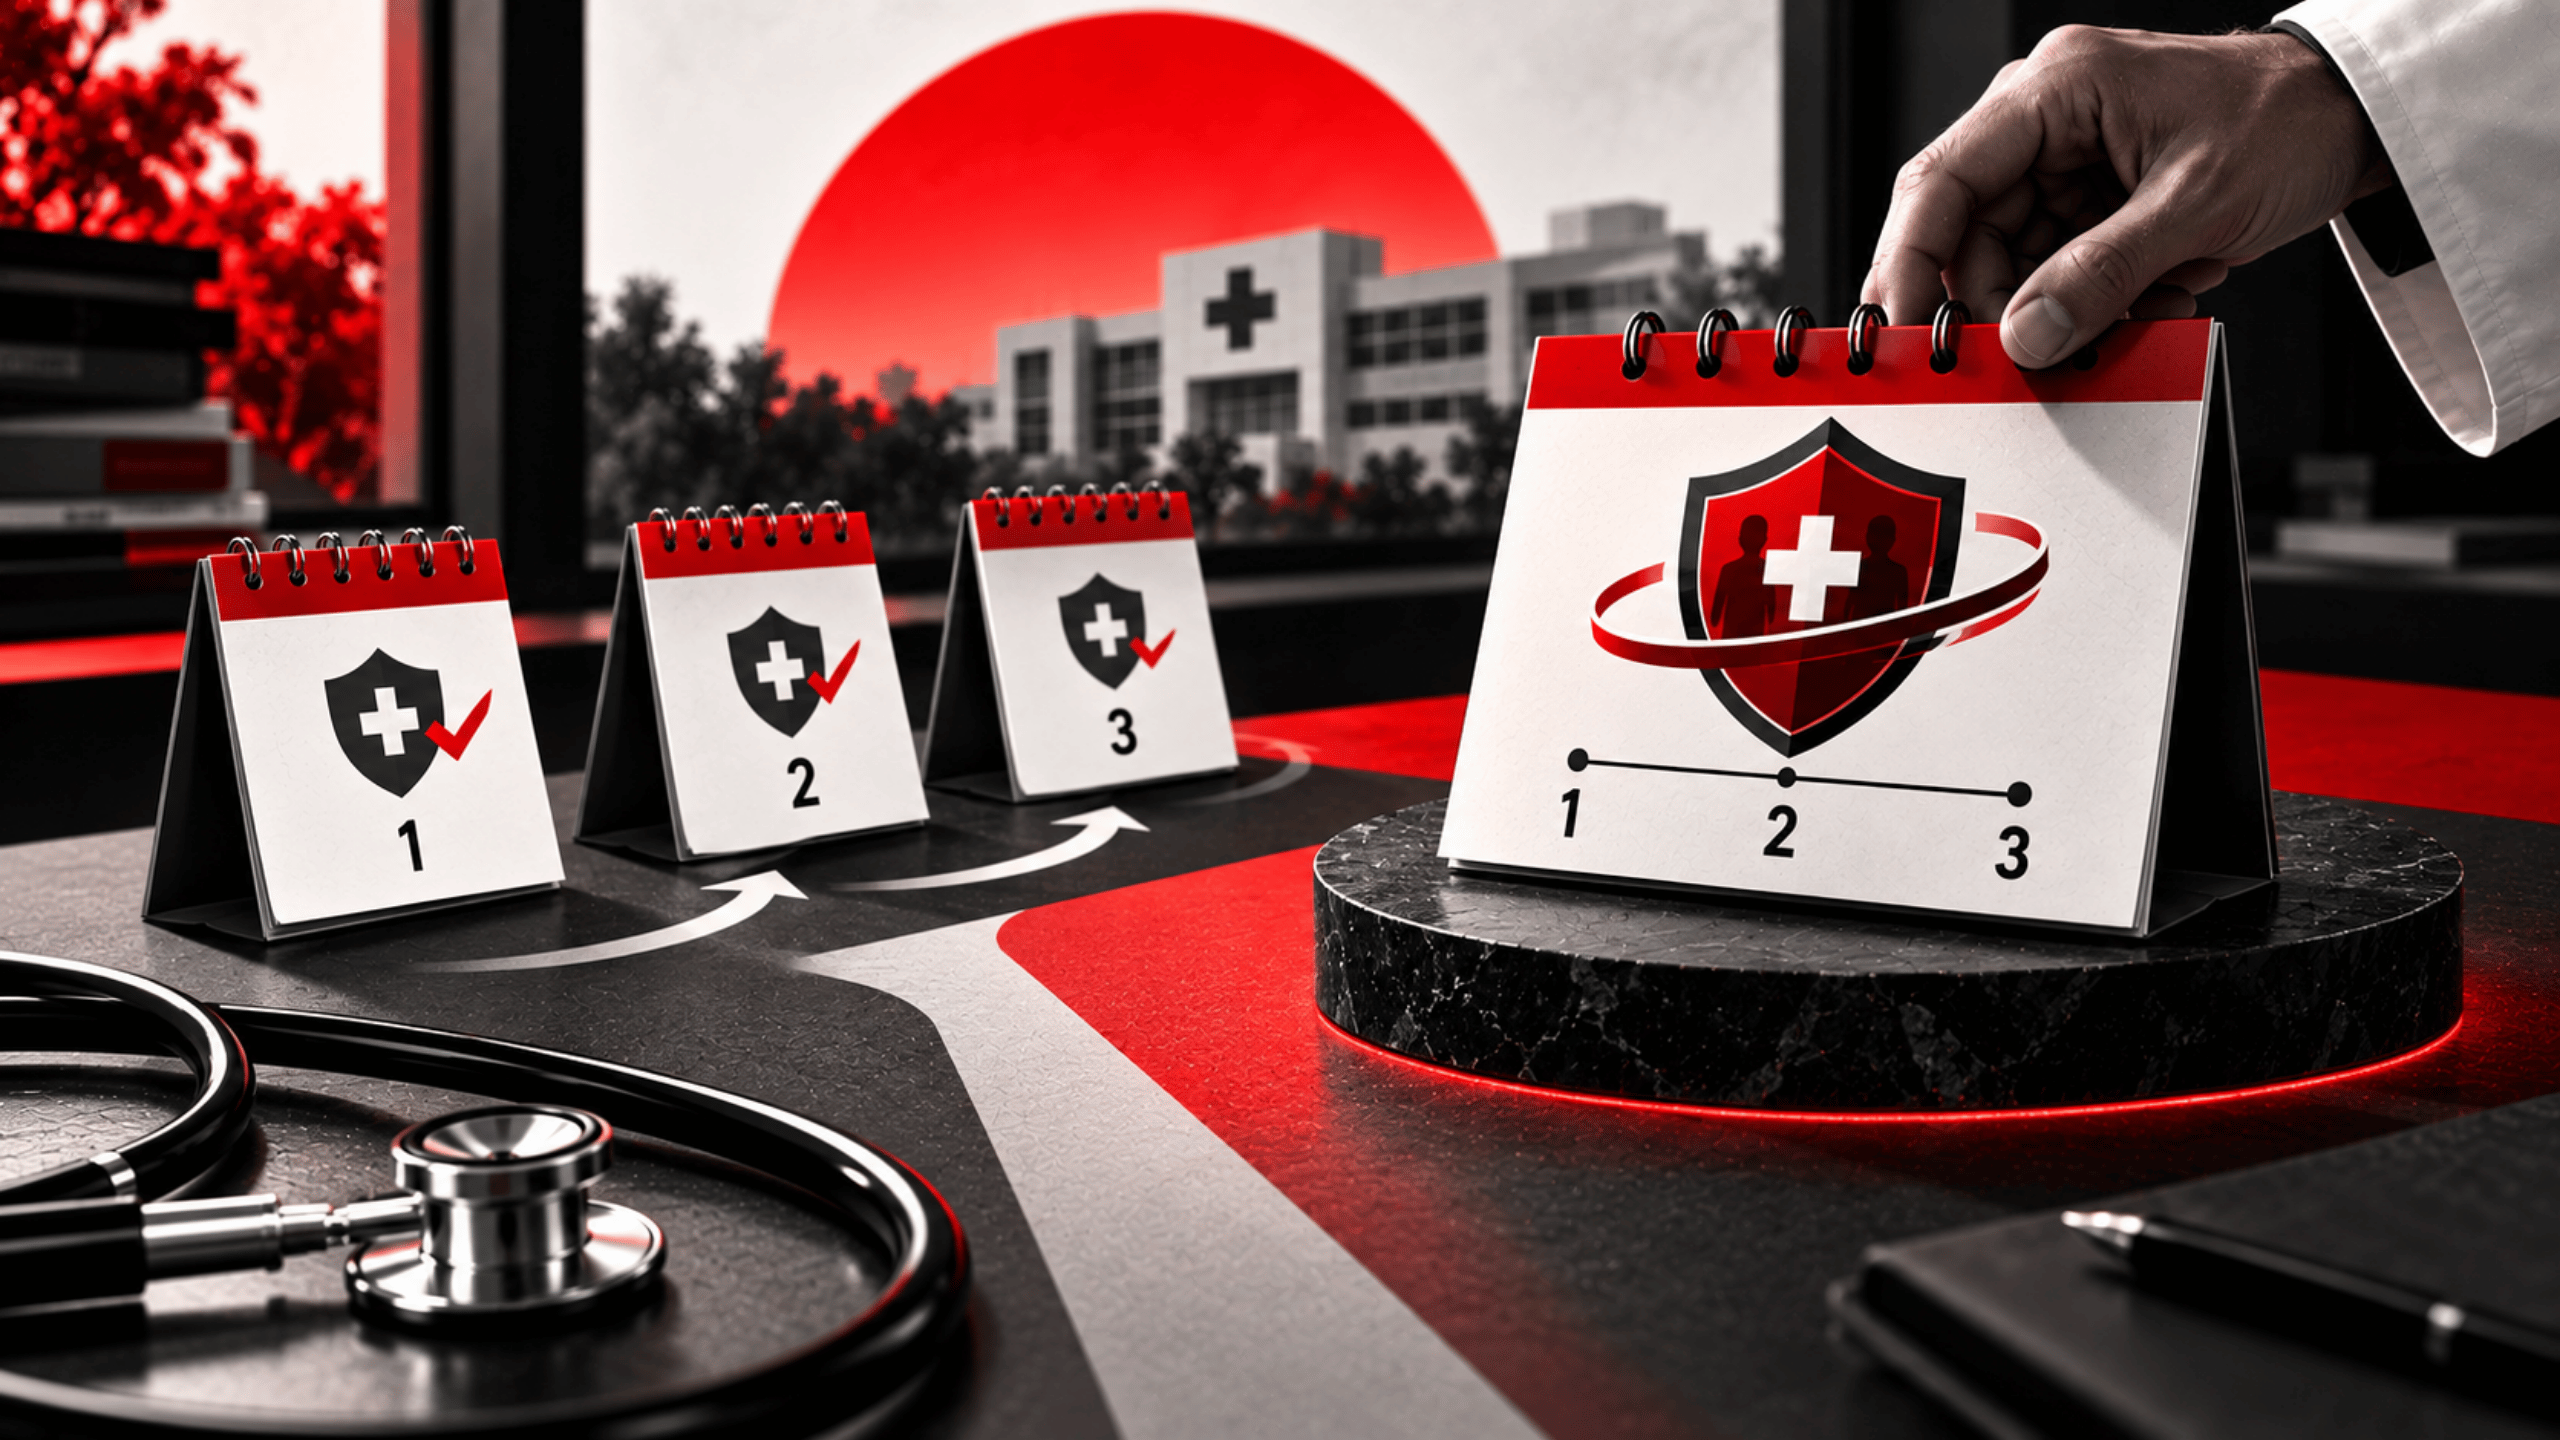
A broker sends you two different quotes for the exact same sum insured.
One document specifically says 1:1.
The other clearly says 1:4.
Furthermore, the second option is noticeably cheaper.
Nothing on either page actually explains what these specific numbers do.
Therefore, the massive temptation is to simply take the cheaper one and move on quickly.
However, getting the AOA AOY ratio professional indemnity explained properly saves you from massive financial disaster later.
Before you sign anything, you must absolutely understand what each number explicitly caps.
Consequently, you must understand exactly what the hidden gap between them actually costs you on a terrible day.
The Two Vital Numbers On Your Schedule
Indian professional indemnity wordings define both terms very directly. Specifically, these exact definitions dictate your entire financial protection. Therefore, you must review your policy document thoroughly. You can verify standard insurance definitions through the Insurance Regulatory and Development Authority of India (IRDAI) portal.
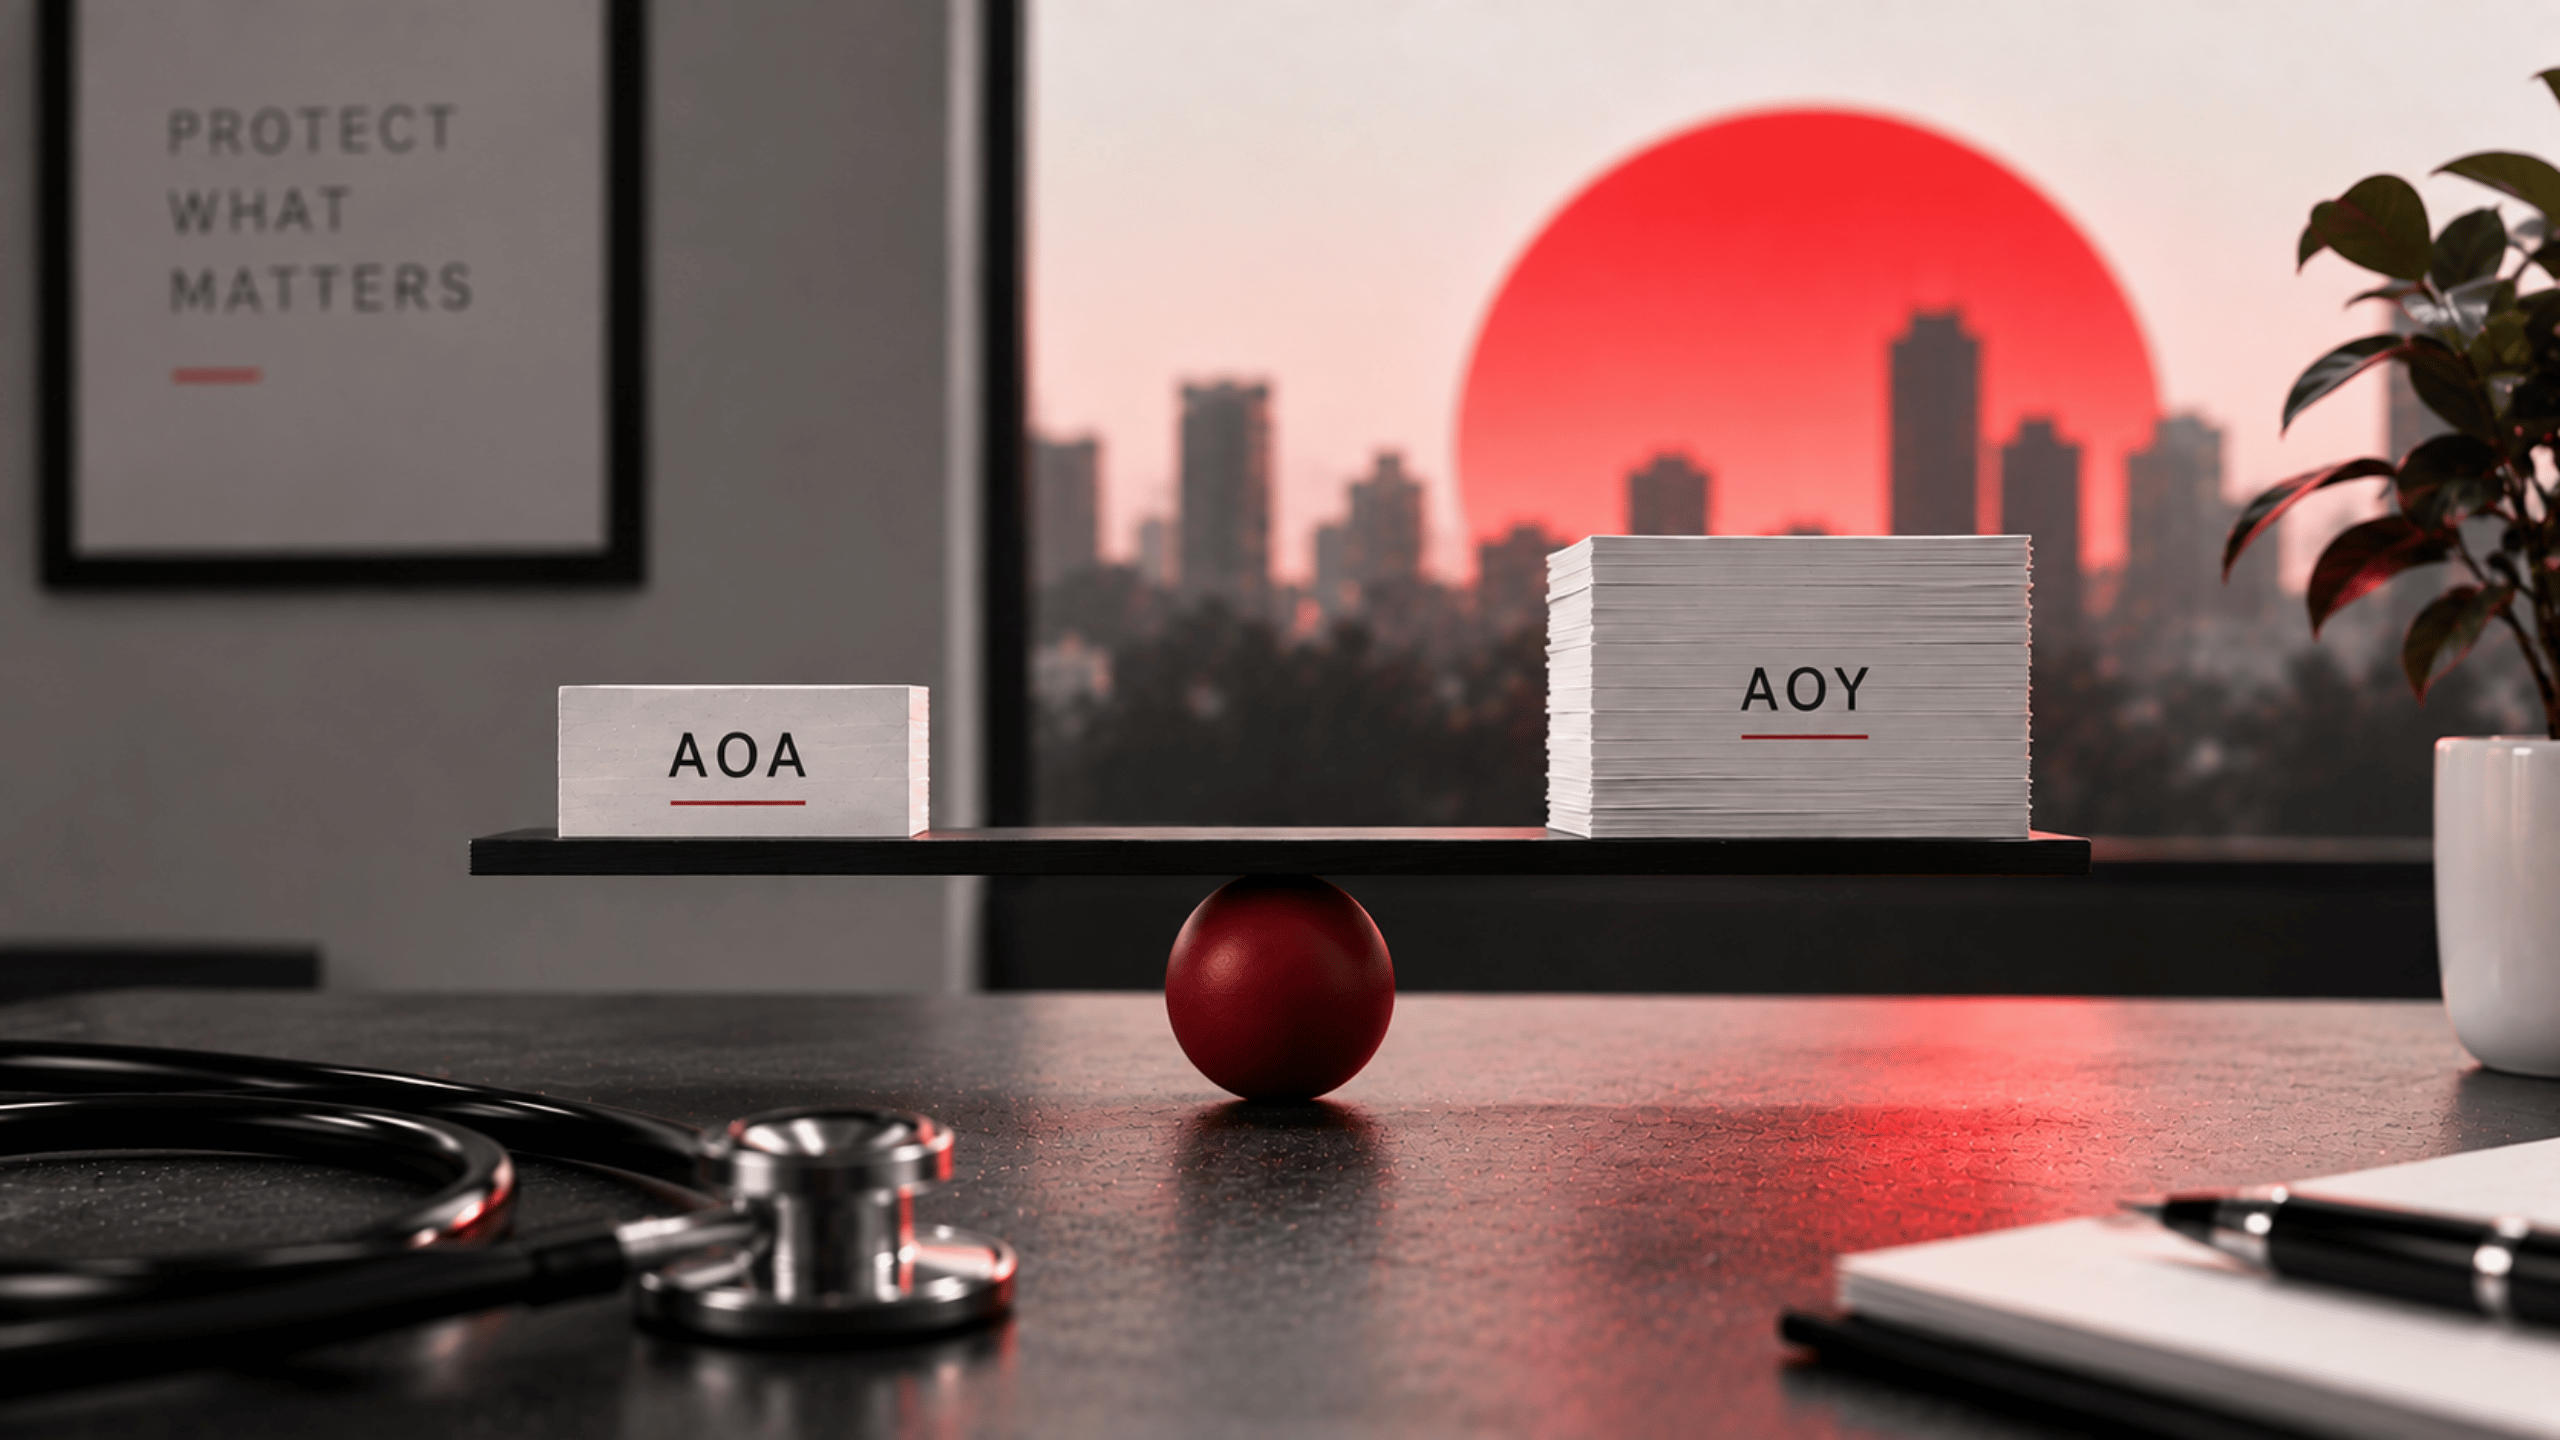
- AOA (Any One Accident): This is the strict indemnity limit applying to any one single claim. Furthermore, it applies to a series of claims arising from one originating cause.
- AOY (Any One Year): This is the total aggregate amount payable during the entire policy period across all claims.
Consequently, AOA is the strict financial ceiling on a single clinical event. Conversely, AOY is the absolute ceiling on the whole year. You are actively buying both limits simultaneously. Therefore, the mathematical relationship between them is the ratio.
The AOA AOY Ratio Professional Indemnity Explained In Practice
Reading the ratio is completely straightforward. Specifically, a 1:1 ratio strictly means one single claim can completely use the entire annual limit. Conversely, a 1:4 ratio clearly means any single claim is tightly capped at exactly a quarter of the annual aggregate.
Let us take an illustrative annual limit of exactly forty lakh. We are doing this purely to show the simple arithmetic. At 1:1, a single highly serious claim could immediately draw on the full forty lakh. However, at 1:4, the absolute most any one claim can draw is just ten lakh. Consequently, the remaining thirty lakh is available strictly for separate, unrelated claims.
These are purely illustrative figures, absolutely not a formal quotation. Furthermore, what they clearly show is the real financial trade. Specifically, a wider ratio strictly spreads your cover across significantly more potential claims. Conversely, a narrower one heavily concentrates it strictly behind the single claim most likely to severely hurt you. Always ensure your practice standards align with National Medical Commission (NMC) professional guidelines.
Which Specific Ratio Suits Your Medical Practice
With the AOA AOY ratio professional indemnity explained mathematically, the choice shifts completely. Specifically, it immediately becomes a careful judgement about your own daily practice. It is absolutely no longer a simple blind comparison of two numbers on a cheap quote.
Indian insurers commonly offer standard ratios of 1:1, 1:2, 1:3, and 1:4. Therefore, the absolute right choice follows directly from how claims are actually likely to arrive in your specific medical specialty.
- Few claims, high severity: Surgical and complex interventional work tends to produce fewer, much larger claims. Consequently, this heavily argues for a significantly higher AOA.
- More frequent, lower value: A high volume consulting practice may routinely see more claims of much smaller size. Therefore, a wider ratio safely stretches much further here.
- Hospital requirements: Empanelment contracts sometimes strictly specify a minimum sum insured. Specifically, check exactly what they say about sub-limits before actually choosing.
- Your own comfort: The critical question to sit with is exactly what a single worst case claim would actually cost. Conversely, do not simply calculate what an average one costs.
Essential Things To Be Highly Careful About
Three specific points are incredibly worth knowing before you compare any quotes.
First, absolutely no ratio is legally mandated. Specifically, no medical council rule strictly prescribes an exact ratio for doctors. Therefore, any intermediary telling you a particular ratio is strictly required should be heavily questioned. You must understand standard contract principles under the Indian Contract Act.
Second, market availability varies significantly. Insurers strictly apply their own internal underwriting appetite by medical specialty. Consequently, higher risk specialties are very often offered a much narrower AOA relative to the total annual aggregate.
Third, the ratio is absolutely not the only thing shaping what actually gets paid. Specifically, legal defence costs treatment, hidden sub-limits, and exclusions can matter just as much as the bold headline limits. Therefore, they sit deeply in the wording rather than on the simple quote.
What To Ask Before You Finally Choose
Ask for both exact figures formally written on the quotation. Do not just blindly accept the total sum insured. Ask explicitly whether legal defence costs are strictly within the limit or in addition to it. Furthermore, that single answer can drastically change what a limit is actually worth in clinical practice.
Ask exactly what specific ratios are actively available for your specialty. Do not just ask what is available in general. Finally, ask what your hospital empanelment contract strictly requires. Consequently, you are absolutely not blindly buying cover you already have. Furthermore, you are absolutely not falling short of a strict contractual minimum.
The Final Takeaway On Your Policy Limits
AOY is exactly what you can claim in an entire year. Conversely, AOA is exactly what you can effectively claim when a crisis actually matters. Therefore, pick the correct ratio strictly for your single worst possible day. Do not pick it for the average day. Ultimately, having the AOA AOY ratio professional indemnity explained clearly protects your entire medical career forever.
5 FAQ SECTION
What do AOA and AOY mean on an indemnity policy?
AOA is the limit for any one accident, applying to a single claim or a series arising from one originating cause. AOY is the aggregate limit payable across all claims during the policy period.
What does a 1:4 ratio actually mean?
It means any single claim is strictly capped at one quarter of the annual aggregate limit. The remaining amount stays available for other, separate claims during the exact same policy year.
Is any AOA:AOY ratio mandatory for doctors in India?
No mandate from IRDAI or the medical councils currently exists. Ratios are purely a product and underwriting matter, so ask your insurer exactly what is available for your specialty.
Which specific ratio is financially better for a surgeon?
There is absolutely no universal answer. Surgical practice tends to produce fewer but larger claims, which generally argues for a higher AOA. However, the right choice depends entirely on your specific practice.
Do legal defence costs come completely out of these limits?
That depends strictly on the policy wording. Some policies include defence costs within the limit, while others treat them completely separately. Ask the insurer to confirm it in writing before you buy.