help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

When the Insurer Will Not Defend

coveryouadmin by coveryouadmin
October 22, 2026
in Blog
Reading Time: 4 mins read
0 0
0
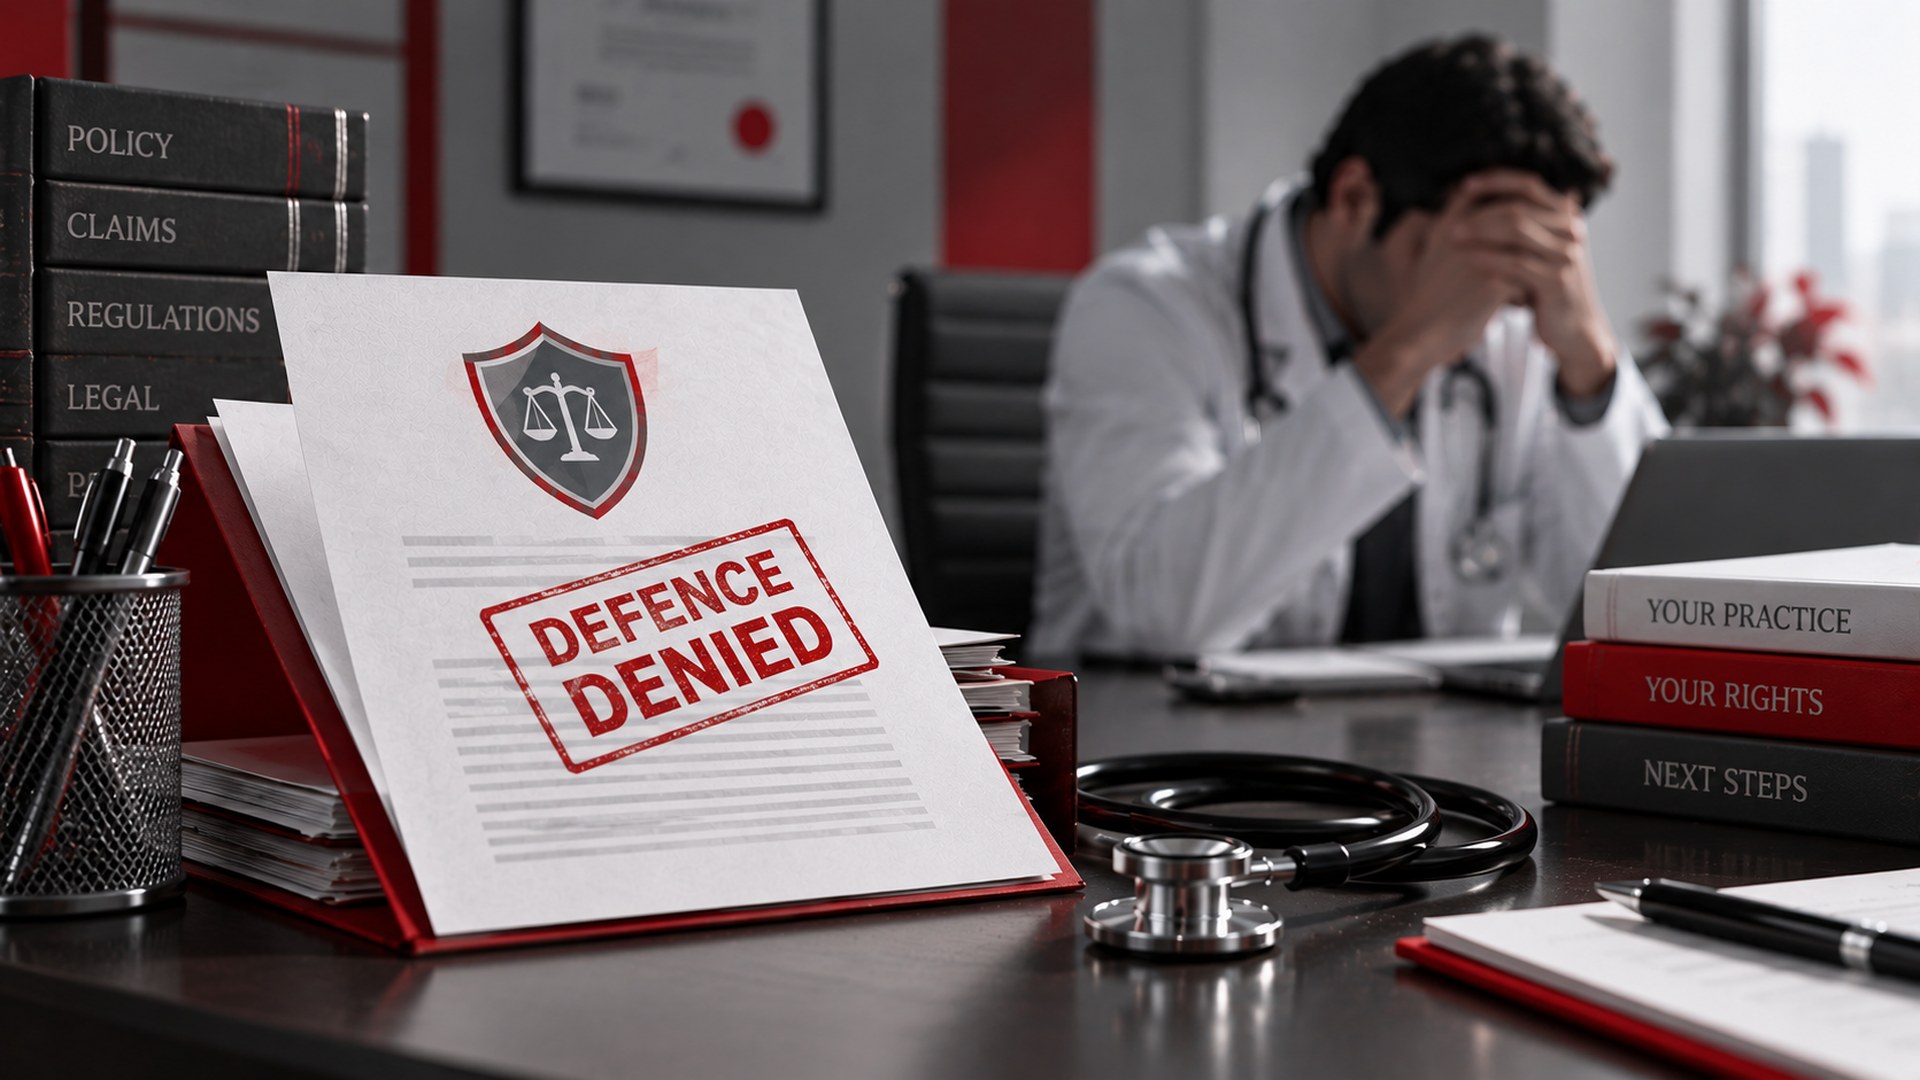
Medical professional sitting at a desk with a legal document stamped “Defence Denied,” representing professional indemnity claim challenges

When a medical negligence claim arises, a denied defence can put a doctor’s professional reputation and practice at risk.

You did everything in the right order. Notified the same week. Sent the case sheet, the consent form, the whole file. The reply, when it comes, is one paragraph and does not offer you a lawyer.

Discovering that an insurer refused to defend medical negligence case work is a particular kind of cold, because you assumed the policy meant representation. Read the wording and you find it mostly did not promise that.

Read The Verb In Your Own Policy

Indian professional indemnity wordings say the insurer has the right, but in no case the obligation, to take over and conduct the defence in your name.

Right, not duty. That single word is the difference between an insurer that must show up and one that may choose to. One corporate product examined does impose a duty to defend — but it is the exception, and it is not a doctors’ retail policy.

Which means a refusal to run your defence is not necessarily a breach of anything. It may be the policy working exactly as drafted.

It also means the sentence “my insurer refused to defend medical negligence case proceedings against me” describes two very different situations, and the difference decides what you do next.

Refusing To Defend Is Not The Same As Refusing To Pay

Separate the two, because doctors conflate them and lose time.

  • Declining conduct: The insurer chooses not to run the defence, but the claim may still be covered and costs may still be recoverable with consent.
  • Repudiating the claim: The insurer says the claim is not covered at all — scope, exclusion, disclosure, retroactive date.
  • Reserving rights: The insurer defends while preserving the right to decline later, which is a third position and should be put in writing.
  • Walking away mid-matter: A separate mechanism, discussed below, that catches people by surprise.

Ask which one you are in, in writing, and do not accept an answer that blurs them.

The Clause That Lets Them Leave Later

This one is worth knowing before it happens, because almost nobody reads this far into the conditions.

Indian wordings let the insurer pay you the remaining limit of indemnity — or any lesser sum for which the claim could be settled — and on making that payment, relinquish conduct and control of the matter and be under no further liability.

In plain terms: the insurer can hand over what is left of the cover and withdraw, mid-litigation, from a defence its own lawyers have been running. Once the limit is exhausted, everything after that is funded by you.

It is a lawful contractual right rather than bad behaviour, and it is the version of insurer refused to defend medical negligence case that arrives with no warning at all — two years in, rather than in the first month.

What To Do In The First Fortnight

  • Get the ground in writing: The clause relied on, and whether cover itself is accepted or declined.
  • Ask about consent separately: If they will not conduct the defence, will they consent to your counsel and your costs?
  • Do not incur fees first: Costs without prior written consentmay be unrecoverable.
  • Keep meeting your duties: Notification and co-operation obligations continue even while you dispute the position.
  • Start the clock on escalation: The grievance route has deadlines that do not pause for the court.

If the position turns into a repudiation, the escalation route runs from the insurer’s grievance officer to Bima Bharosa and then the Insurance Ombudsman, where an award binds the insurer.

The Answer

When an insurer refused to defend medical negligence case work, the first question is never whether that was allowed. It usually was.

The question is whether the claim is still covered — so get that answer in writing, and get consent for counsel before anyone sends a bill.

Frequently Asked Questions

Is my insurer obliged to defend me?

Usually not. Most Indian doctors’ wordings give the insurer a right, but not an obligation, to take over the defence. One corporate product examined imposes a duty, so check which yours is.

If they will not defend me, is my claim still covered?

Possibly. Declining to conduct the defence is different from repudiating the claim. Ask the insurer to state, in writing, whether cover is accepted and whether costs will be consented to.

Can an insurer stop defending part-way through?

Indian wordings allow the insurer to pay the remaining limit, or a lesser settlement sum, and then relinquish conduct and be under no further liability. From that point the defence is self-funded.

Can I appoint my own advocate if they refuse?

You can instruct counsel, but recovery of those costs depends on the insurer’s prior written consent. Ask for consent explicitly, in the same letter.

What if I think the refusal is wrong?

Escalate through the insurer’s grievance redressal officer, then IRDAI’s Bima Bharosa portal, then the Insurance Ombudsman, which can entertain complaints up to fifty lakh rupees and whose award binds the insurer.

Do my duties under the policy continue while we disagree?

Yes. Notification, co-operation and consent obligations continue even while the coverage position is being disputed.
Tags: Bima Bharosa IRDAIclaim repudiation doctorsconduct of defence clausedefence costs indemnitydoctor legal protectiondoctor liability insuranceduty to defend insurance Indiahealthcare risk managementinsurance dispute Indiainsurance ombudsman complaintinsurer refused to defend medical negligence casemedical malpractice cover Indiamedico legal defencepolicy conditions doctorsprofessional indemnity India
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

How Fast Must You Report It?

Next Post

Settling Without Losing Your Cover

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Doctor discussing written consent requirements with patients in a medical-legal setting, highlighting informed consent and professional indemnity risks.
Blog

Settling Without Losing Your Cover

October 22, 2026
Stressed doctor holding his head behind a desk with a legal envelope, stethoscope, hourglass, and a calendar marking dates 4 to 26 labeled “Still not reported”
Blog

How Fast Must You Report It?

October 20, 2026
A legal settlement concept showing money being exchanged, a Lady Justice statue, and a stack of legal documents against a city skyline at sunset.
Blog

Upfront or Reimbursed?

October 20, 2026
Medical professional indemnity concept featuring a balance scale, medical and legal professionals, clinical expertise, policy conditions, claims process, and risk management.
Blog

Who Picks the Lawyer?

October 15, 2026
Clock beside a pending medical indemnity insurance claim file, illustrating delays in claim review and settlement.
Blog

How Long Does a Claim Actually Take?

October 12, 2026
Doctor reviewing a rejected medical indemnity insurance claim alongside policy documents, exclusions and legal considerations.
Blog

Your Claim Was Rejected. Now What?

October 12, 2026
Next Post
Doctor discussing written consent requirements with patients in a medical-legal setting, highlighting informed consent and professional indemnity risks.

Settling Without Losing Your Cover

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Settling Without Losing Your Cover
  • When the Insurer Will Not Defend
  • How Fast Must You Report It?
  • Upfront or Reimbursed?
  • Who Picks the Lawyer?

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In