Pull up your policy schedule.
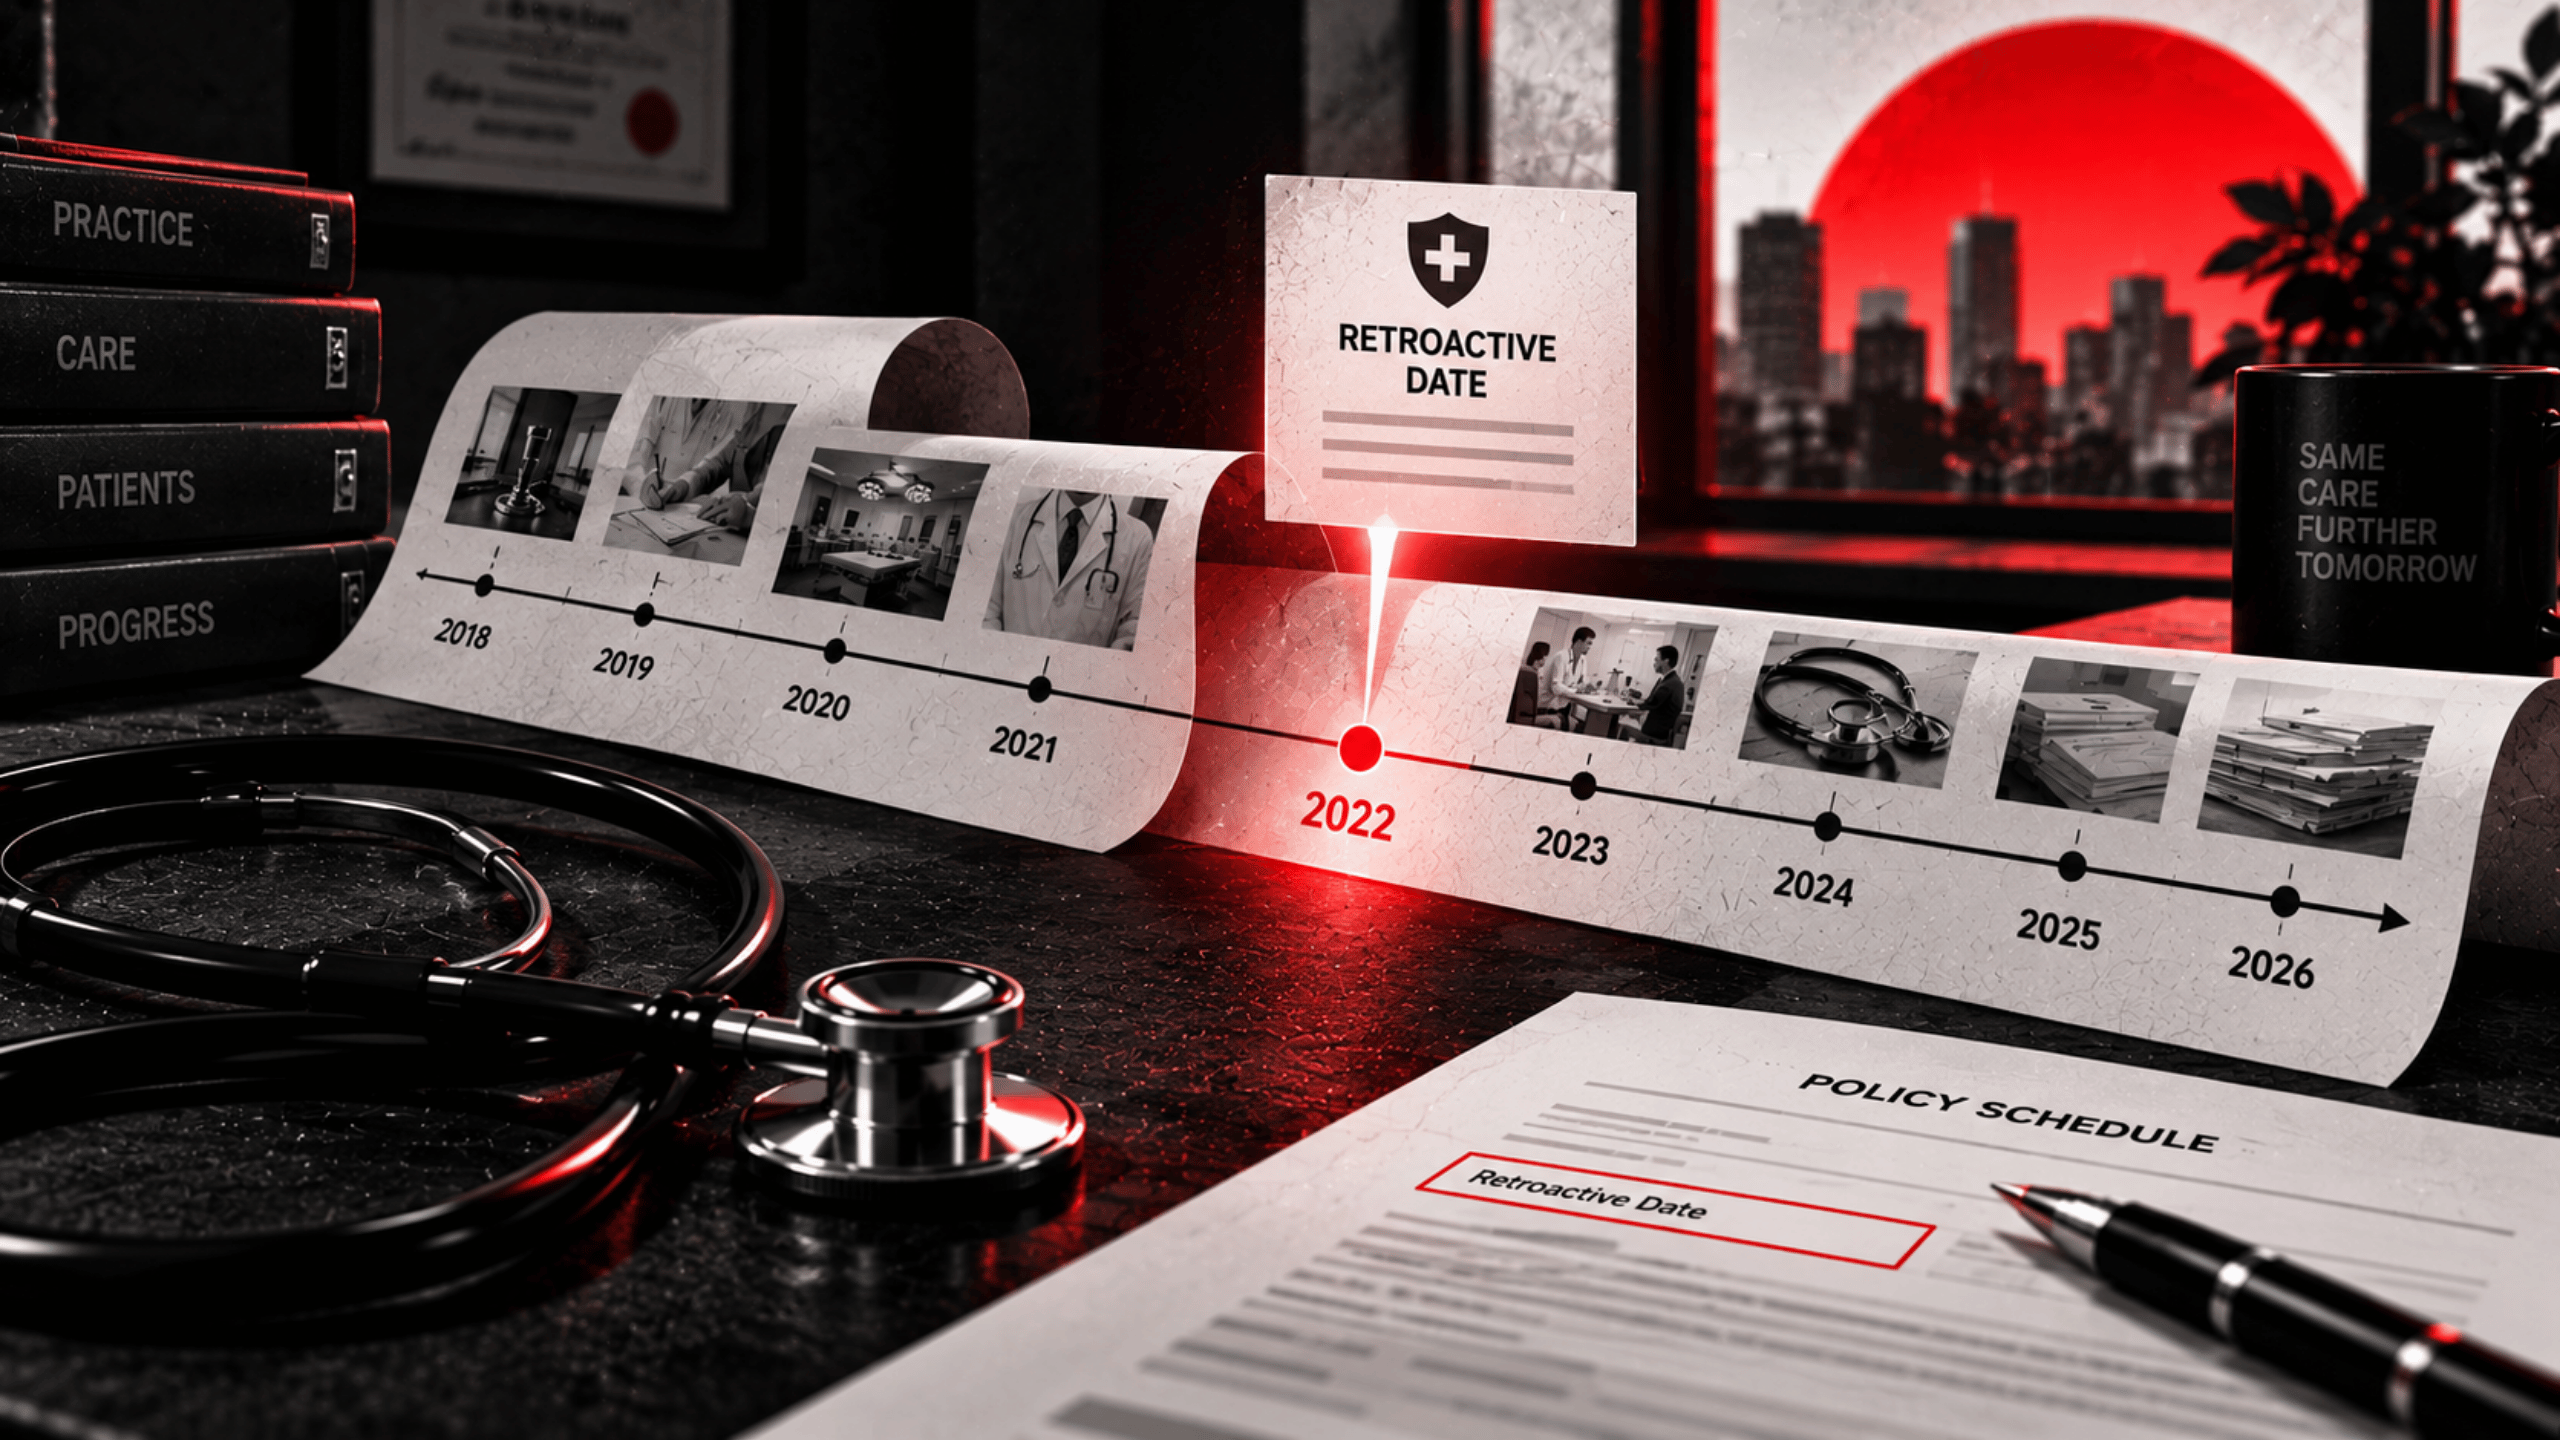
Somewhere below the sum insured, in the same small type as everything else, there is a field marked retroactive date.
Most doctors have never looked at it, and it is the single line on the page that decides whether eight years of your work is insured or not.
Specifically, the retroactive date professional indemnity meaning is simple enough to explain in a sentence.
Therefore, it is consequential enough to be worth ten minutes of your evening.
What The Date Does
Indian professional indemnity wordings define it directly: the date on which the risk incepted under a claims made policy, and thereafter renewed without a break in the period of cover.
Its function is exclusionary. Wordings exclude any claim arising from an act committed, or alleged to have been committed, before the retroactive date shown in the schedule. You can read more about official policy definitions and exclusionary clauses on the Insurance Regulatory and Development Authority of India (IRDAI) portal.
So the date draws a line across your career. Everything after it can be covered. Everything before it cannot, by any policy you hold today.
Why Two Clocks Have To Agree
This is where the date stops being a technicality and starts being the thing a claim turns on. Consequently, grasping the full retroactive date professional indemnity meaning becomes crucial here.
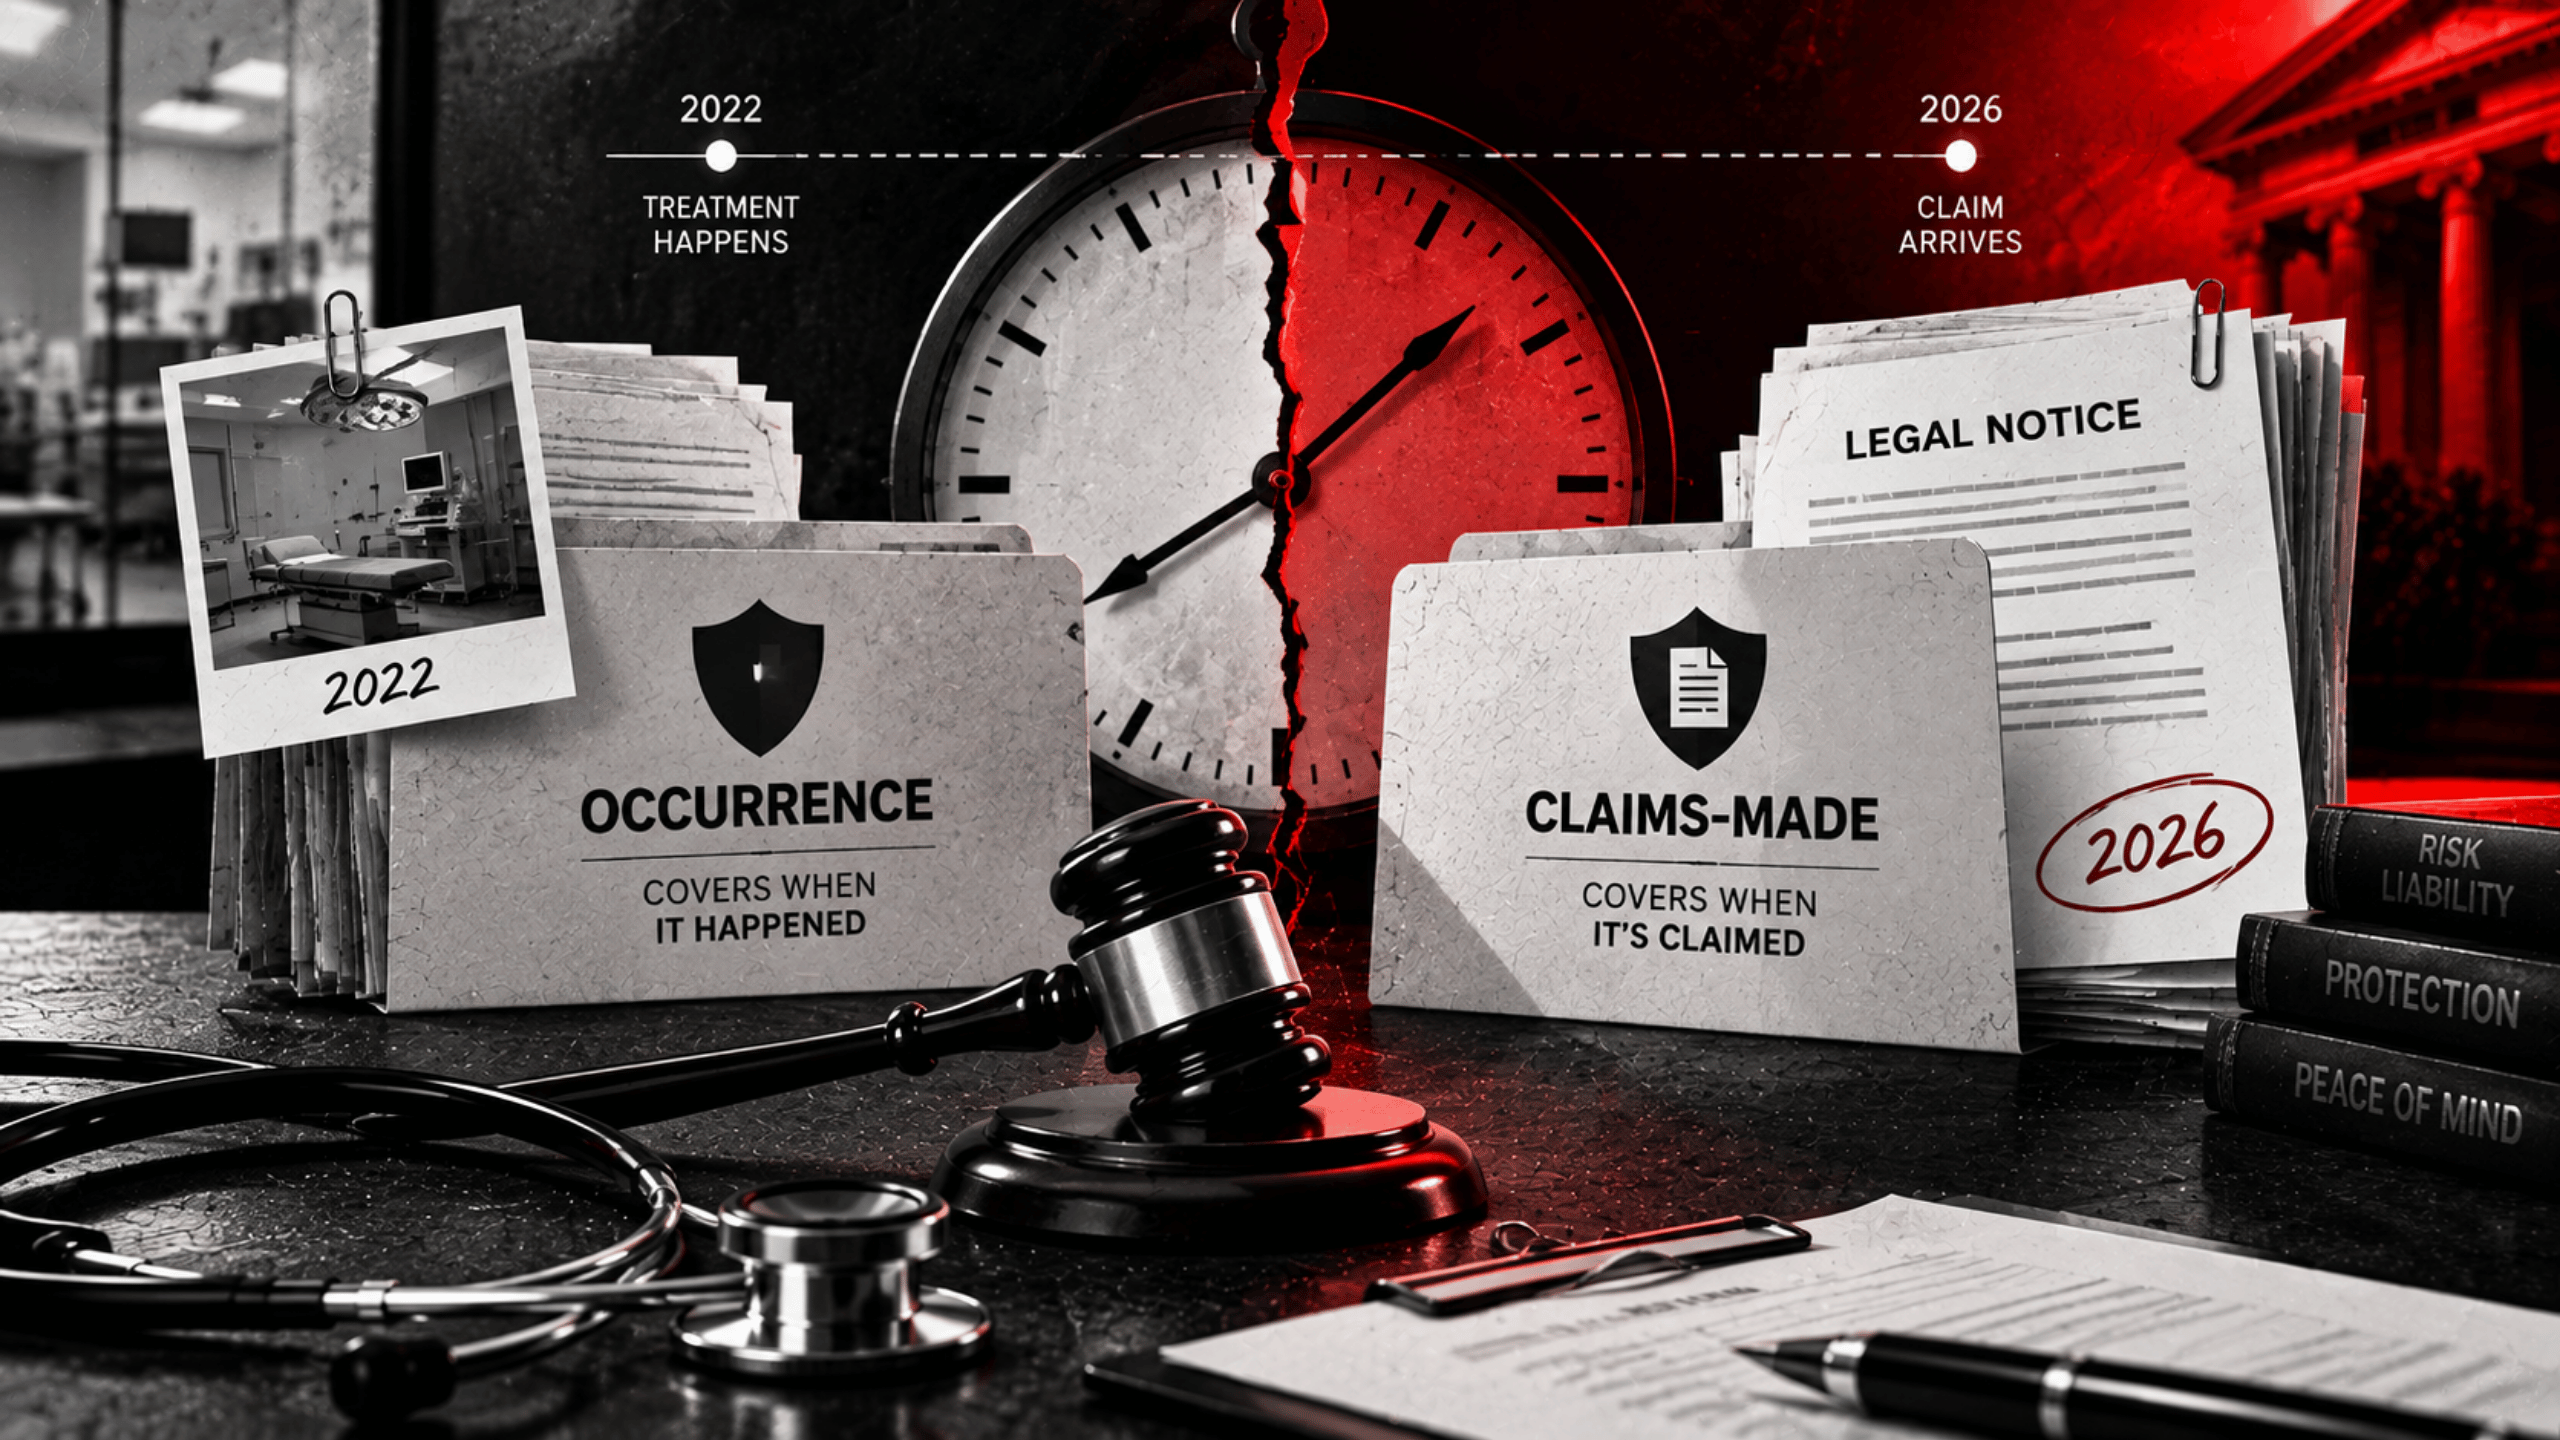
Claims made cover needs two conditions satisfied at once, and doctors usually only track one of them.
- The policy must be live: Active on the day the claim is first made against you in writing.
- The treatment must qualify: Performed on or after the retroactive date on that schedule.
A claim about a 2021 surgery, filed today, needs a live policy today and a retroactive date reaching back to 2021. One without the other fails. Always align your practice with proper doctor liability insurance standards.
What Keeps It Where It Is
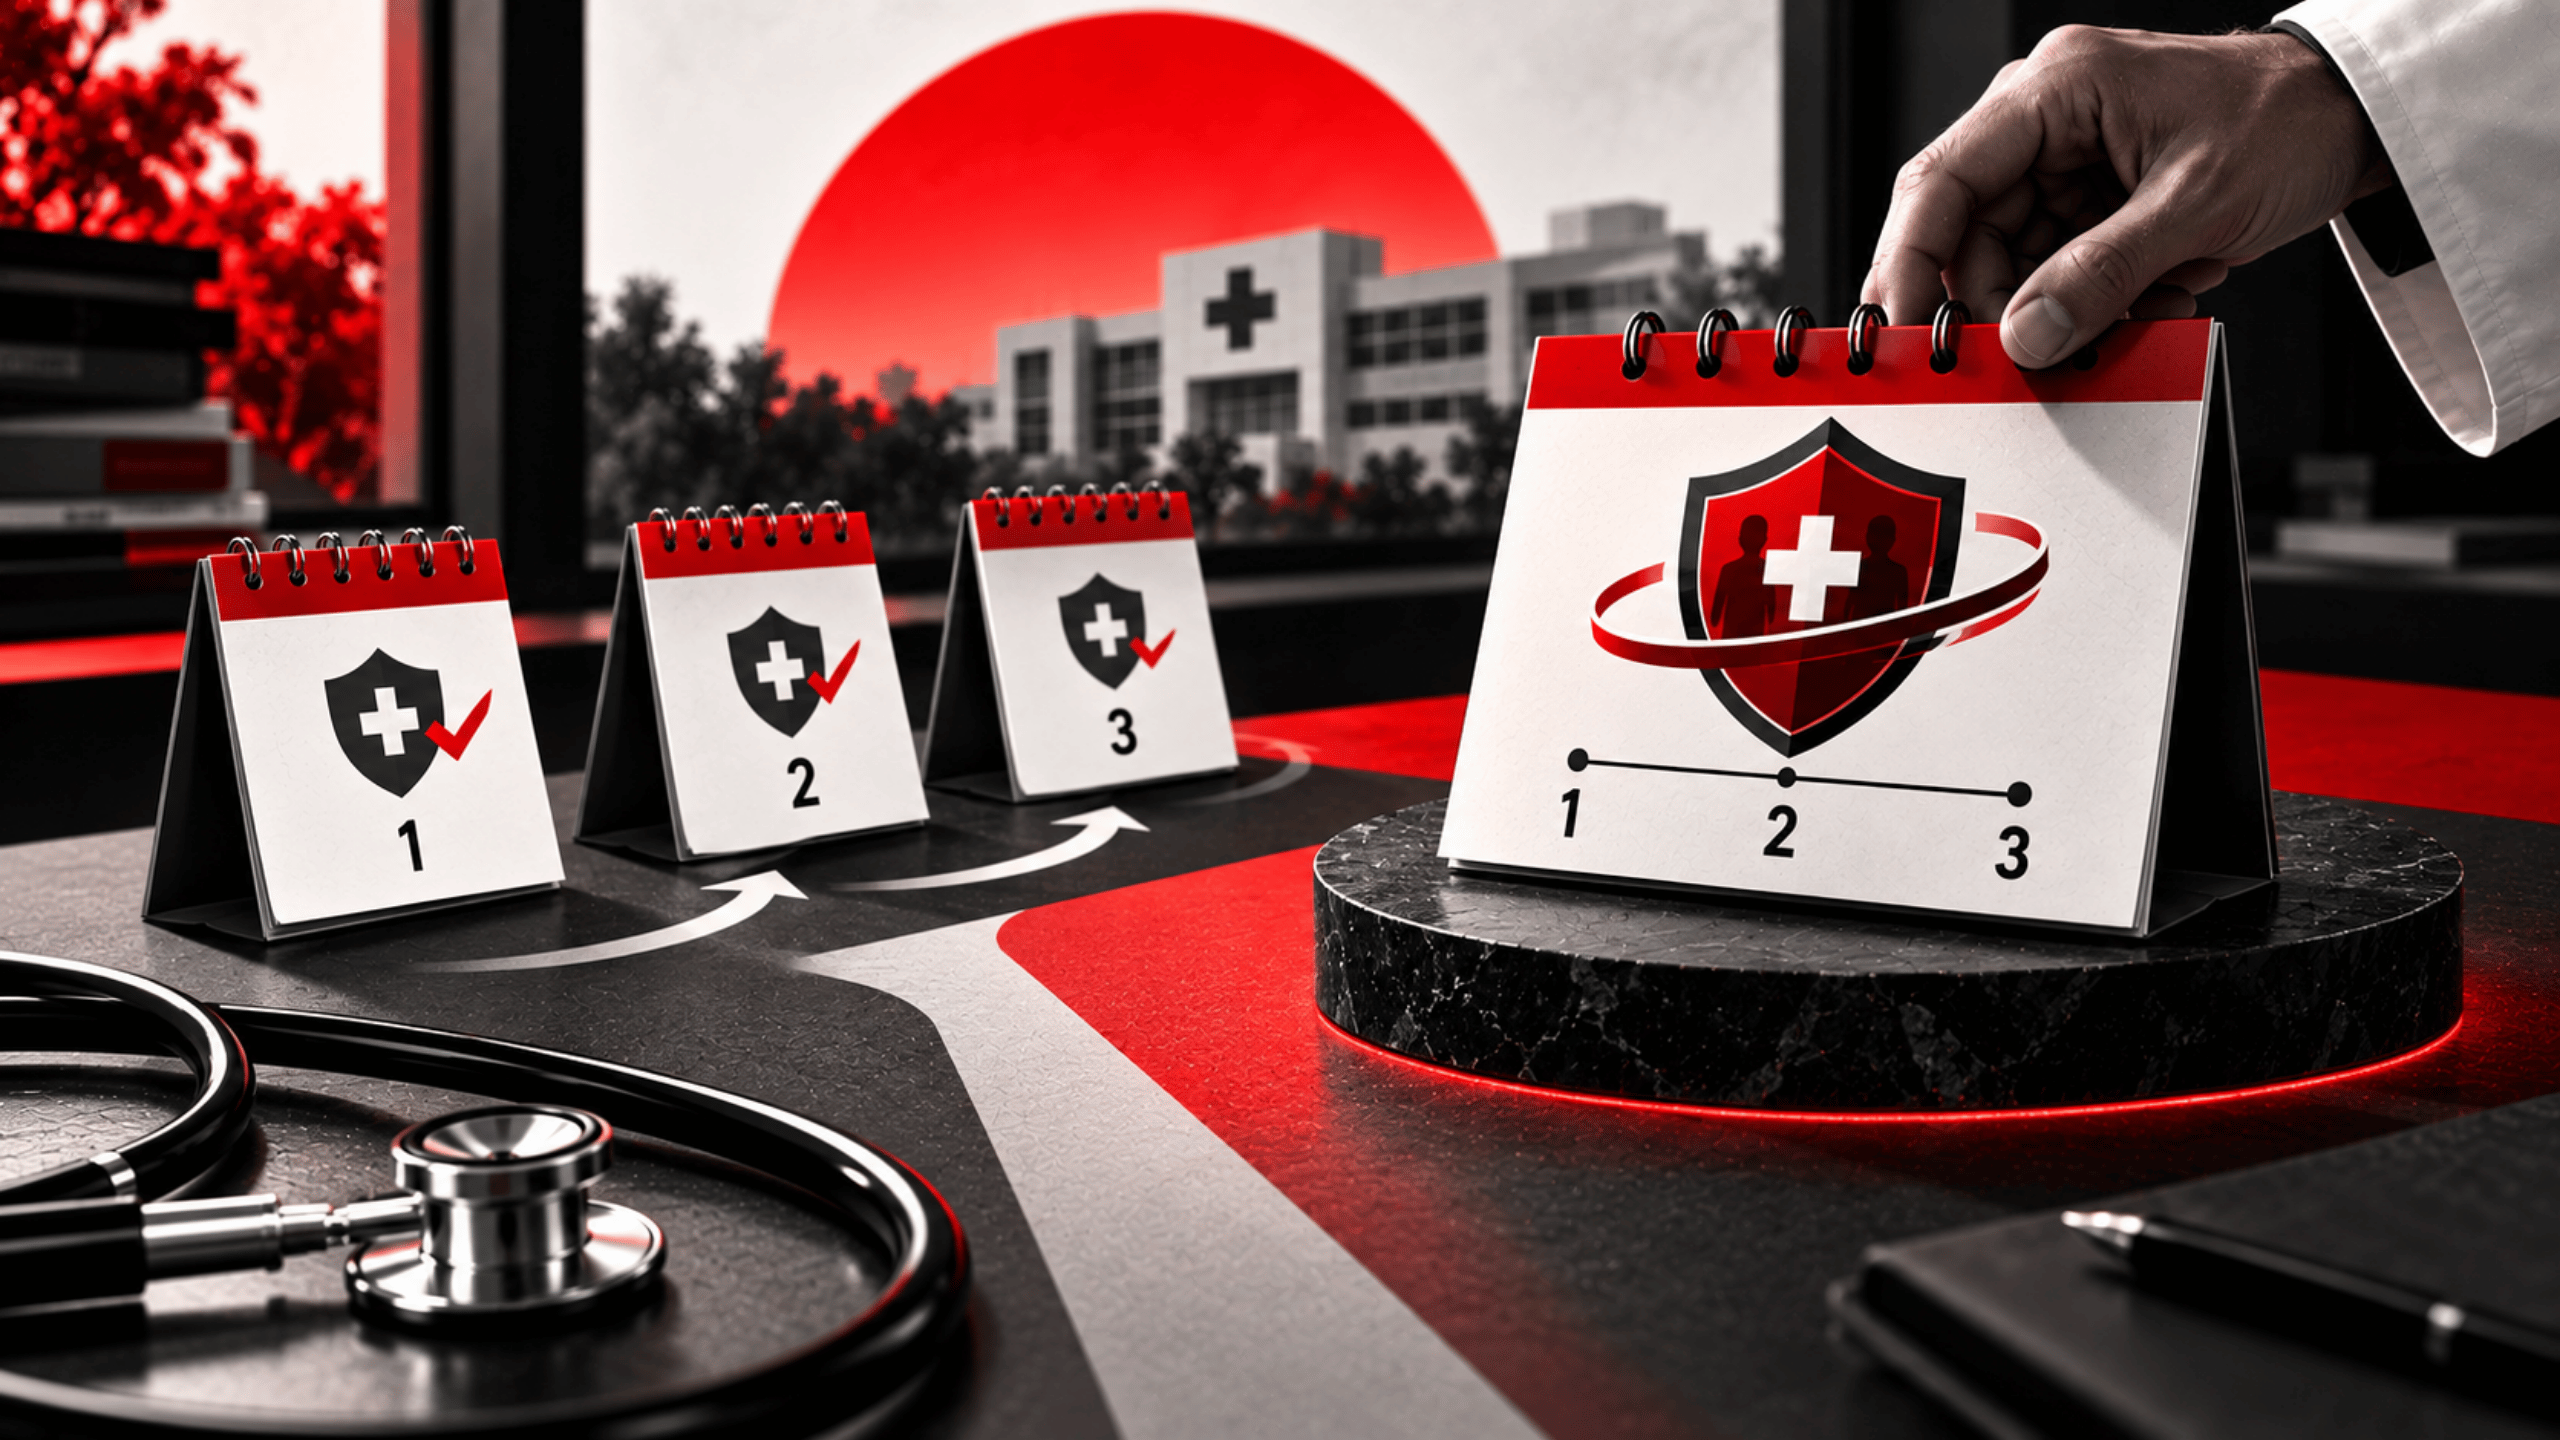
Unbroken renewal. That is the whole mechanism, and the retroactive date professional indemnity meaning is built around it, specifically renewed without a break in the period of cover.
Renew on time, year after year, and the date stays frozen at your first policy’s inception even as you change sum insured, add a specialty, or move to a different insurer. Each renewal buys another twelve months of cover and quietly extends the value of a date you set once, years ago, probably without noticing.
That is why a doctor eighteen years into continuous insurance coverage holds something a doctor who bought a first policy last week cannot buy at any price. The premium is comparable. The reach is not.
What Puts It At Risk
Three things, all avoidable, and all of them administrative rather than clinical.
- A lapse: A break in cover breaks the continuity the definition depends on.
- An undocumented switch: A new insurer needs prior policy schedules to carry your existing date forward. Without them, the date is set at the new inception.
- Not checking the new schedule: If the date is not printed on the policy you were issued, it does not exist, whatever was discussed on the phone.
Confirm the position in writing before you pay, and read the schedule the day it arrives, while an error can still be corrected without anyone having to argue about what was intended. Ensure your record keeping complies with the National Medical Commission (NMC) guidelines.
None of those three failures involves a clinical decision. They are diary entries and document requests, which is what makes them frustrating to lose a decade of cover to.
The Ninety Second Check
Open your current schedule and answer two questions. Does the retroactive date match the inception of your very first policy? And can you produce the schedules that prove the chain between them?
If the answer to either is no, that is the most valuable conversation you will have with your broker this year.
The Takeaway
Your premium buys the next twelve months.
Your retroactive date is everything you have already paid for.
Protect it the way you would protect a record, by never letting the chain break. Furthermore, understanding the exact retroactive date professional indemnity meaning secures your entire medical legacy.
5 FAQ SECTION
What does the retroactive date on my policy mean?
It is the date from which your cover can respond to past work. Indian wordings exclude claims arising from acts committed before the retroactive date shown on the schedule.
Is the retroactive date the same as my policy start date?
Not necessarily. For a first policy they usually coincide. On continuous renewal the retroactive date stays at the original inception while the policy period moves forward each year.
How do I keep my retroactive date unchanged?
Renew without any break in cover. The definition itself refers to a policy renewed without a break in the period of cover, so continuity is what preserves it.
What happens to it if my policy lapses?
A break in cover breaks continuity, and the date is generally set afresh at the new policy’s inception. Confirm the position with your insurer, as treatment is contractual.
Can a new insurer keep my existing retroactive date?
Typically yes, where you can evidence unbroken prior cover with your previous schedules. Ask for the date to be confirmed in writing and check it appears on the new schedule.