help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

The Exclusions Page, in Plain Language

coveryouadmin by coveryouadmin
September 17, 2026
in Blog
Reading Time: 4 mins read
0 0
0
The Exclusions Page, in Plain Language

Your policy protects you—but exclusions define where that protection stops.

Nobody actively reads it.

It sits four or five pages deep into the policy wording.

Specifically, it sits in the exact same type as everything else.

However, it is the only section of the document that explicitly describes what your policy will never do.

Reading it takes exactly about six minutes.

Consequently, understanding a professional indemnity exclusions list India is absolutely vital.

Therefore, it is the fastest way to understand what your cover is actually for.

Specifically, the exclusions define the exact shape of your protection more precisely than the benefits page ever does.

The Exclusions That Appear Almost Everywhere

These specific clauses recur consistently across Indian professional indemnity wordings for doctors. Treat this specific list as highly illustrative. Your own specific wording strictly governs your actual protection. Furthermore, the exact detail varies significantly between insurers and between specific filings. You can verify general policy regulations directly through the Insurance Regulatory and Development Authority of India (IRDAI).

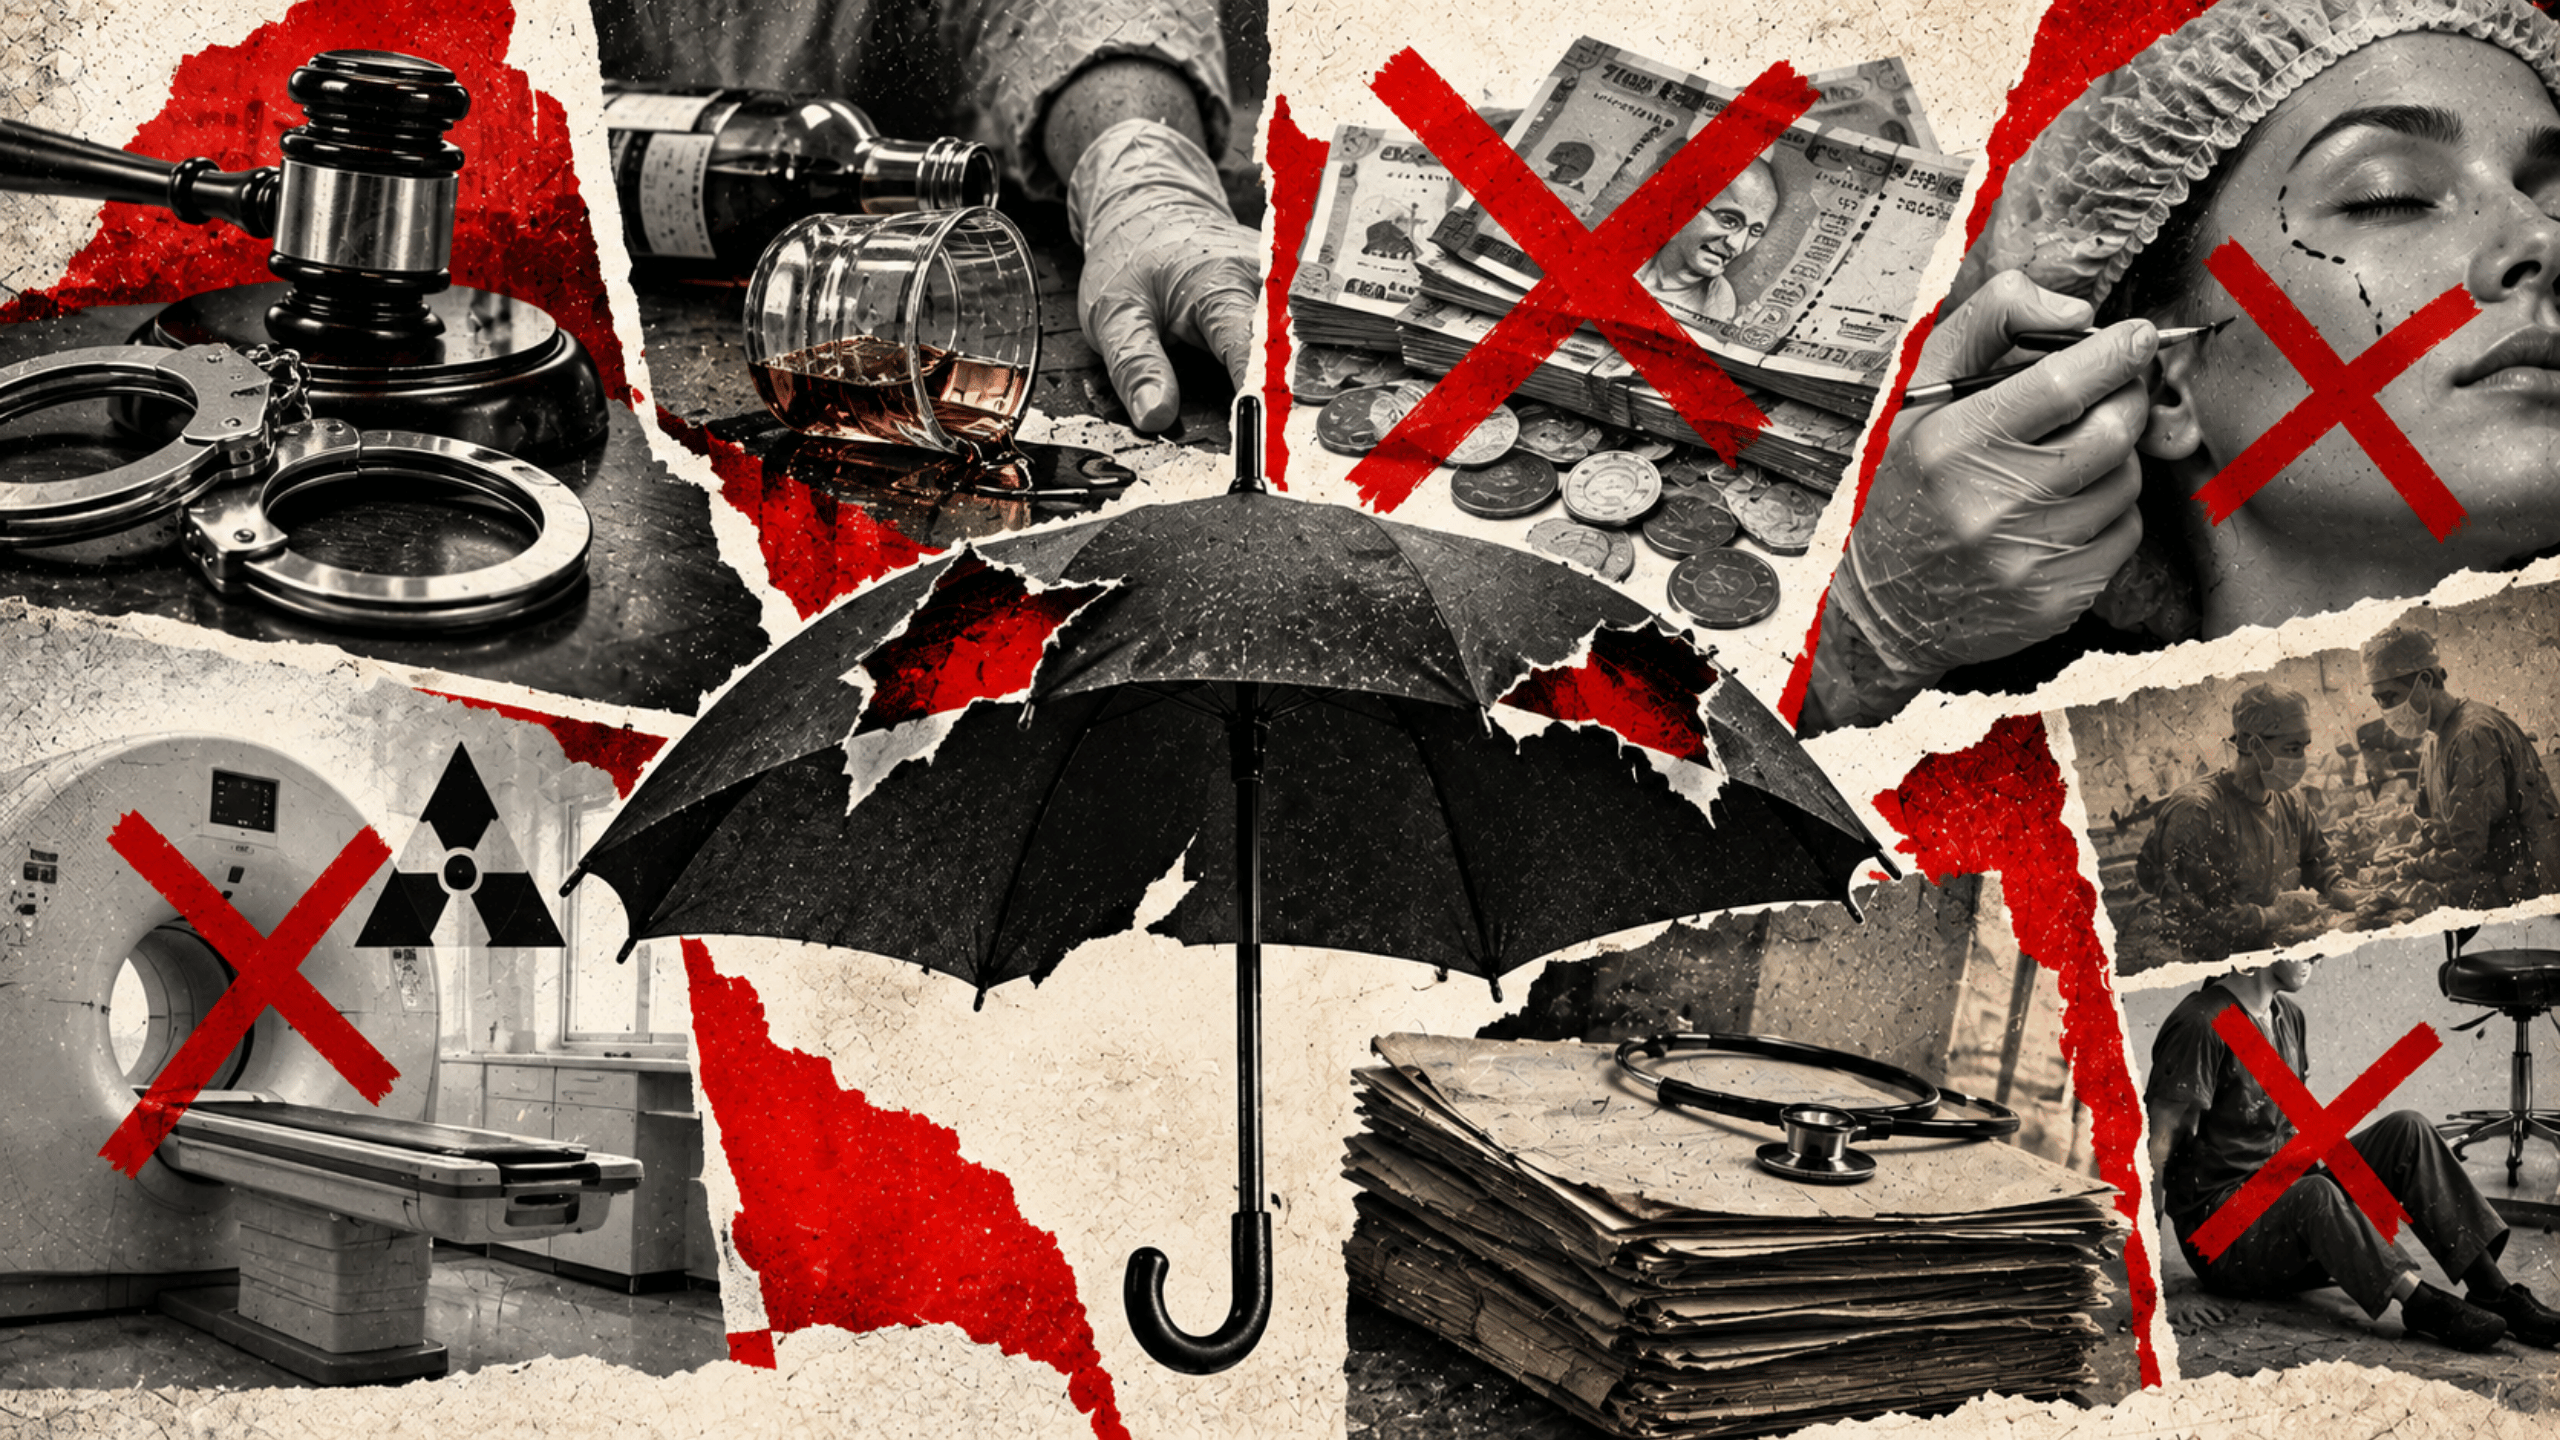
  • Acts before the retroactive date: Anything alleged to have been committed before the exact date printed on your active schedule.
  • Criminal acts and breaches of law: Clinical conduct in strict violation of any active law or ordinance.
  • Services under the influence: Medical treatment provided while actively under the influence of intoxicants or narcotics.
  • Contractual liability: Strict liability assumed under a contract that would not otherwise legally attach. Verify standard contractual obligations under the Indian Contract Act.
  • Fines and penalties: Specifically including punitive and exemplary financial damages.
  • Pure financial loss: Loss of clinical goodwill, loss of market share, and similar economic losses.
  • Defamation and related wrongs: Libel, slander, false arrest, wrongful detention, and similar legal heads.
  • Employer’s and public liability: Injuries arising strictly from contracts of employment, and general third party liability.
  • War and nuclear risks: War, invasion, civil war, and ionizing radiation or radioactive contamination.
  • Deliberate disregard: Knowingly failing to take active steps to prevent a patient claim.

The Clinical Exclusions Worth Checking Individually

Some specific exclusions are highly specific to medical practice. Consequently, these are the exact ones most likely to totally surprise a doctor. Many experienced doctors falsely assumed their whole scope of work was fully covered. Therefore, navigating the professional indemnity exclusions list India correctly avoids massive clinical risks.

Indian wordings commonly exclude cosmetic procedures such as hair transplants and flap rotations. However, they often include specific carve outs for reconstructive work after severe burns or trauma. Furthermore, they include strict carve outs for anaesthetic or vital support services. Treatment or prescription drugs strictly for weight reduction frequently appear as an exclusion. Wordings may also heavily restrict procedures performed under general anaesthesia outside a proper hospital setting. Ensure your clinical setup completely aligns with National Medical Commission (NMC) professional standards.

If any of that directly describes part of your active practice, do not rely on a general summary. Take the specific exclusion clause directly to your insurer. Specifically, ask clearly in writing whether the work you actually do falls inside or strictly outside it.

Why Exclusions Are Not A Trick

One more vital thing before you blindly go looking for your specific wording. Specifically, it completely changes exactly how you read it.

It is highly tempting to read this exact page as the insurer simply looking for a quick way out. Mostly, it is the exact opposite scenario. Conversely, it is the necessary financial boundary that makes the product priceable at all.

A policy that actively covered criminal conduct, regulatory fines, and losses you fully knew about before you bought it would absolutely not be genuine insurance. Each specific exclusion logically removes something that either is not a genuine risk, is somebody else’s risk, or logically belongs in a completely different policy. Specifically, this naturally includes employer’s liability, public liability, or clinic property cover.

Which naturally leads to the truly useful question. Therefore, ask not whether your indemnity policy safely covers absolutely everything. Conversely, ask whether the exact things it actively excludes are safely covered somewhere else, or knowingly carried by you personally.

How To Use This In Ten Minutes

Open your exact wording and quickly find the exclusions section. Mark absolutely anything that touches your actual clinical scope of work. Write directly to your insurer or broker with those highly specific clauses. Specifically, ask how each clause applies directly to your practice, and whether an active extension or a separate policy is readily available.

Keep the formal written reply securely with your policy documents. Any professional indemnity exclusions list India insurers openly publish will naturally be completely general. Conversely, a written answer about your own specific practice is highly specific. Furthermore, it is the absolute fastest way to confidently answer a hospital, a clinical partner, or your own memory two years from now.

The Takeaway

The policy benefits page exactly tells you what you actually bought. Conversely, the exclusions page explicitly tells you exactly what you still actively carry. Therefore, read the second one carefully before a massive claim makes you read it for the very first time. Ultimately, understanding your professional indemnity exclusions list India fully protects your medical career forever.

5 FAQ SECTION

What are the most common exclusions in Indian professional indemnity policies?

Acts before the retroactive date, criminal acts, services under the influence of intoxicants, contractual liability, fines and penalties, pure financial loss, defamation, employer’s and public liability, war and nuclear risks, and deliberate disregard of the need to prevent claims.

Are cosmetic procedures actively excluded?

Indian wordings commonly exclude certain cosmetic procedures, often with specific carve outs for reconstructive work after burns or trauma. Check your own specific wording and confirm the exact position for the procedures you perform.

Does my policy cover fines imposed by a regulator?

Fines, penalties and punitive damages are typically heavily excluded. Cover is generally directed entirely at civil liability to a patient, absolutely not at administrative penalties imposed directly on you.

Is an injury to my clinic staff safely covered?

Generally not under standard professional indemnity. Employment related injuries strictly fall under employer’s liability, and physical injuries to general visitors usually fall completely under public liability.

Do exclusions differ significantly between insurers?

Yes. Wordings vary significantly between specific insurers and between individual product filings. Furthermore, exclusions are strictly amended over time. Always carefully read the exact wording issued with your own active policy.
Tags: claims made policy exclusionsdoctor insurance termsdoctor liability insurancehealthcare risk managementindemnity policy conditionsinsurance claim rejectionmedical indemnity exclusionsmedical malpractice cover Indiamedical practitioner coverpolicy exclusions doctorspolicy wording doctorsprofessional indemnity exclusions list Indiaprofessional indemnity insurance Indiaprofessional liability Indiaretroactive date exclusion
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

You Retire. The Claims Window Does Not

Next Post

Five Moments You Assume You Are Covered

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Five Moments You Assume You Are Covered
Blog

Five Moments You Assume You Are Covered

September 17, 2026
Run-Off Cover: After You Stop Practising
Blog

You Retire. The Claims Window Does Not

September 17, 2026
AOA and AOY: What the Ratio Means
Blog

AOA, AOY and the Ratio You Pick

September 17, 2026
Retroactive Date: The Line That Decides
Blog

The Most Important Date on Your Policy

September 17, 2026
Claims-Made vs Occurrence: When Does Your Cover Respond?
Blog

Claims-Made vs Occurrence, Explained

September 17, 2026
Red, black and white editorial image showing consecutive insurance calendar periods progressing into continuous medical professional protection.
Blog

Multi-Year or Annual Renewal?

September 17, 2026
Next Post
Five Moments You Assume You Are Covered

Five Moments You Assume You Are Covered

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Five Moments You Assume You Are Covered
  • The Exclusions Page, in Plain Language
  • You Retire. The Claims Window Does Not
  • AOA, AOY and the Ratio You Pick
  • The Most Important Date on Your Policy

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In