You forgot your renewal once.
It happened exactly three years ago.
You caught the dangerous lapse four days late.
Consequently, that highly stressful memory simply refuses to leave you.
Therefore, locking your cover in for three years sounds incredibly appealing.
Specifically, it feels like the perfect permanent solution to your own worst habit.
However, before you start searching blindly, you must understand the rules first.
Evaluating the multi-year indemnity policy vs annual renewal debate requires absolute clarity.
There is exactly what the Indian regulator legally permits.
Conversely, there is what insurance companies actually offer on the shelf today.
What The Regulator Allows For Long Term Insurance Policies
The insurance regulator issued a highly important master circular recently. Specifically, this June 2024 circular strictly governs general insurance business. It clearly provides that general insurance policies may be issued differently. Therefore, policies can legally run on an annual, long term, or short term basis. Consequently, long term policy tenure is officially permitted in principle across India. You can review official regulatory updates directly on the Insurance Regulatory and Development Authority of India (IRDAI) portal.
However, being legally permitted is not the exact same as being readily available. Whether any Indian insurer currently files and sells a multi year product remains highly uncertain. Therefore, you must ask your specific insurer directly. Do not blindly assume the answer either way.
Why Annual Professional Indemnity Renewal Remains The Norm
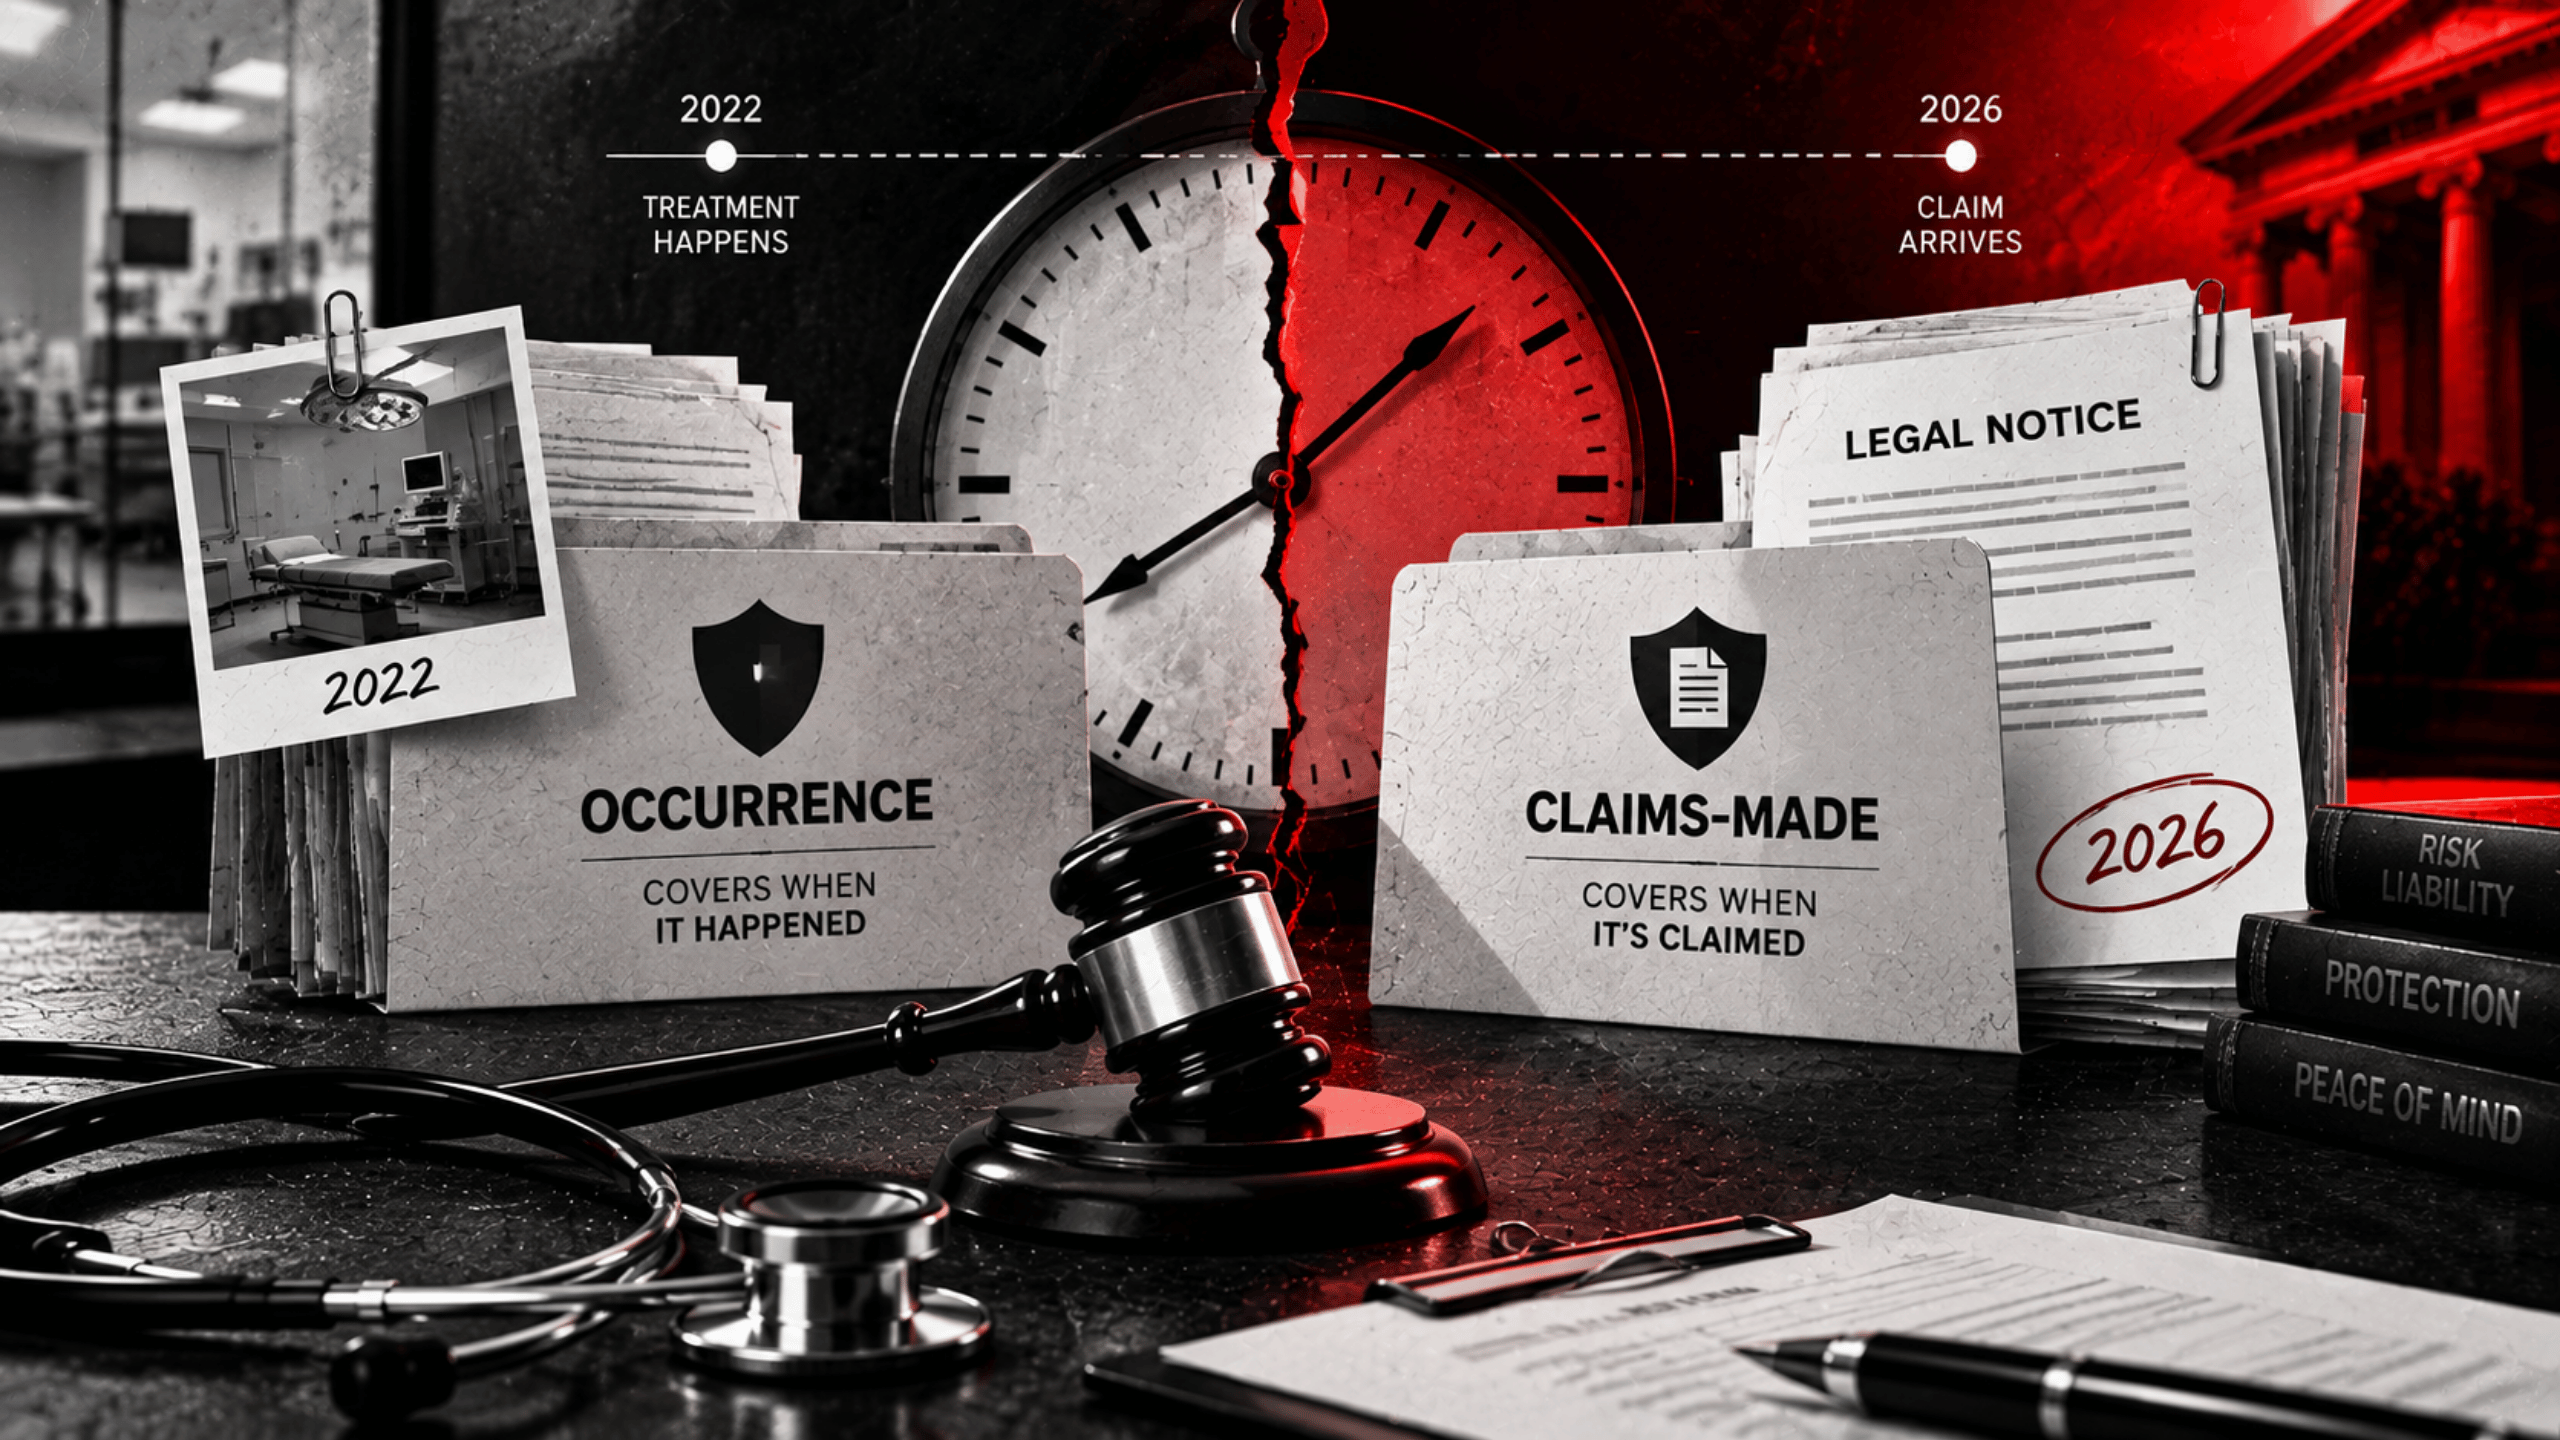
Ask any experienced broker about doctor insurance policies in India. Almost every single medical practitioner currently holds a standard one year policy. Furthermore, the real reason for this is absolutely not market inertia. Conversely, the financial product is deliberately built around an annual rhythm. Specifically, these structural reasons actively work directly in your professional favor. Professional indemnity is strictly written on a claims made basis. Consequently, this unique legal structure actively pushes the entire product towards annual cycles. You can track shifting medical practice guidelines comprehensively on the National Medical Commission (NMC) website.
- Risk changes yearly: A new clinical procedure or hospital alters your exposure.
- Disclosure is annual: Patient claims and legal notices are declared at each renewal.
- Limits get revisited: The exact sum insured you needed previously may not suit you now. Review your medical liability insurance limits regularly.
- Policy wordings evolve: Insurance terms and legal definitions change constantly between filings.
None of that makes a longer tenure strictly wrong. However, it clearly explains exactly why the market settled here permanently.
What Continuous Insurance Coverage Options Compete On
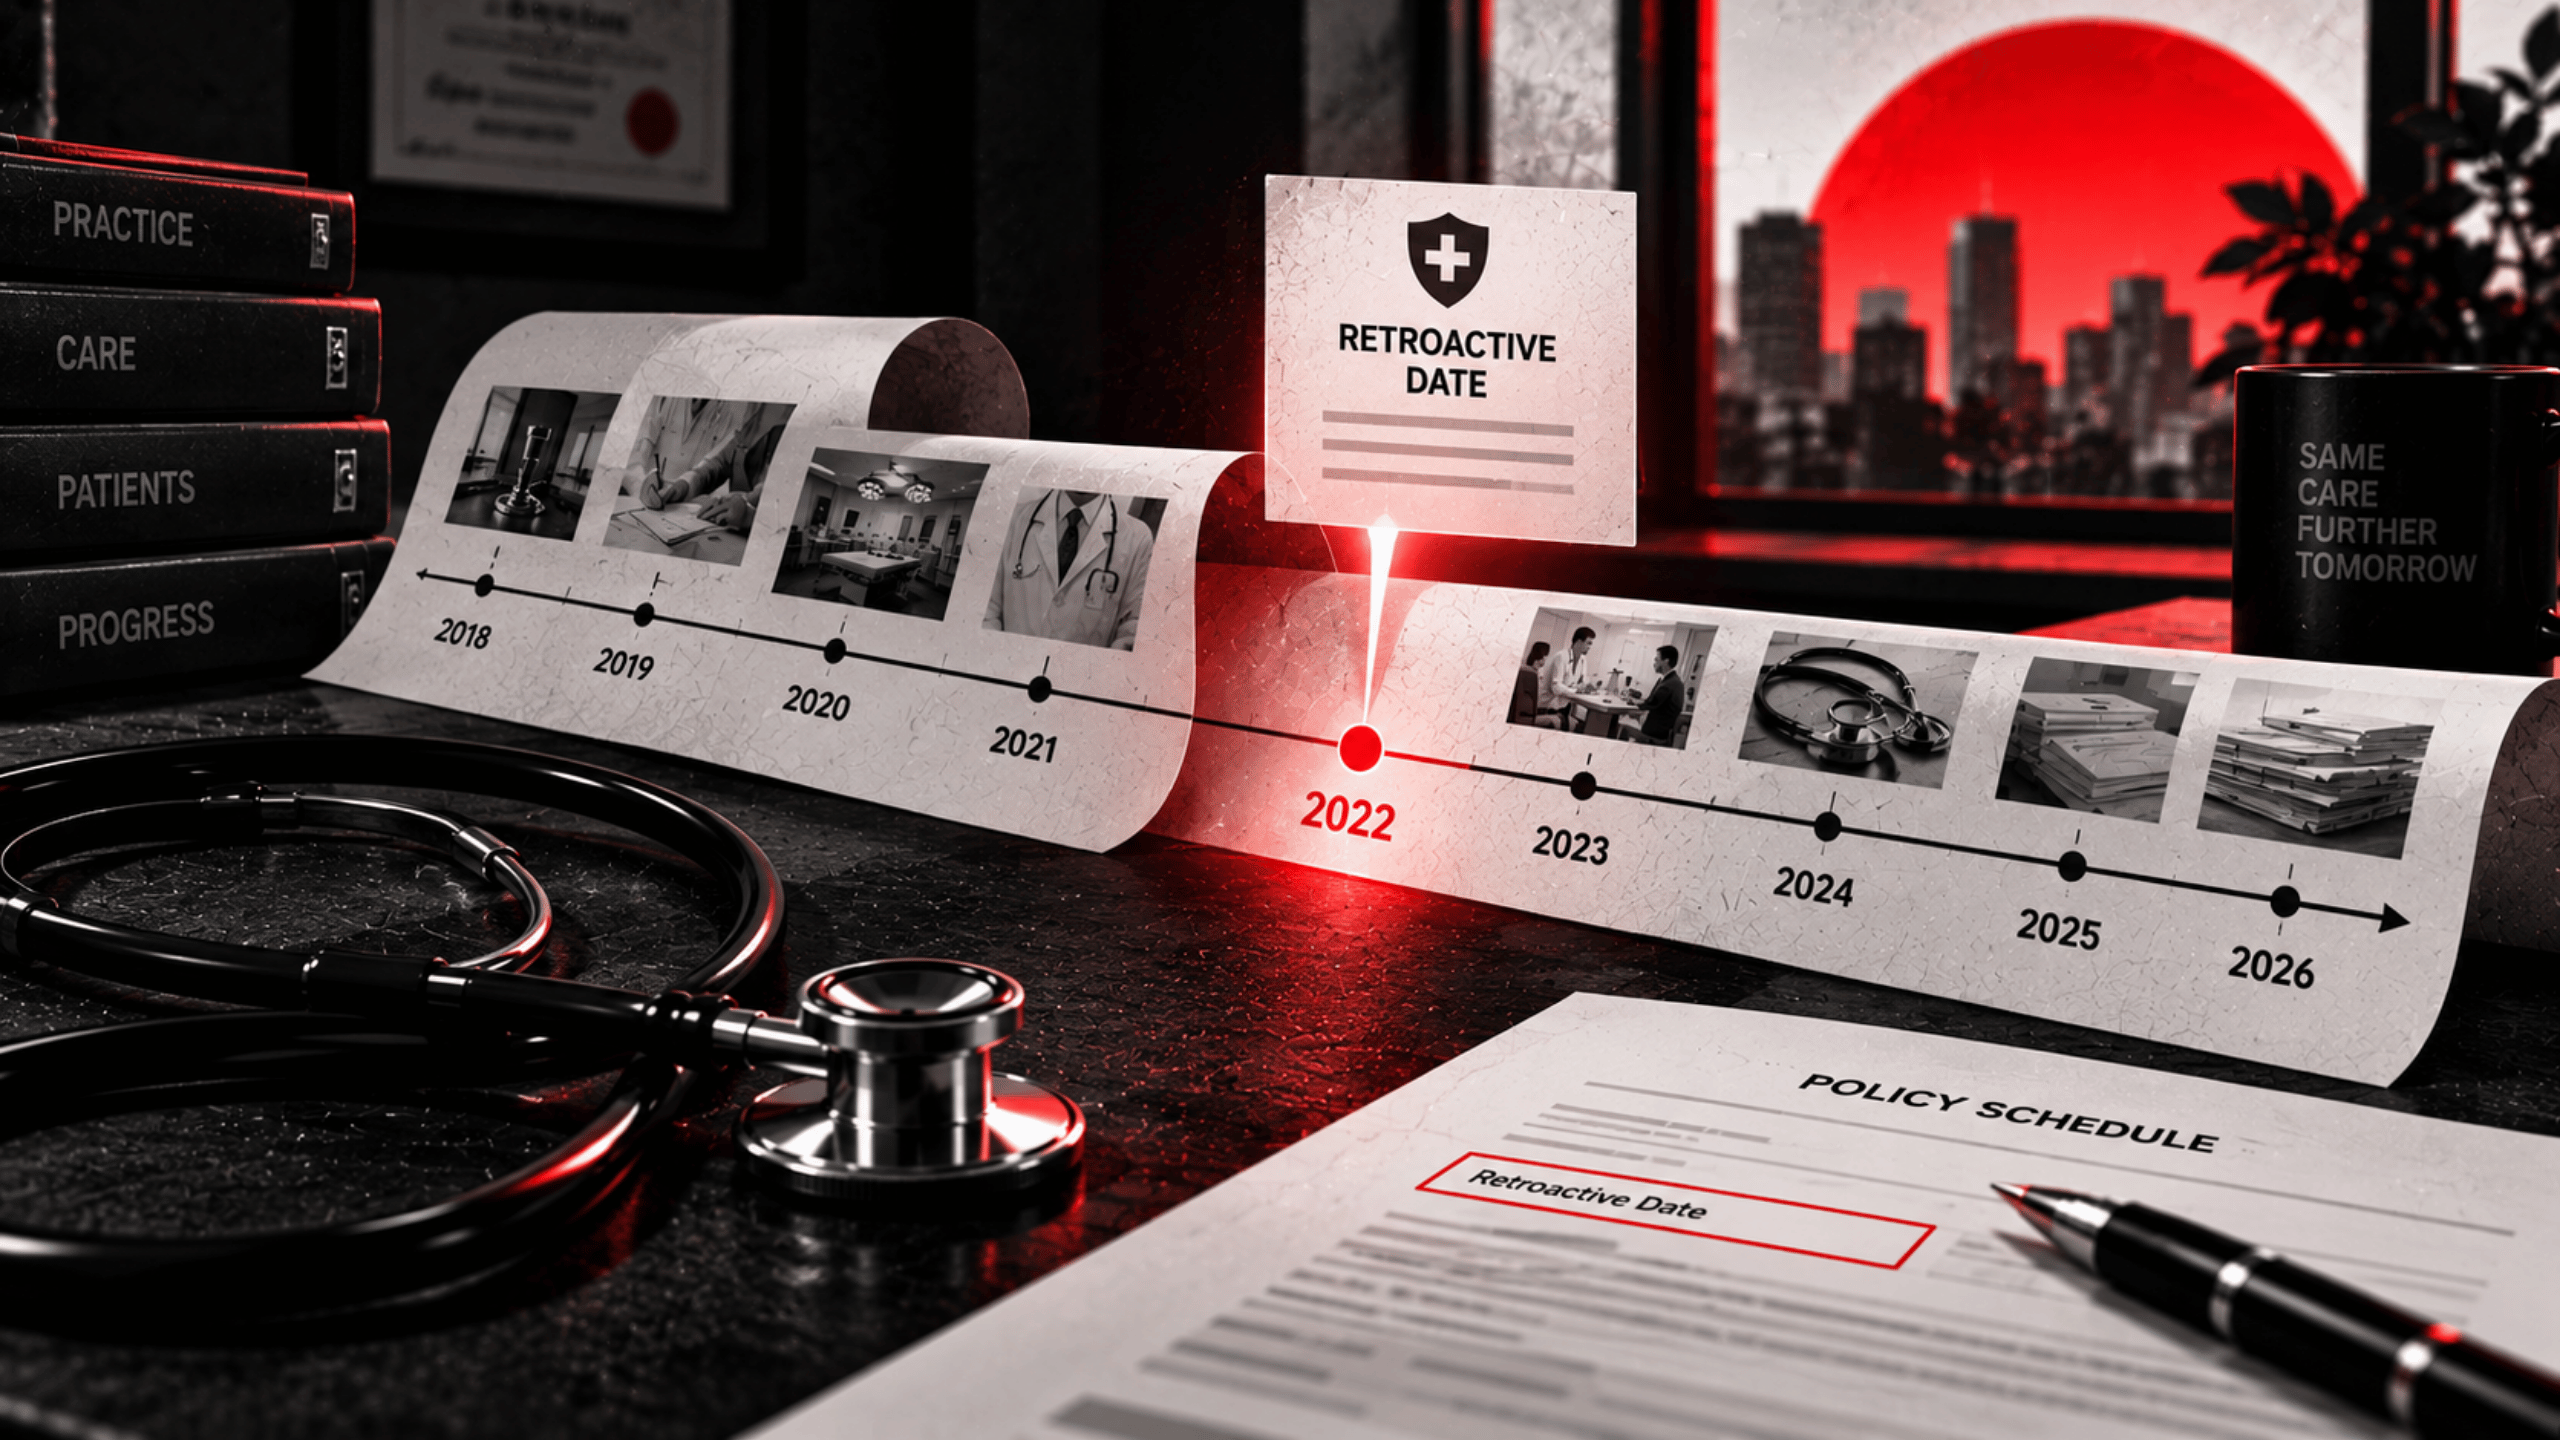
Here is the exact point most of this debate misses completely. The benefit people genuinely want is absolutely not the long tenure itself. Conversely, doctors desperately want continuous insurance coverage forever. Specifically, they want to completely avoid any dangerous coverage gaps. Furthermore, they want absolute retroactive date preservation. Continuity is completely achievable on a standard annual policy. It simply requires a highly reliable calendar reminder. Therefore, it requires a fully working bank payment mandate. Renew precisely on time every single year. Consequently, your retroactive date holds exactly as it would under a longer contract.
Which completely reframes the multi-year indemnity policy vs annual renewal choice into something far more useful. Specifically, it is absolutely not about which tenure is inherently better. Conversely, it is simply about what actually stops you from missing a critical date. You can carefully review statutory contract rules under the Indian Contract Act to understand policy continuity.
Critical Questions Before Signing A Long Term Policy Tenure
If a longer tenure is formally offered to you, proceed very carefully. Therefore, ask these specific questions before signing anything. Furthermore, you must get these exact answers firmly in writing.
- What happens to the retroactive date: It must firmly carry your original date forward.
- How disclosure works mid term: Confirm exactly how you report a sudden practice change.
- Whether coverage limits can be revised: Clarify if upgrading requires a brand new policy. Ensure your doctor insurance renewal process is clear.
- How premium is paid: Confirm the exact payment structure before assuming instalments exist.
- How cancellation works: Refunds strictly apply to completely uncommenced policy years.
What Actually Protects Your Retroactive Date Preservation
Whichever tenure you ultimately choose, the protective behavior remains absolutely identical. Set two strict calendar reminders right now. Specifically, set them forty five and fifteen days before expiry. Set them strictly in your own personal calendar immediately. Therefore, stop relying on the insurance company to chase you. Verify your bank payment mandate actually works perfectly. Failed mandates cause significantly more policy lapses than simple forgetfulness does. Furthermore, read your policy schedule the exact moment it arrives. Check the retroactive date, the specialty, and the exact financial limits. Disclose anything that changed during the year clearly in writing.
A longer policy is simply a modern convenience. Conversely, continuous proactive protection is your ultimate financial shield. Therefore, set your renewal reminders right away. This is the one step no insurance product can ever do for you. Understanding the multi-year indemnity policy vs annual renewal differences keeps your medical practice completely safe. Ultimately, mastering the multi-year indemnity policy vs annual renewal decision secures your long term professional peace of mind.
5 FAQ SECTION
Does IRDAI permit multi year general insurance policies?
Yes. The June 2024 master circular provides that policies may be issued on an annual, long term, or short term basis. However, actual product availability strictly depends on the individual insurer.
Can I buy a three year professional indemnity policy as a doctor?
You must ask your specific insurer. Long term tenure is permitted in principle. Conversely, the actual availability of a multi year doctors indemnity product varies significantly today.
Would a multi year policy protect my retroactive date better?
Not inherently. What strictly preserves your retroactive date is completely unbroken cover. Therefore, an annual policy renewed exactly on time achieves the exact same legal outcome.
Can I pay a long term premium in monthly instalments?
Do not blindly assume so. Instalment premium arrangements differ vastly by product and specific insurer. Therefore, confirm the exact payment structure clearly in writing before fully committing.
What happens if I cancel a policy longer than one year?
Under the current circulars, refund rules differ based on tenure. Specifically, for terms over one year, refunds apply strictly to policy years where risk cover has not yet commenced