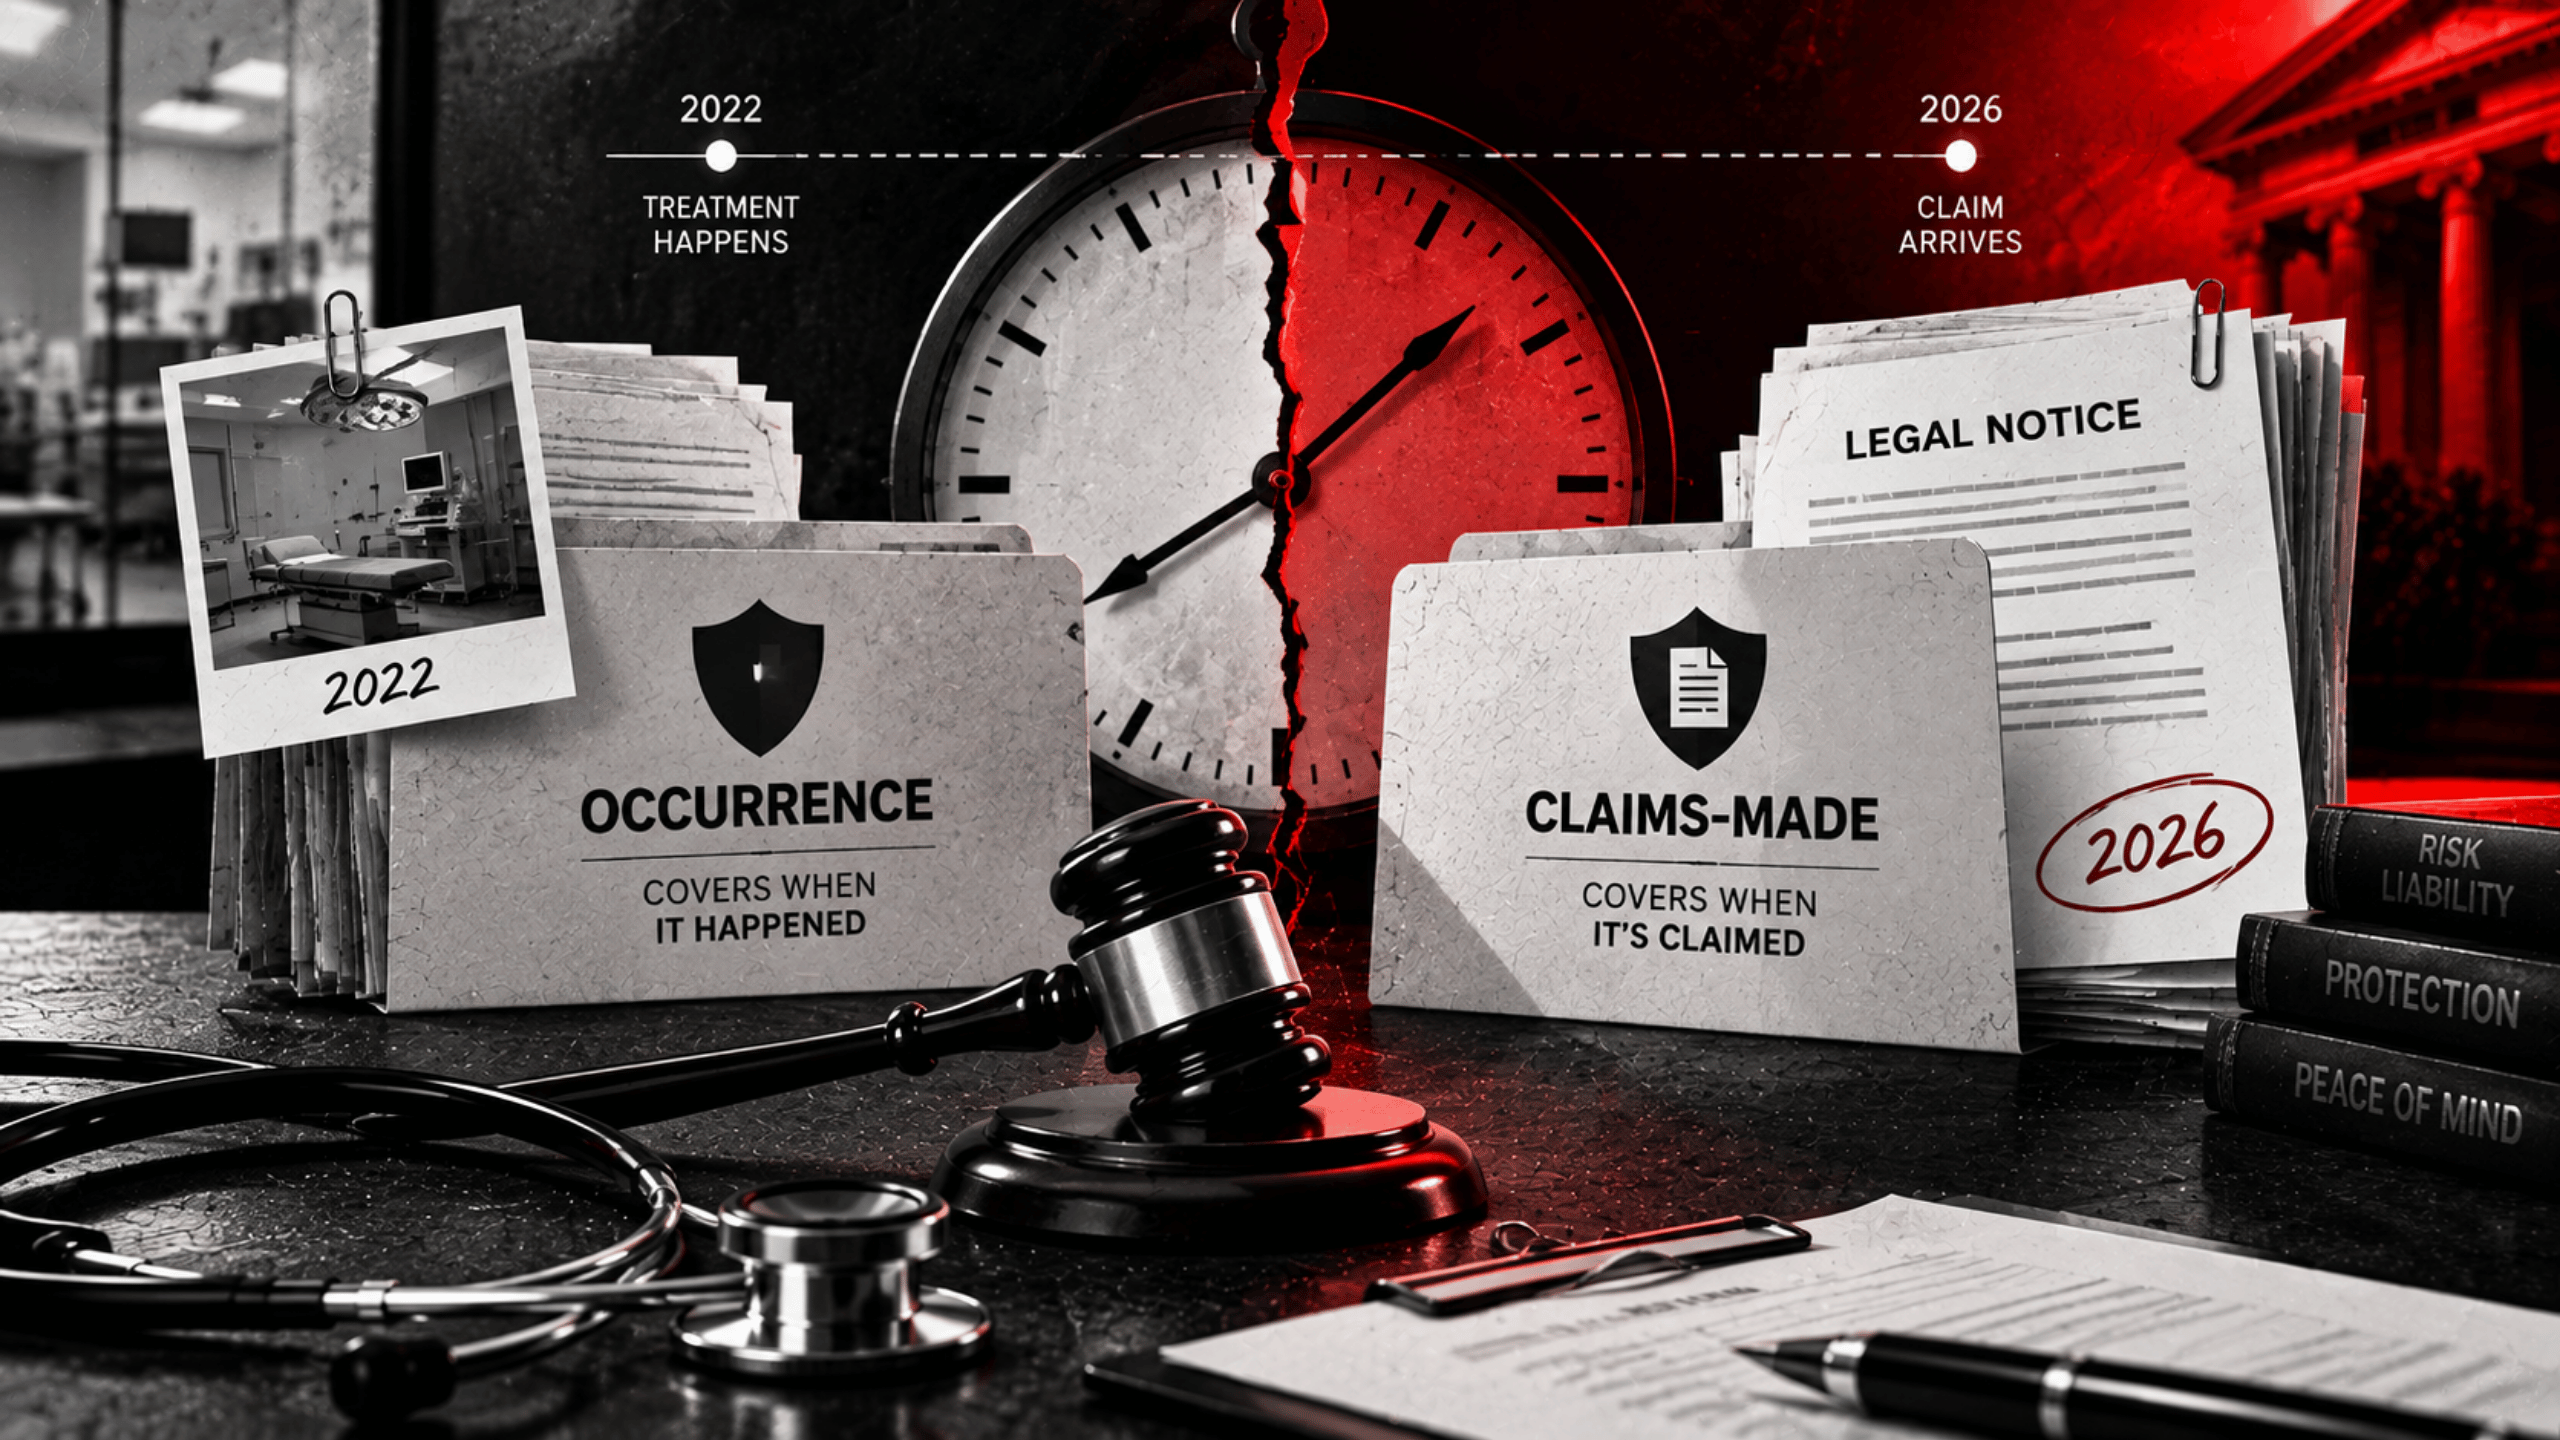
The notice arrives on a Tuesday.
By Friday you have an advocate, a retainer and an invoice carrying a number you had not budgeted for.
You are insured, so the money is handled. That is what the policy is for.
Partly. Does indemnity cover legal defence costs? Yes, it does. What almost nobody explains at the point of sale is where that money comes from.
Yes — And It Comes Out Of Your Sum Insured
Every Indian doctors’ indemnity wording I have read says the same thing in slightly different words: amounts spent on defending, settling or paying a claim reduce the limit of indemnity. Defence costs sit inside the cover, not on top of it.
So a fifty lakh policy is not fifty lakh of compensation plus whatever the lawyers cost. It is fifty lakh in total, and the lawyers are paid from it first. Nothing about that is hidden — it is printed in the conditions — but very few doctors are told it at the point of sale.
Take an illustrative case. A matter runs four years and the defence costs eight lakh. Whatever is left for an award or settlement is forty-two lakh, not fifty. Those are illustrative numbers, not a quotation — but the direction is the point. A long defence quietly shrinks the cover available for the outcome.
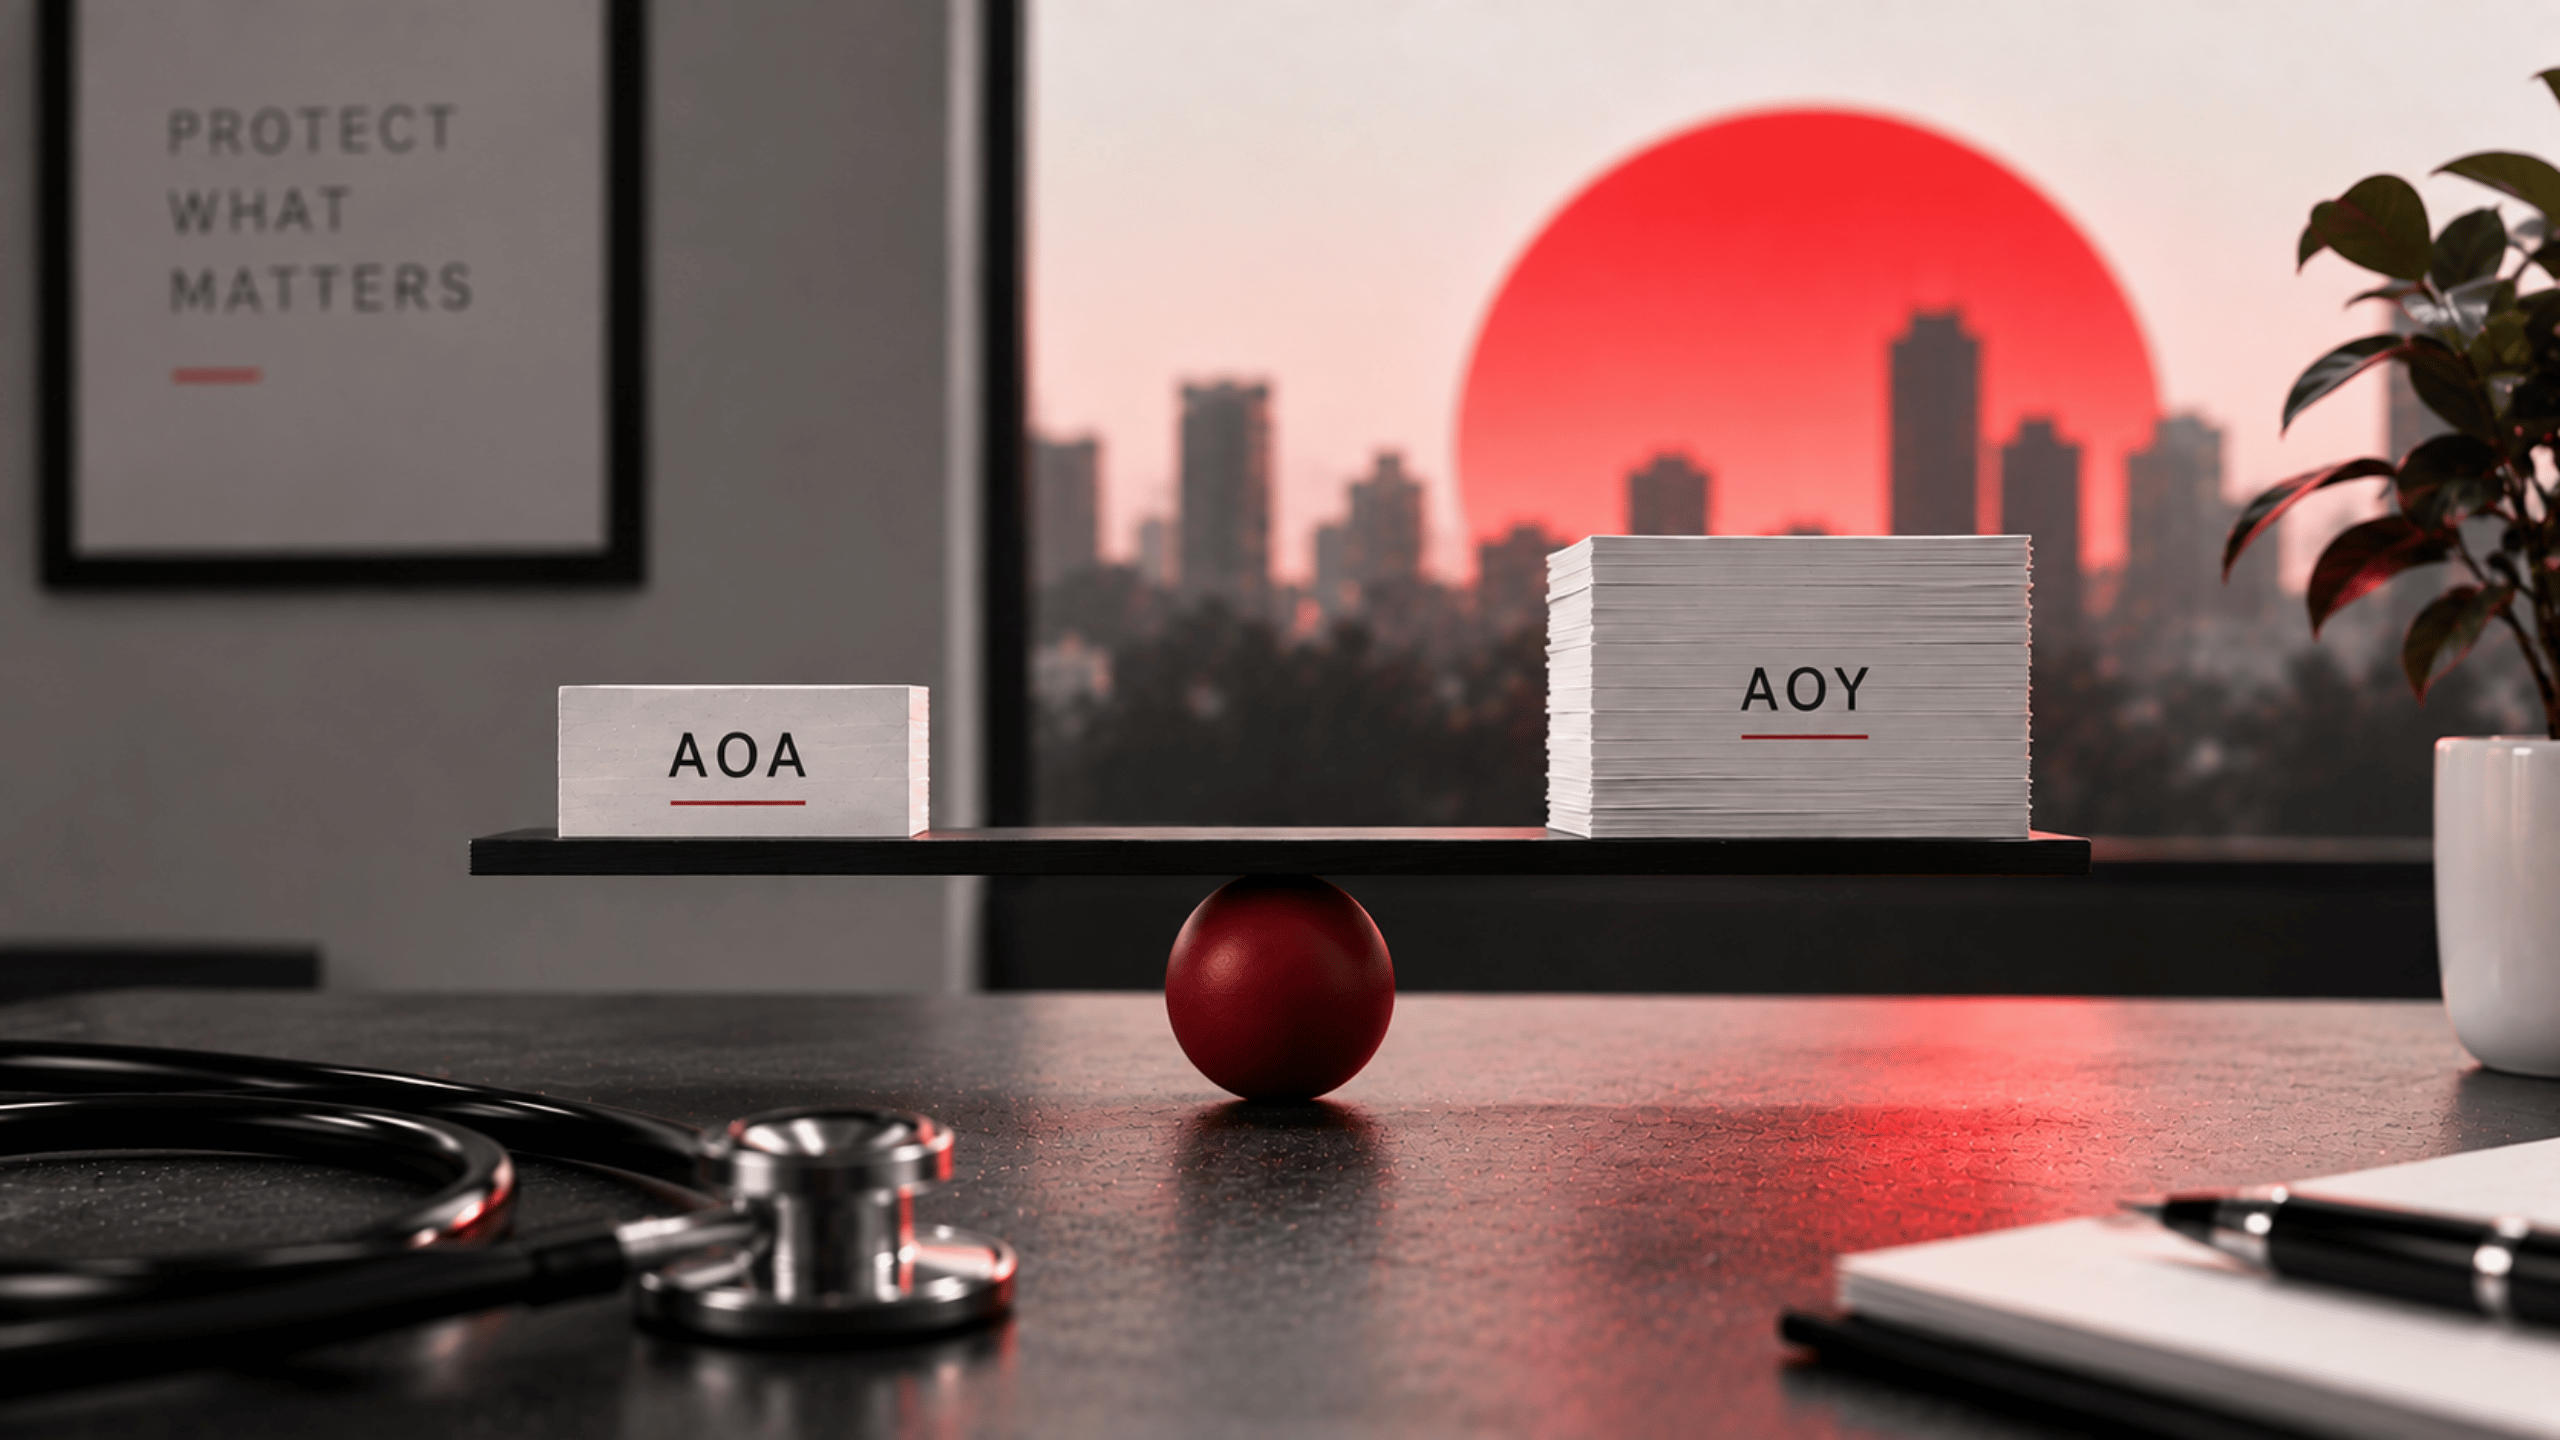
This is also why the AOA and AOY limits on your schedule matter more than the headline sum insured suggests.
The practical consequence is that the answer to does indemnity cover legal defence costs is really two answers. It covers them, and it covers them out of the money you were relying on for the outcome.
And They Usually Count Toward Your Excess
There is a second erosion most doctors miss. Several wordings apply the compulsory excess or deductible to defence costs as well as to damages, so the first slice of your legal bill is yours before the policy engages at all.
Check the schedule for the excess figure and check the wording for what it attaches to. The two are not always in the same paragraph, and the difference is real money in a long matter.
Does Indemnity Cover Legal Defence Costs You Incurred Alone?
This is where a valid policy stops helping people.
Indian wordings require the insurer’s prior written consent before you admit liability, make an offer, agree a settlement, or in some wordings before you incur defence costs at all. In at least one Indian product that consent is drafted as a condition precedent to cover.
Read plainly: fees you run up before telling your insurer may not be recoverable, however reasonable they were. Some of the newer wordings add that consent will not be unreasonably withheld. Several of the doctors’ wordings do not say that at all.
So the honest answer is conditional. The cover is there; reaching it requires a phone call before the retainer, not after.
Four Lines To Find In Your Own Wording
None of this requires reading the whole document. Four provisions decide almost everything about how a defence is funded.
- Within or in addition: Does the wording say defence costs reduce the limit of indemnity? Almost certainly yes — confirm it.
- What triggers consent: Admission, settlement, or incurring costs. The third is the strictest version.
- What the excess attaches to: Damages only, or damages and defence costs.
- Right or duty to defend: Most wordings give the insurer a right, not an obligation. That distinction decides who runs your defence.
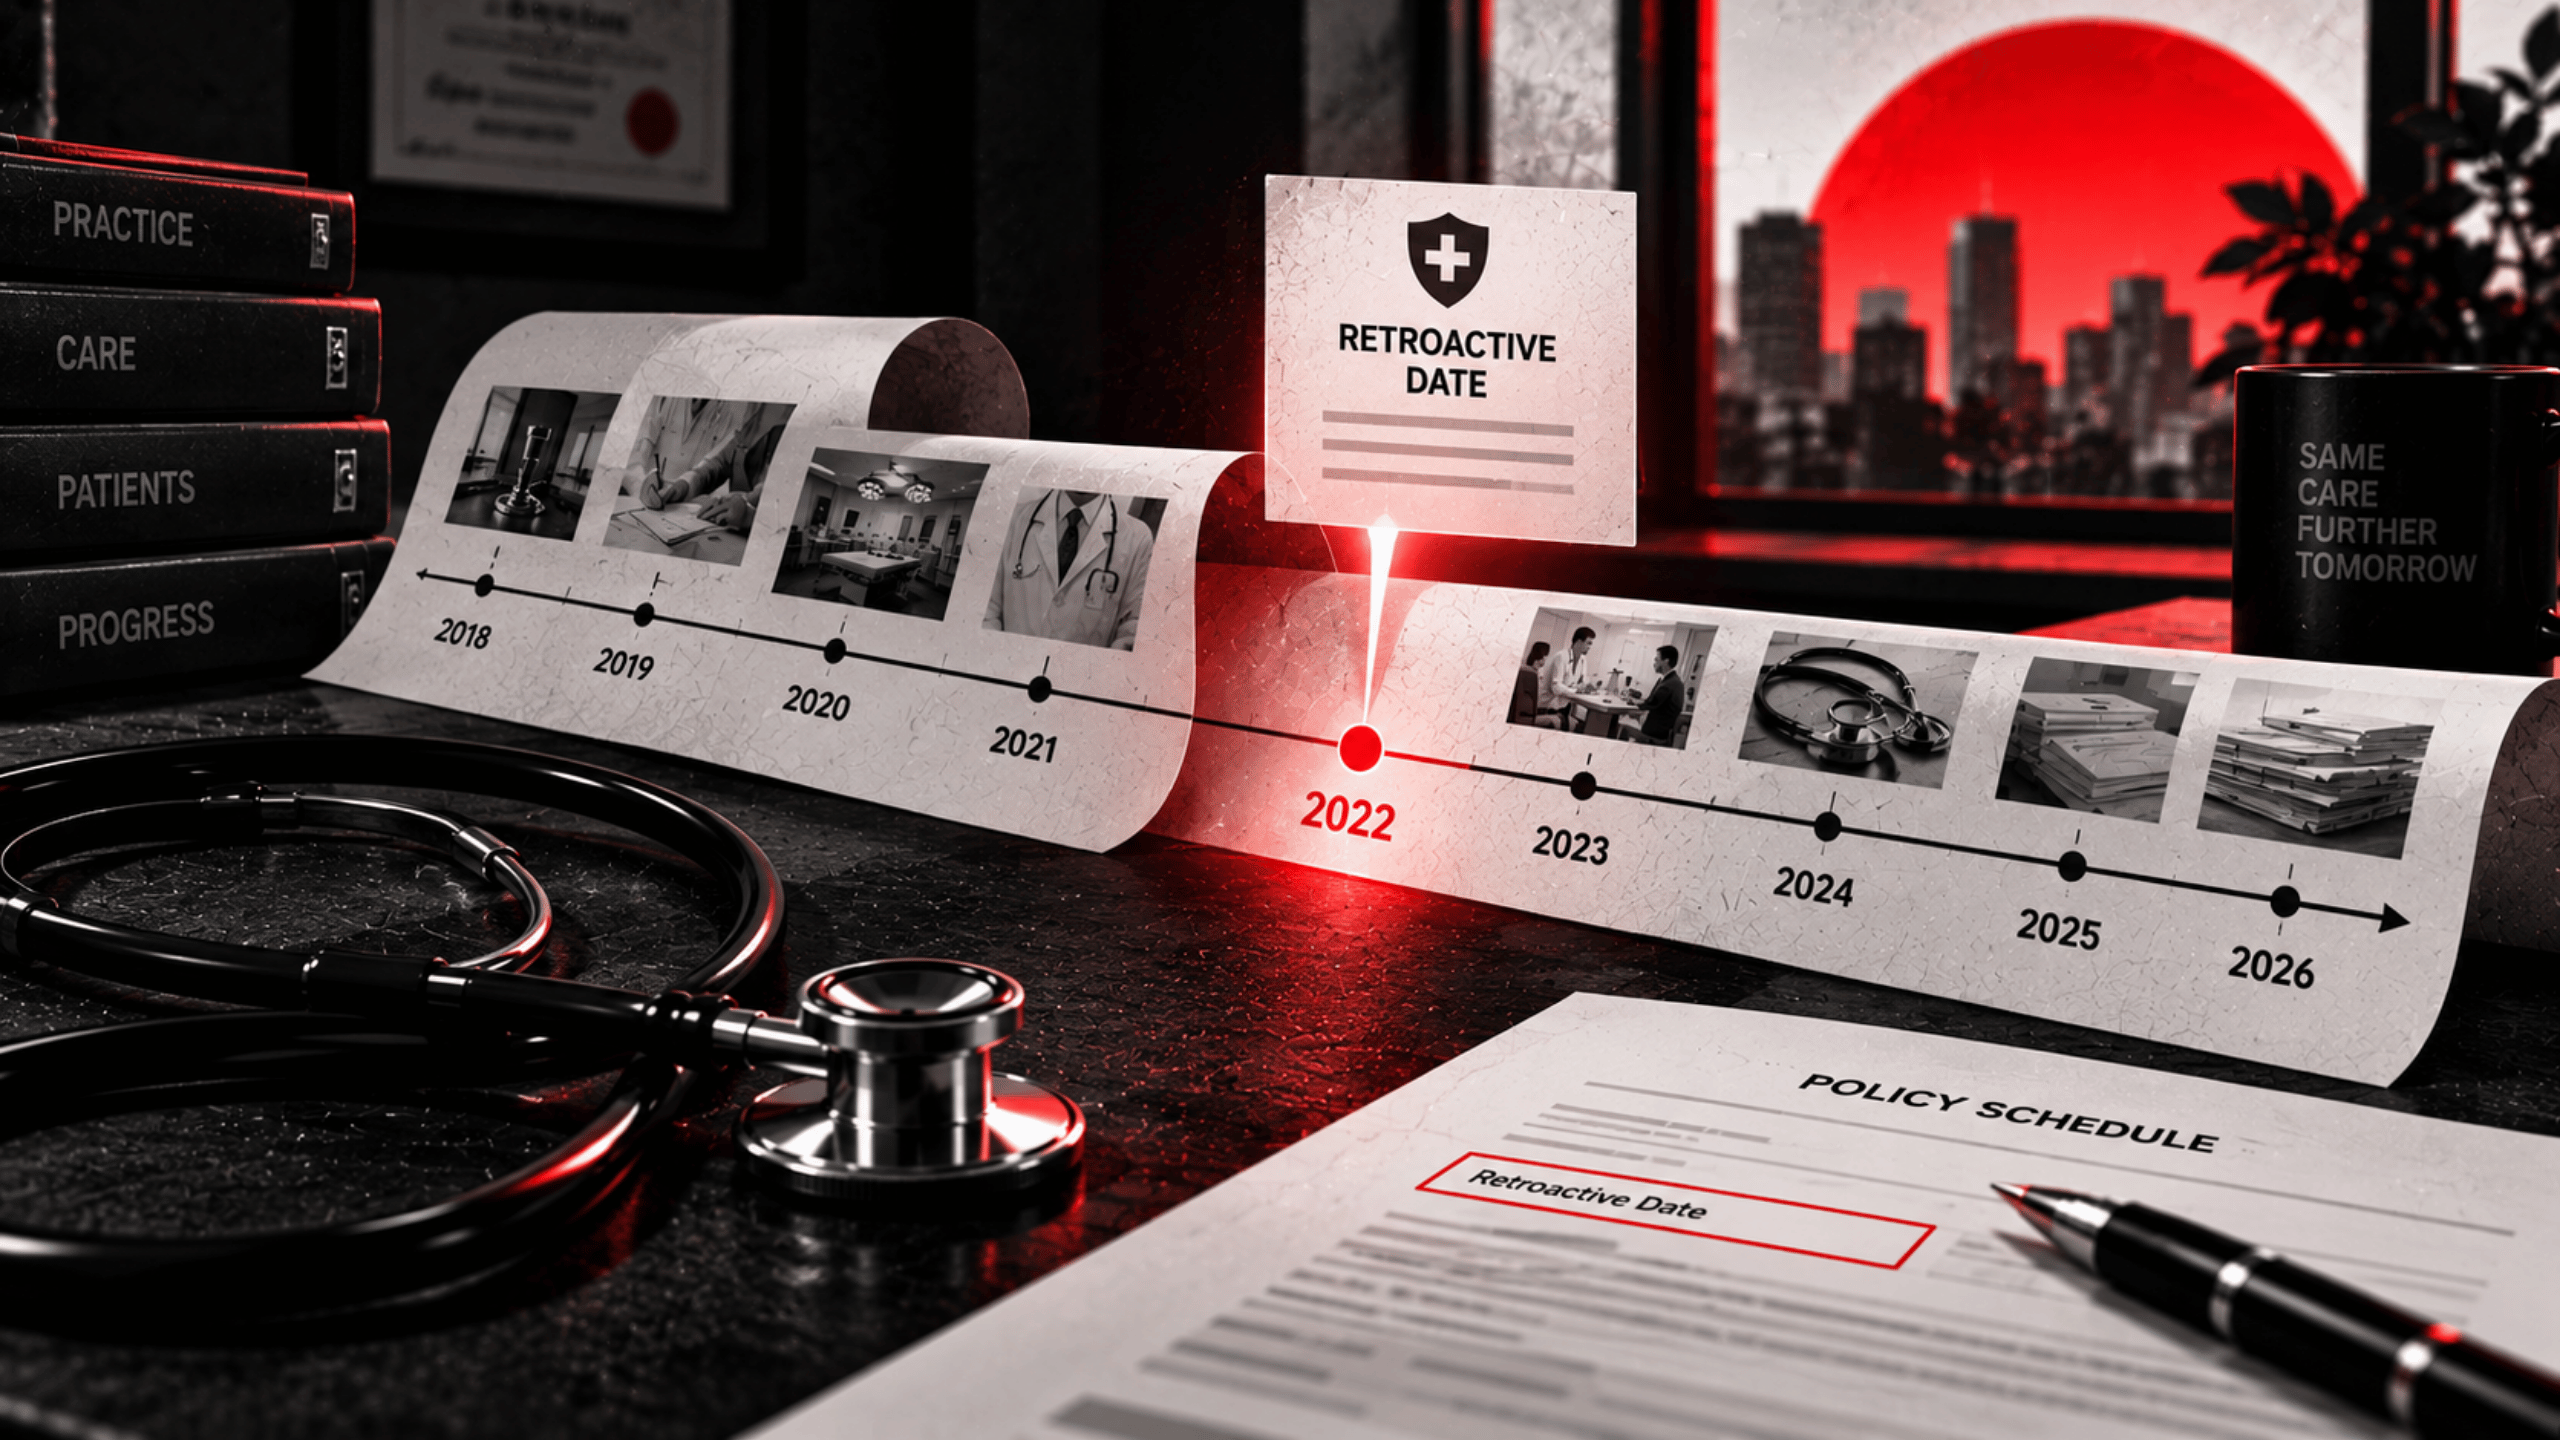
If you cannot find these in ten minutes, email your insurer and ask for them in writing. That reply belongs in the same folder as your policy schedule and registration documents, and it is worth having before a notice arrives rather than after.
The Takeaway
Does indemnity cover legal defence costs? Yes — from inside your limit, after your excess, and only with consent.
Which means the limit you choose is buying two things at once. Size it for the defence as well as the award.
6 FAQs
Are defence costs paid on top of the sum insured?
In the Indian doctors’ wordings examined, no. Amounts spent defending or settling a claim reduce the limit of indemnity. Check your own wording, as terms differ between insurers.
Does my excess apply to legal costs too?
In several wordings it does. Confirm what the compulsory excess attaches to in your policy, because it is not always limited to damages.
Can I appoint an advocate and claim the fees later?
Only with the insurer’s prior written consent. Some wordings make that consent a condition precedent, so costs incurred before notifying the insurer may not be recoverable.
Will my insurer definitely run my defence?
Not necessarily. Most Indian wordings give the insurer a right, but not an obligation, to take over the defence. One product examined imposes a duty. Ask which yours is.
Does a long case reduce what is left for a settlement?
Yes, where defence costs erode the limit. A matter running several years can consume a meaningful share of the sum insured before any award is decided.
Where can I check the rules that apply to insurers?
The Insurance Regulatory and Development Authority of India publishes the applicable regulations and circulars at irdai.gov.in.