help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

One Old Complaint. Declare It Or Not?

coveryouadmin by coveryouadmin
September 16, 2026
in Blog
Reading Time: 4 mins read
0 0
0
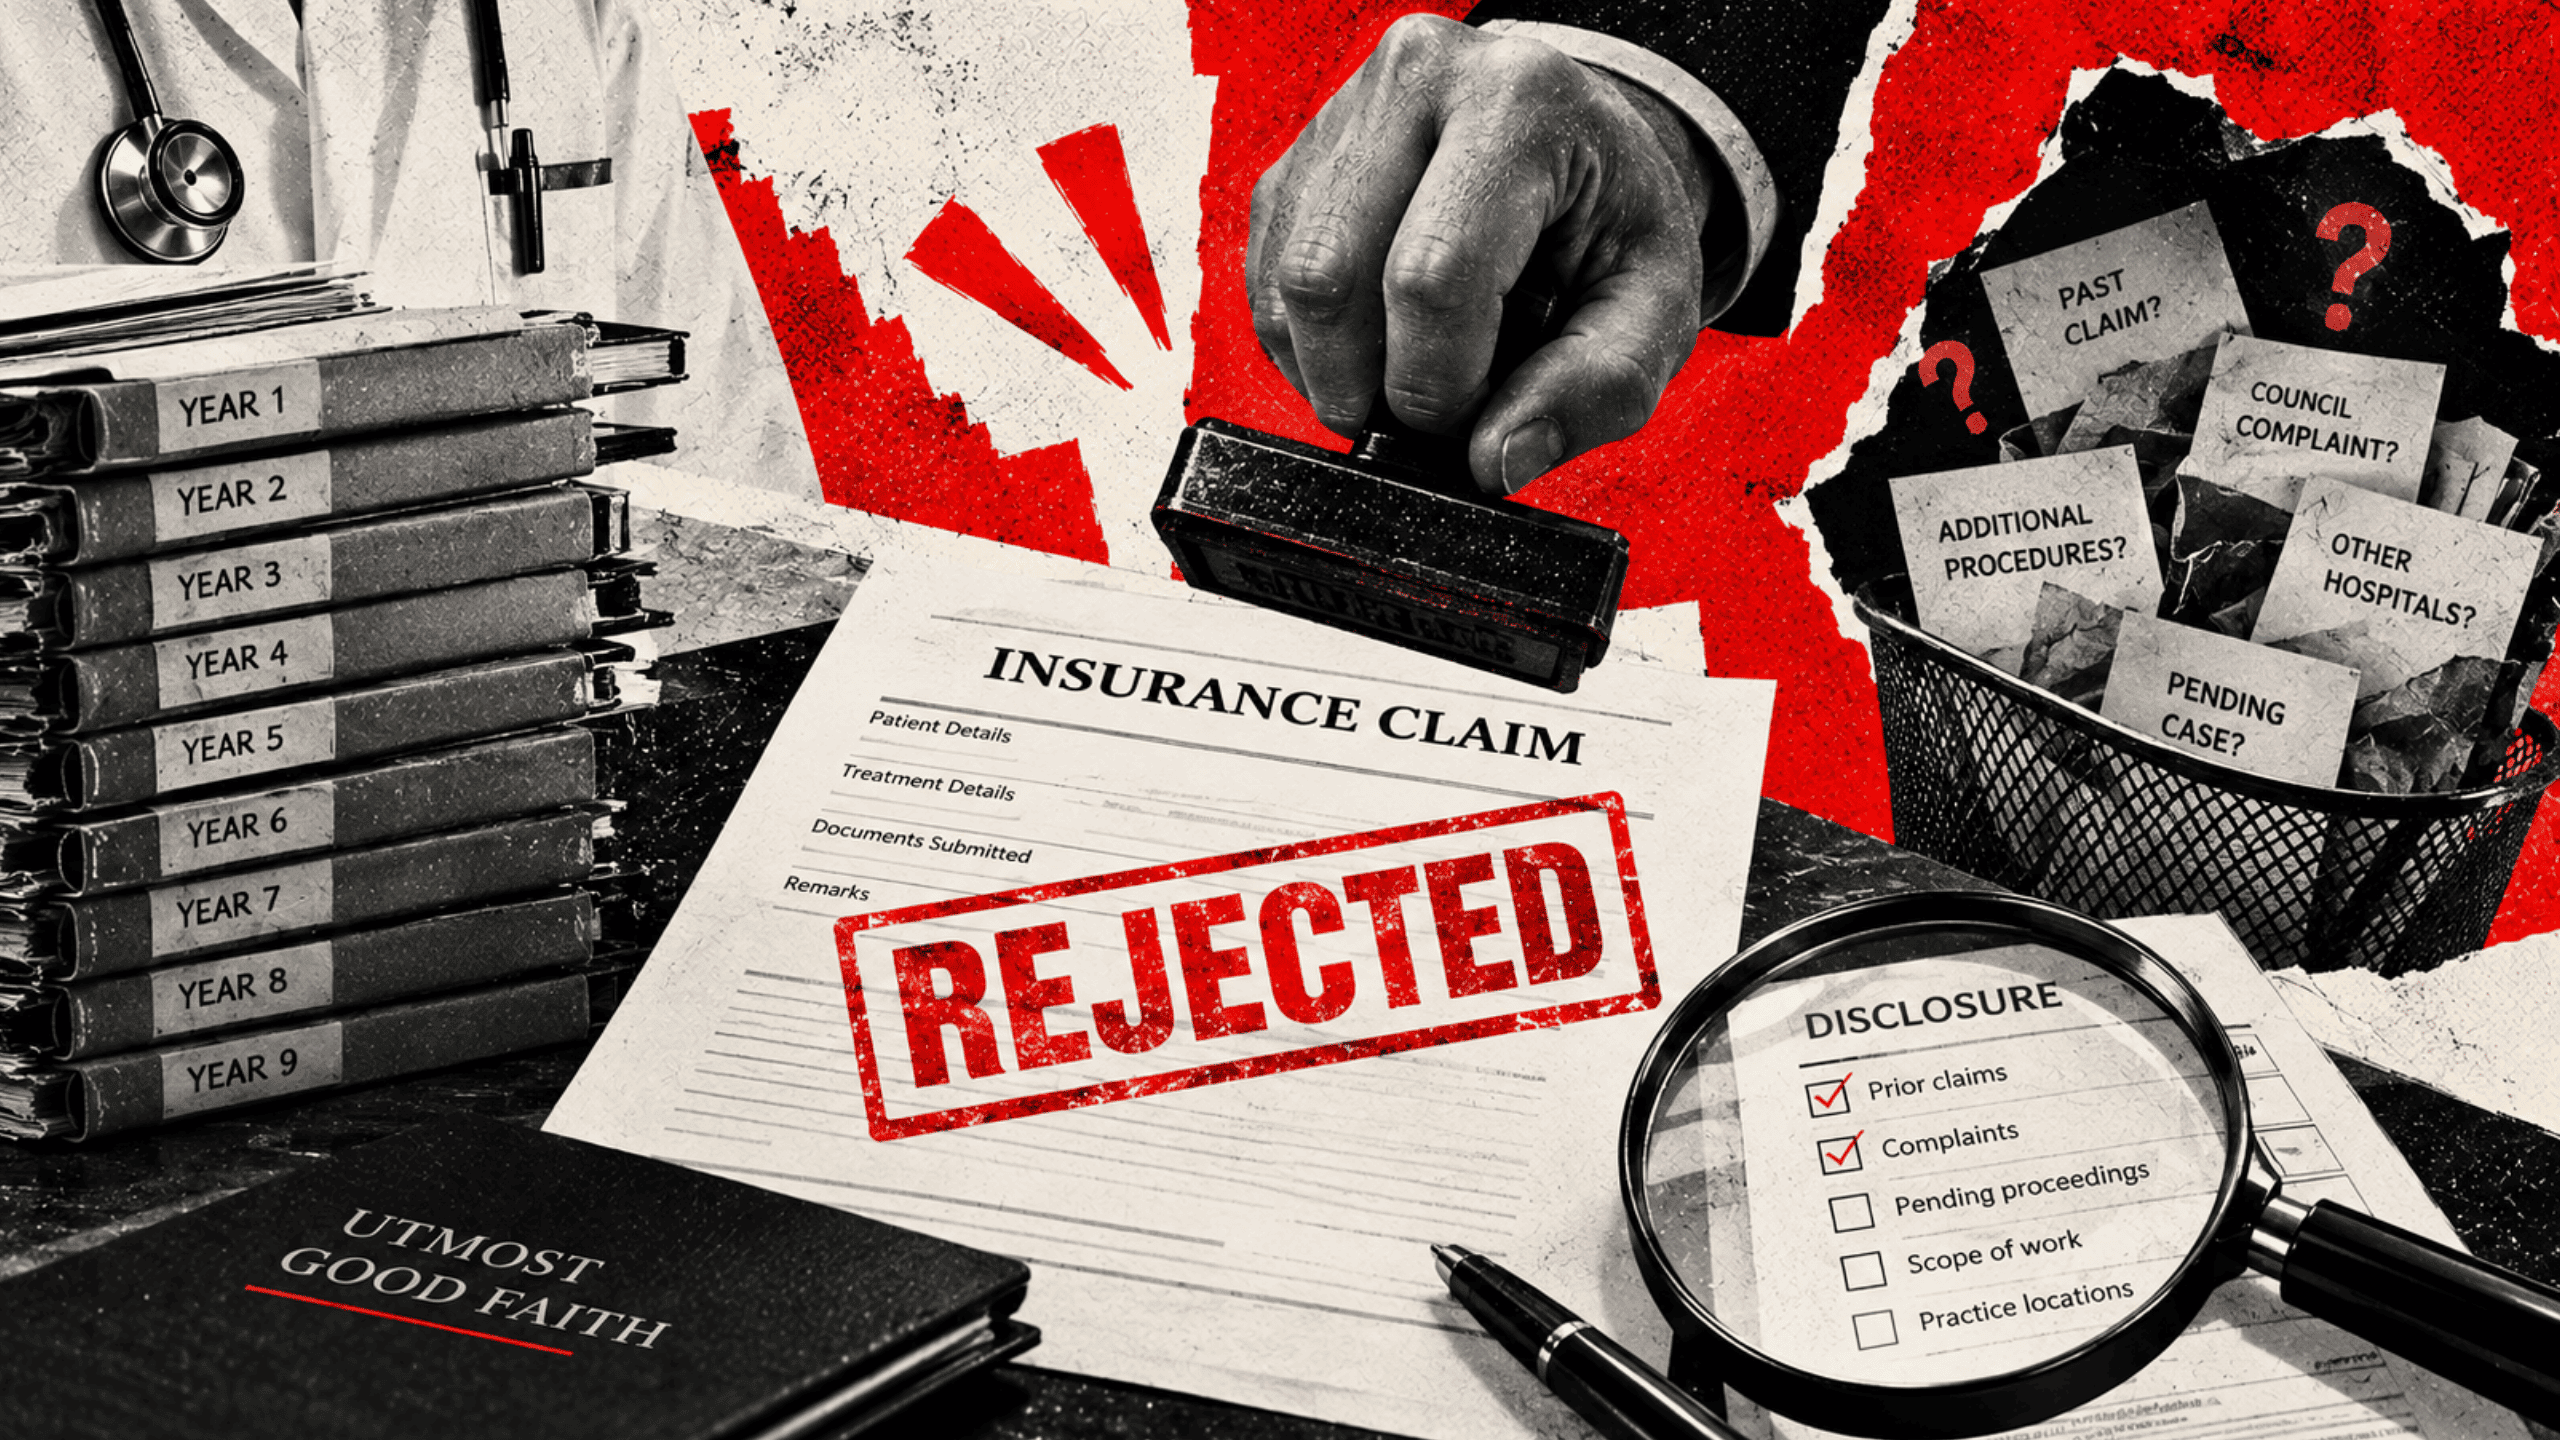
The Complaint That Comes Back

A complaint that appears forgotten can resurface when an insurer investigates a future claim.

You are on the exact last page of an insurance proposal form.

It is eleven at night.

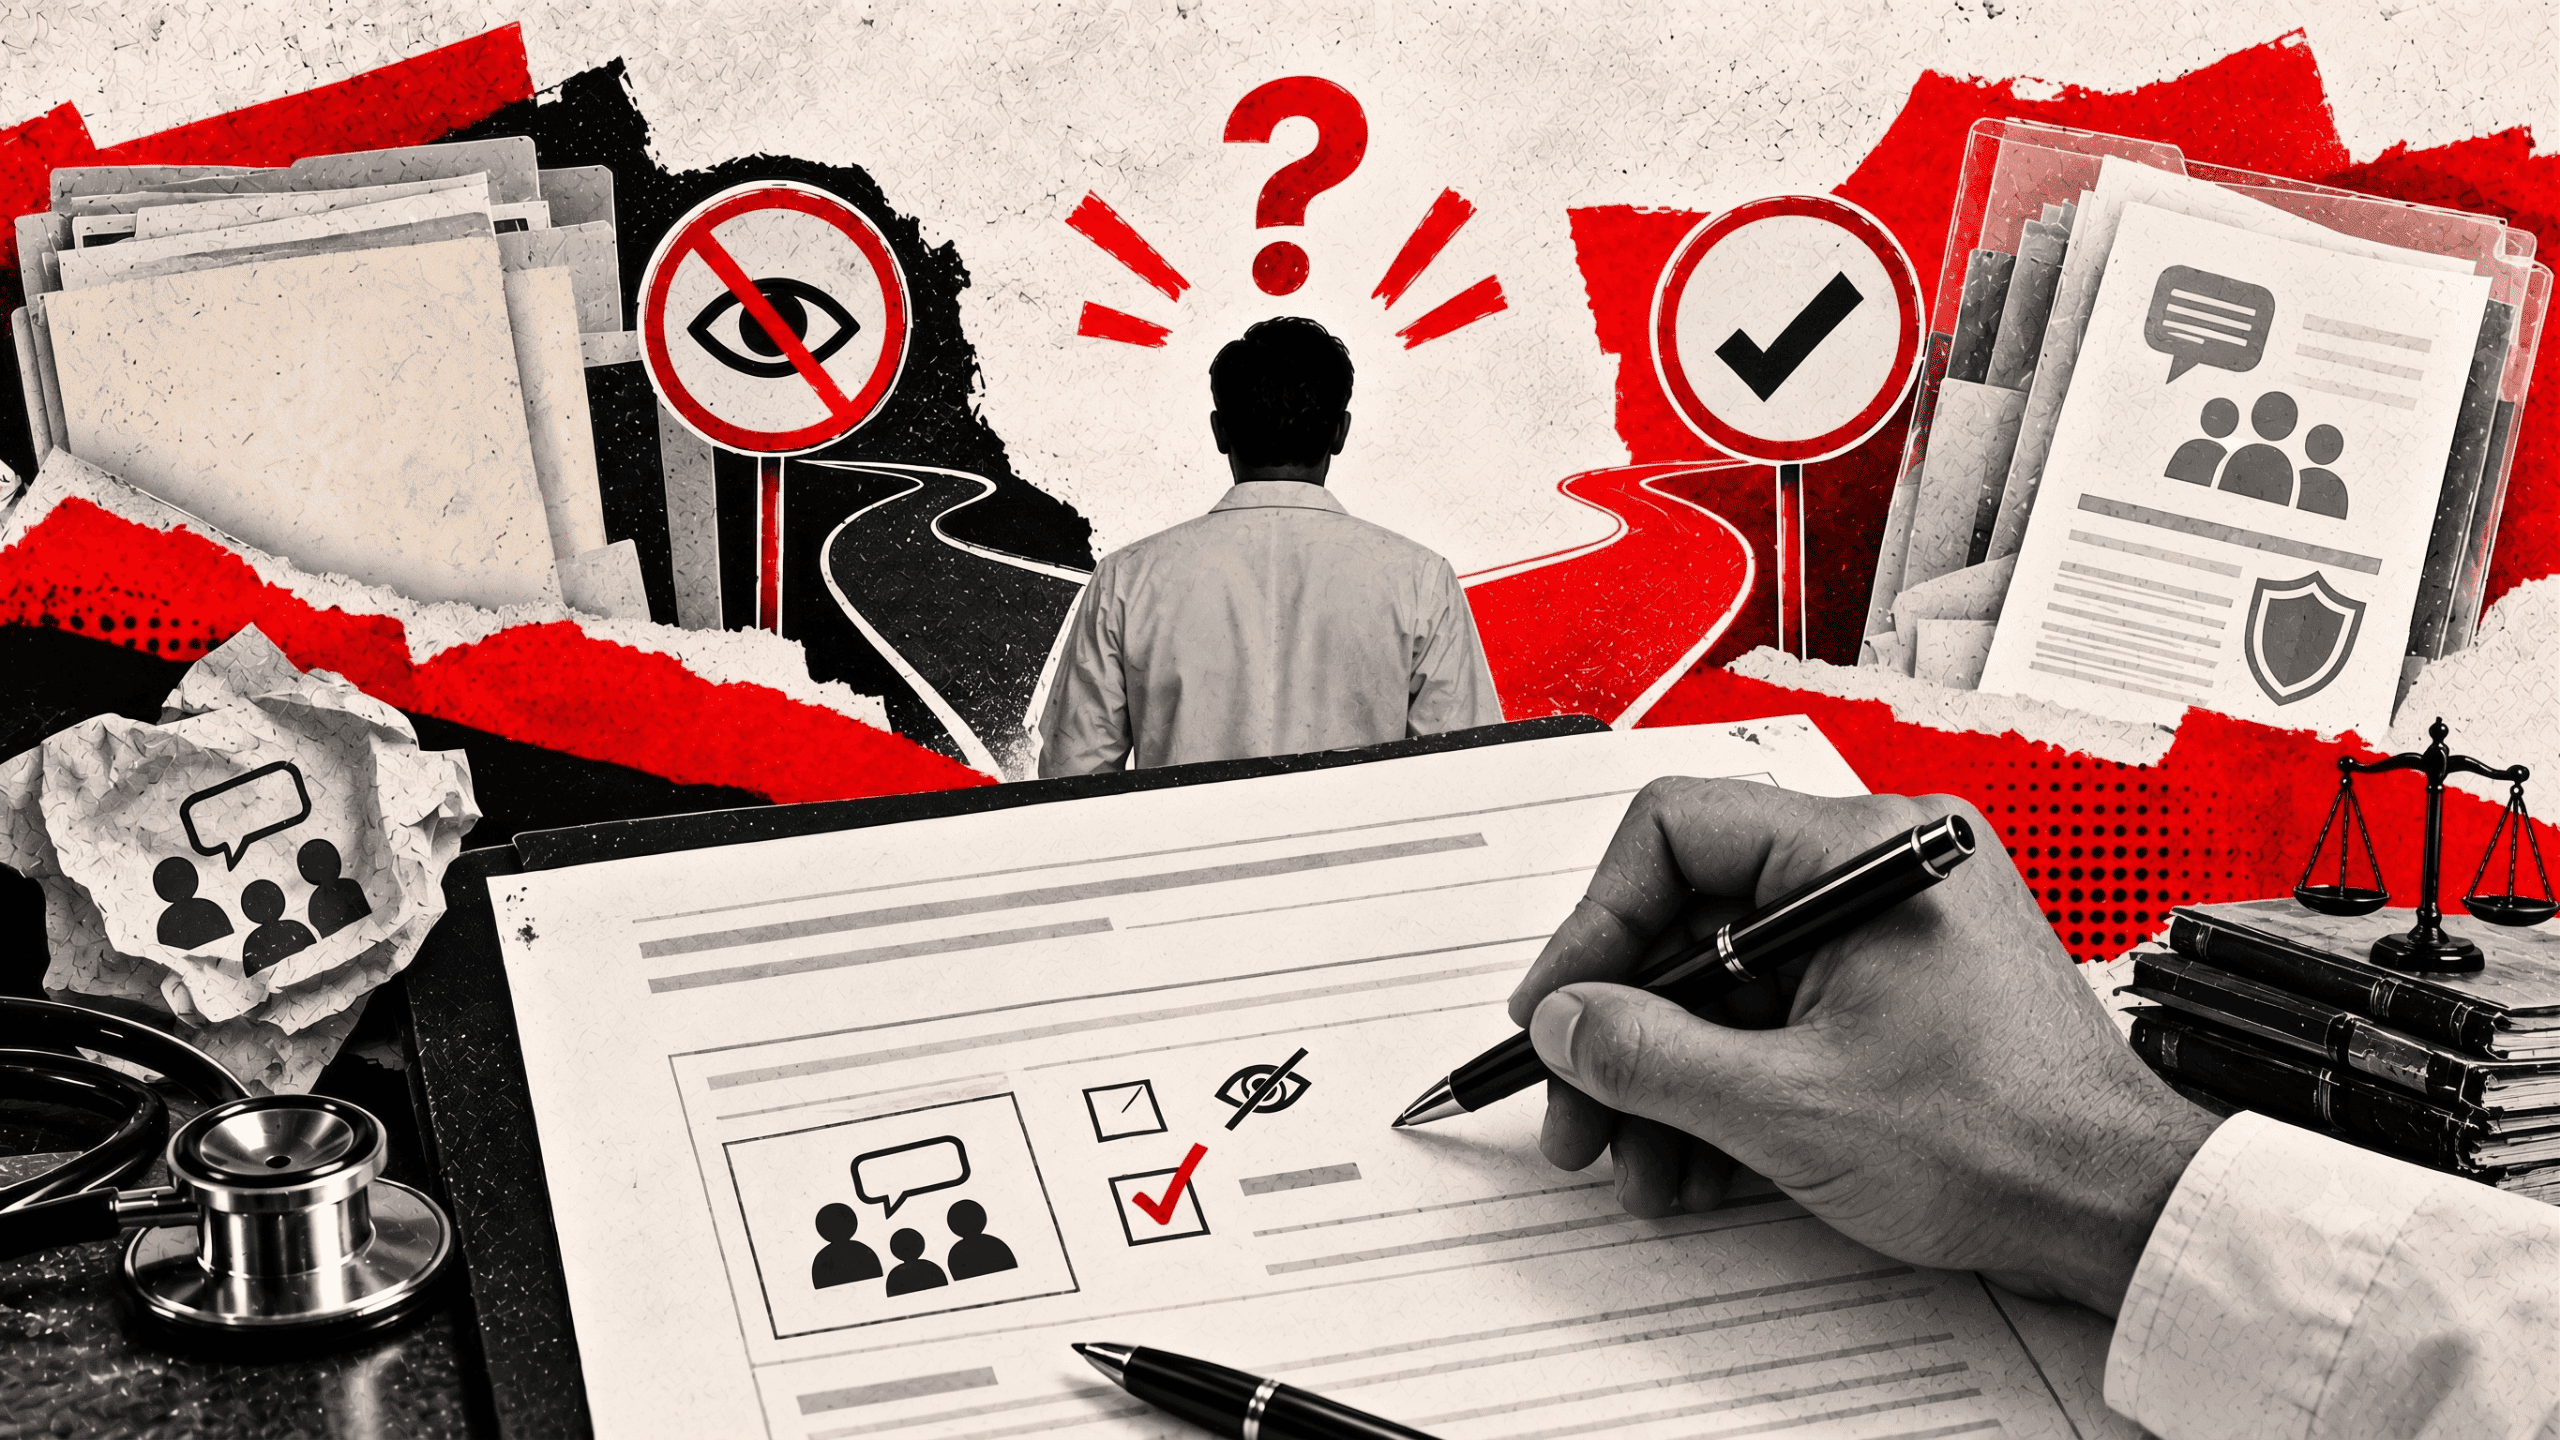
One specific box asks whether any complaint has ever been made against you.

Three years ago, a family wrote to your hospital. Specifically, they were unhappy with a clinical outcome.

You met them, and it was quickly resolved. Furthermore, nothing was ever legally filed.

Consequently, you sit there and think. Specifically, do I need to declare past complaint when buying indemnity cover for something that closed years ago?

Would anyone ever actually know?

They absolutely would. Insurers investigate liability claims properly. Therefore, the moment they look is the exact moment you need the policy to hold securely.

Why Disclosing Medical Complaints Matters

The underwriter pricing your cover has never watched you operate. Furthermore, they have never read a case sheet or spoken to your patient. All they have is your printed form.

So, Indian law firmly puts the duty on you. Under utmost good faith, you must strictly disclose every material fact. This includes anything that would reasonably affect whether the insurer accepts your medical risk. Answering only what is strictly asked is not enough. You can read more about utmost good faith under the Indian Contract Act.

It is worth separating two things doctors conflate here. Declaring a complaint is not an admission that you did something clinically wrong. Conversely, it is simply a factual statement that an event happened. Therefore, the insurer is legally entitled to know this before agreeing to carry you.

What Insurers Count As A Past Complaint

Doctors read this word very narrowly. However, insurers absolutely do not.

  • Written grievances: A letter or email to you, your clinic, or a hospital administrator.
  • Council references: Anything reported to a State Medical Council or the National Medical Commission.
  • Legal notices: From a patient advocate, whether or not a consumer case followed.
  • Internal enquiries: A hospital committee examining an adverse outcome.
  • Prior claims: Anything reported to a previous insurer, including matters closed without payment.

Verbal complaints sit in a grey zone. A raised voice at reception that went nowhere is generally not expected. However, anything recorded or acted on must be declared.

The True Cost Of Silence During Indemnity Insurance Renewal

Play the medical timeline forward. The exact mechanism is what makes this worth taking seriously.

Nothing happens at purchase. The policy issues easily. You renew for years, and everything looks completely fine. That is precisely the hidden problem. Consequently, the severe consequence is deferred to the one day you cannot absorb it.

When you finally file a claim, the investigator reviews hospital complaint registers. They check correspondence and prior insurer records. Therefore, the undeclared matter inevitably surfaces. The claim is quickly repudiated for material non disclosure. Furthermore, the policy may be treated as completely void from the start. Years of premium and the vital defence you were counting on disappear together. Check guidelines on IRDAI to understand policy voiding rules. This is exactly why asking do I need to declare past complaint when buying indemnity is so crucially important.

Will Declaring Past Medical Negligence Complaints Raise Your Premium?

This is the real fear behind do I need to declare past complaint when buying indemnity cover. However, it is mostly misplaced. Underwriters see medical complaints constantly. A long career with a perfectly blank record is highly unusual.

  • One resolved complaint: Usually means no change at all, especially if it closed without payment.
  • A paid claim: May attract a modest financial loading, much like a motor claim at renewal.
  • Repeated similar complaints: Prompts questions about protocols, and sometimes triggers a specific exclusion.
  • Live or serious matters: Usually results in one named exclusion, with the rest of the cover completely intact.

In most cases, declaring simply changes the paperwork. It does not change the actual price. Set that against a repudiated claim, and it stops being a difficult decision.

How To Declare Past Grievances In Five Minutes

Disclosure is a professional skill. Doing it badly can create confusion where none existed. Therefore, keep it factual, complete, and completely unemotional.

State the facts only. Include the exact date, what the grievance was, and how it closed. Provide absolutely no defensiveness and no clinical argument. Attach the closure letter if you have one. Furthermore, ask your previous insurer for a claims experience letter so nothing is missed. Finally, keep a written acknowledgement that the disclosure was formally received.

The Final Rule For Indemnity Insurance Application

If you are unsure whether something qualifies, simply put it on the form. Let the professional underwriter decide.

Nobody has ever lost a legal claim for declaring too much. Conversely, plenty have lost one for declaring too little. The massive difference is just five minutes on a form you fill in once a year. Understanding do I need to declare past complaint when buying indemnity fully protects your hard earned medical practice. For dispute resolution queries, always check with the Council for Insurance Ombudsmen.

5 FAQ SECTION

Do I need to declare verbal complaints from patients?

Only if they were recorded, escalated, or acted upon. A passing expression of dissatisfaction that went nowhere is generally not expected. If it reached a register, an email, or a committee, declare it.

Will a resolved complaint get my application rejected?

Very rarely. Insurers expect complaints across a medical career. A single resolved matter usually results in no change to terms at all. Outright rejection is strictly reserved for serious or repeated issues.

What if the complaint was against my clinic staff, not me?

Declare it. If it arose from treatment under your supervision or in your establishment, it forms part of your risk profile. Therefore, an insurer will regard it as highly material.

How far back should I check my records?

Five to seven years is the usual expectation. However, some proposal forms ask about your entire career. Read the question exactly as worded and answer that period honestly.

Does declaring a complaint mean it will be excluded from cover?

Not necessarily. Closed matters are typically noted and nothing more. An exclusion is normally applied only where a dispute is still live or a claim is reasonably foreseeable.
Tags: claims made policy doctorsconsumer court medical complaintdo I need to declare past complaint when buying indemnitydoctor insurance applicationdoctor legal advicedoctor liability insurancedoctor risk assessmenthealthcare risk protectioninsurance non disclosurematerial fact disclosuremedical indemnity proposal formmedical malpractice covermedical negligence complaintprofessional indemnity Indiaunderwriting medical insurance
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

Paid Every Premium, Still Rejected

Next Post

Switching Insurers? Read This First

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Protection Beyond the Age Barrier
Blog

Still Practising At 68? The Age Limit Myth

September 16, 2026
Racing the Clock to Get Covered
Blog

Covered By Tonight? Policy Activation Timelines Explained

September 16, 2026
One Case Behind You, Future Risk Ahead
Blog

A Pending Case And A New Insurance Policy

September 16, 2026
The Gap That Breaks Your Protection
Blog

Eleven Days Uncovered: An Indemnity Policy Lapse

September 16, 2026
Switching Insurers? Read This First
Blog

Switching Insurers? Read This First

September 16, 2026
The Claim That Never Gets Through
Blog

Paid Every Premium, Still Rejected

September 16, 2026
Next Post
Switching Insurers? Read This First

Switching Insurers? Read This First

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Still Practising At 68? The Age Limit Myth
  • Covered By Tonight? Policy Activation Timelines Explained
  • A Pending Case And A New Insurance Policy
  • Eleven Days Uncovered: An Indemnity Policy Lapse
  • Switching Insurers? Read This First

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In