You ask three people and get three answers.
A colleague says fifty lakh is plenty. A broker suggests two crore. A quote page offers you six options and explains none of them.
None of them show their working, because there is none to show.
So how much indemnity cover is enough for a surgeon in India? There is no published answer — and understanding why is the first step to choosing well.
Nobody Publishes A Number, And That Is Not An Oversight
No IRDAI rule, no medical council regulation and no hospital empanelment norm I could find prescribes a minimum sum insured for a doctor of any specialty. Insurers publish purchase options — twenty-five lakh, fifty lakh, one crore and upwards — but not guidance on which to pick.
Nor is there a reliable published dataset of what Indian consumer commissions actually award, broken down by specialty. Figures that circulate as “the average medical negligence award” are anecdotal. Treat any article quoting one with suspicion, including one that quotes a very large Supreme Court award as though it were typical. Outliers describe the tail, not the middle.
Reason From Your Own Exposure Instead
Without a benchmark, the only honest way to settle how much indemnity cover is enough for a surgeon is to describe your own risk and let the figure follow from it.
- What you operate on: A procedure with a catastrophic failure mode carries a different tail than one that does not, whatever the volume.
- What the worst outcome looks like: Not the most likely complication. The one that would end up in a commission.
- Who your patients are: Earning capacity feeds directly into compensation, because Indian courts assess loss individually rather than by formula.
- How often you operate: Frequency drives the annual aggregate; severity drives the per-claim limit.
- Where you work: Empanelment contracts sometimes specify a minimum. Read them before you choose.
- Whether you also consult: A mixed practice has both a wide and a deep exposure, and the two are priced differently.
The Number Behind The Number
Before settling on a figure, there is a structural point that changes what any figure is worth.
One structural point does more work than any benchmark: your sum insured has two limits, not one.
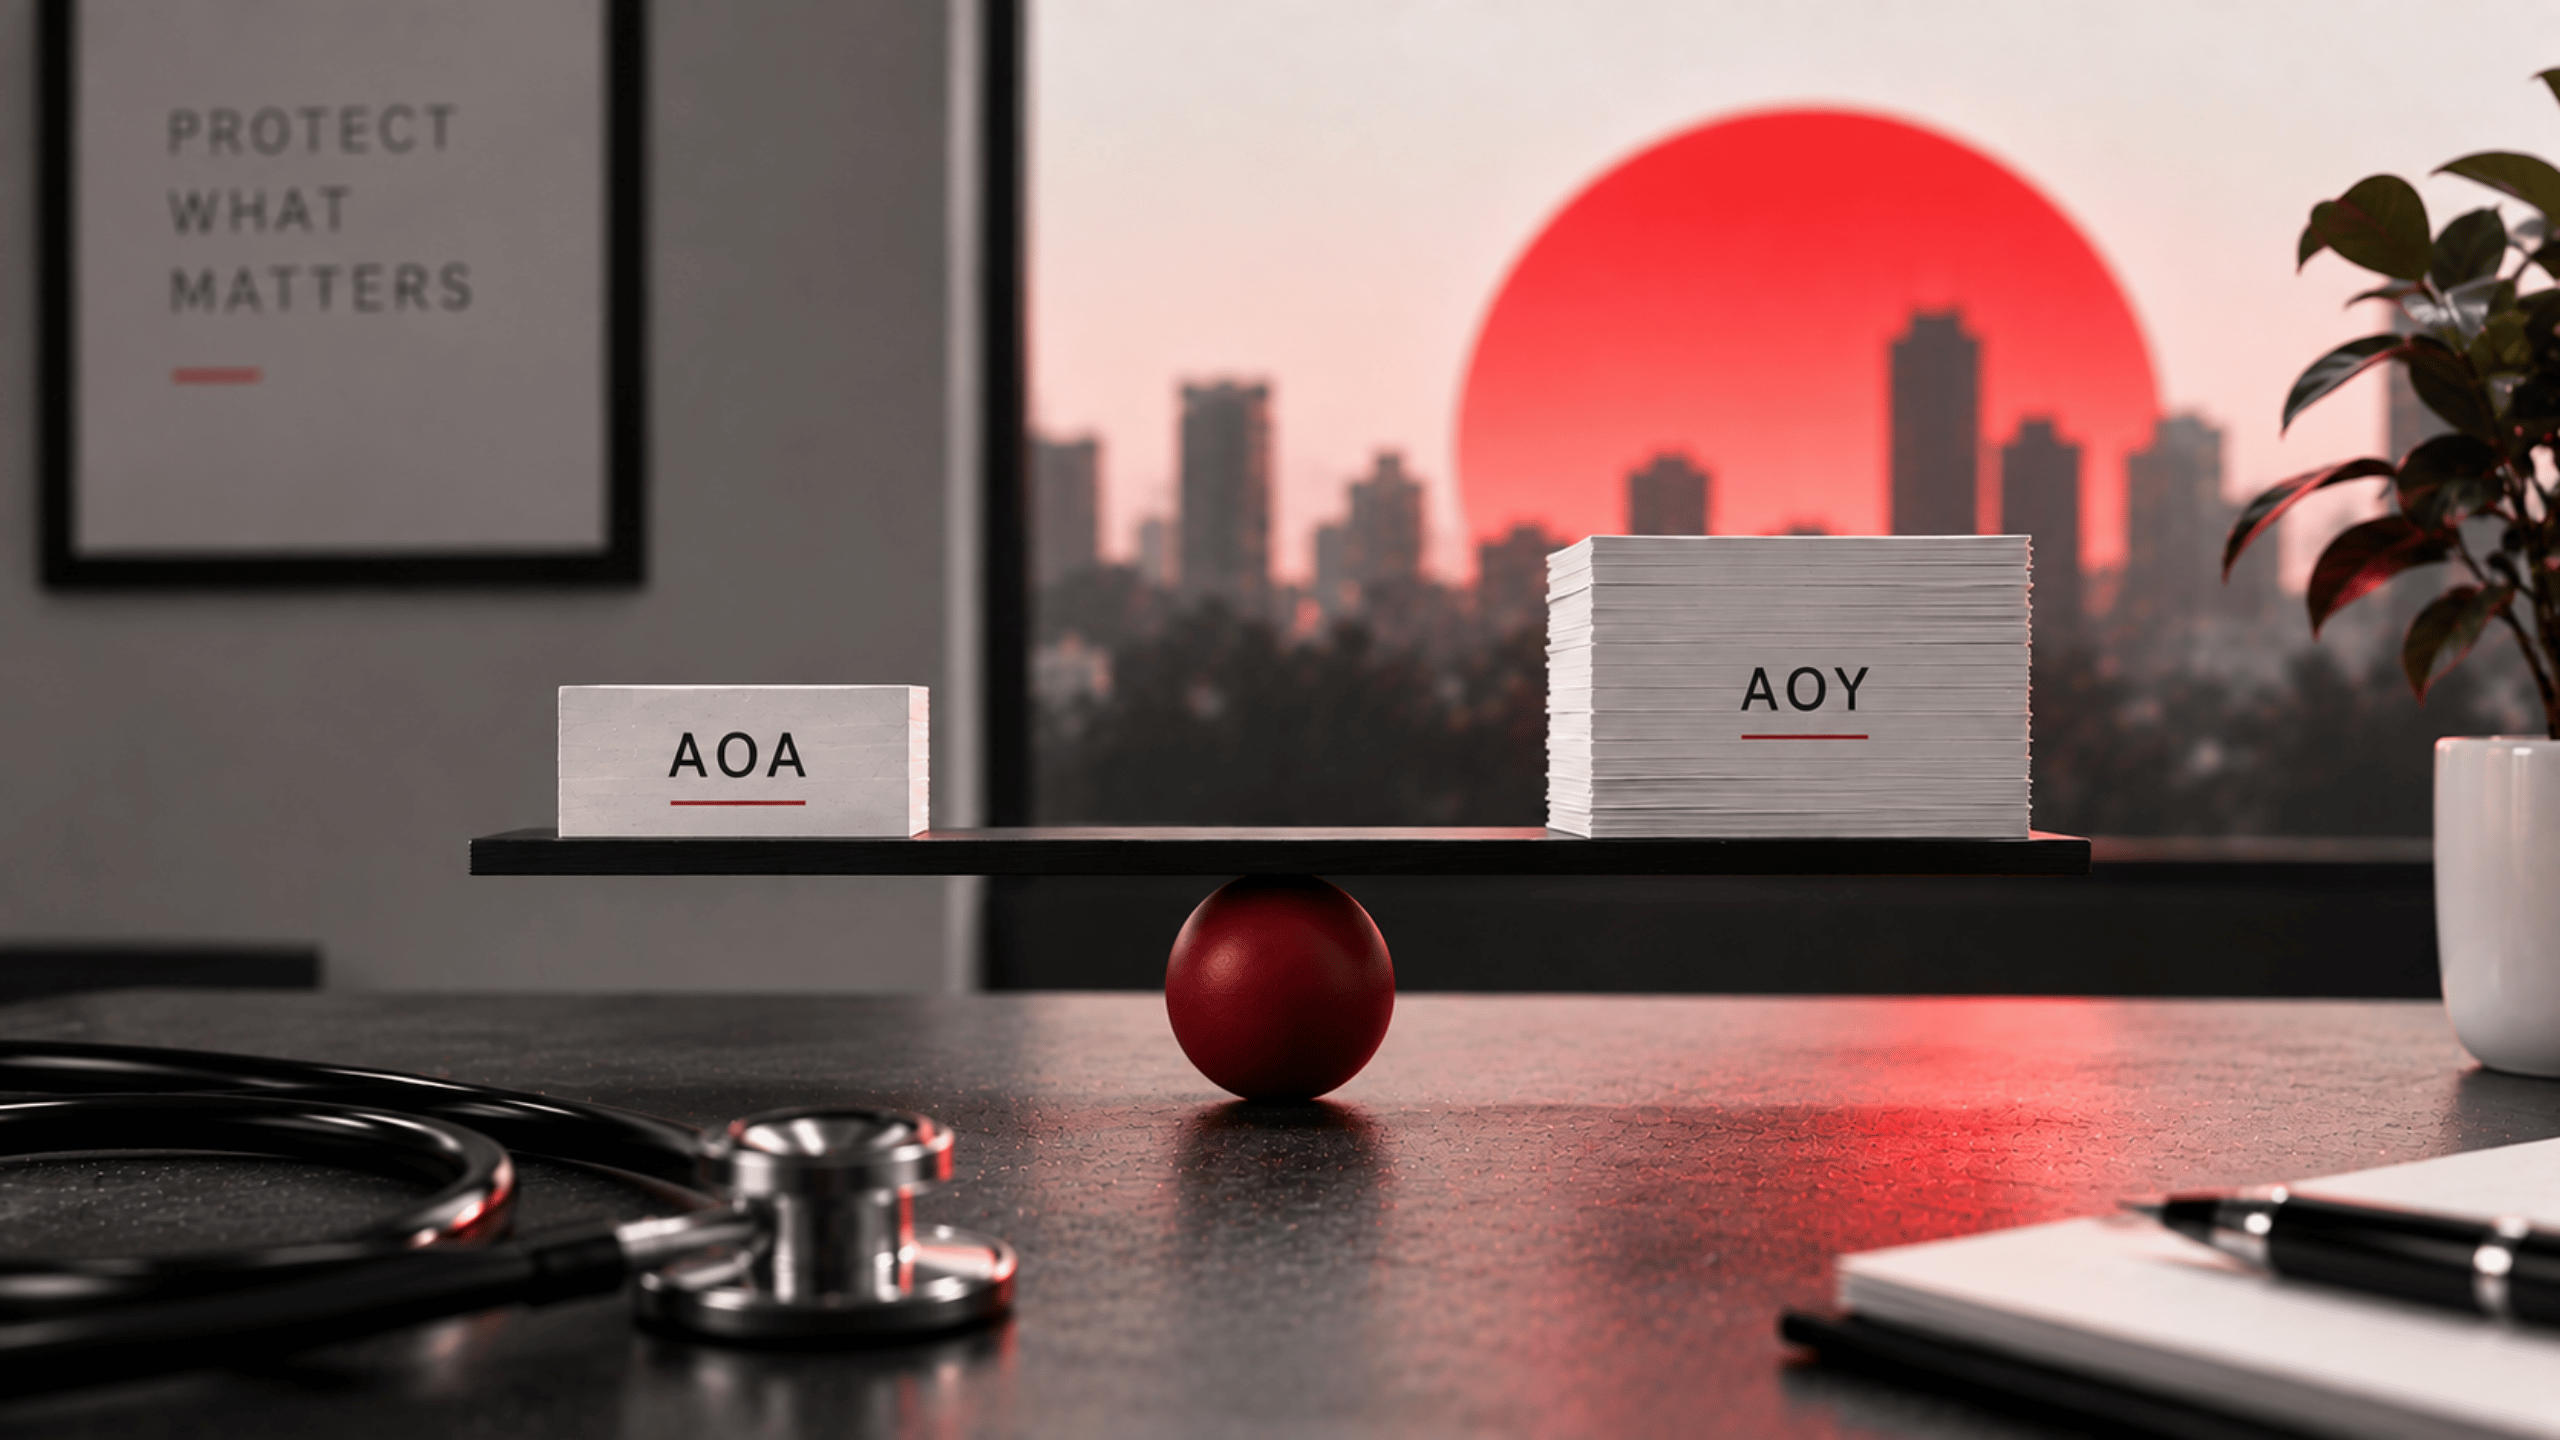
AOA caps a single claim. AOY caps everything payable in the policy year. A one crore AOY at a 1:4 ratio means no single claim can draw more than twenty-five lakh — which for a surgeon is often the wrong shape of cover, because surgical claims tend to be few and large rather than many and small. The AOA and AOY ratio deserves more of your attention than the headline figure.
Remember too that defence costs come out of the same pot. A multi-year defence consumes cover before any award is decided.
How Much Indemnity Cover Is Enough For A Surgeon In Practice?
Ask the question a different way. Not what is average, but what would a single worst outcome in your own theatre actually cost — the compensation, the years of defence, and the shortfall you would fund yourself.
Then check the shape as well as the size: the AOA, the AOY, the excess, and what the policy does not cover at all. A larger sum insured with the wrong ratio can protect you less than a smaller one with the right one. If you are weighing two specific figures, the one crore against fifty lakh comparison works through the arithmetic.
And revisit it. A limit chosen when you were doing two lists a week describes a practice you may not still run.
The Takeaway
How much indemnity cover is enough for a surgeon is not a question with a market answer. It is a question about your own worst day.
Price that day honestly, buy the shape as carefully as the size, and revisit it whenever your practice changes.
Frequently Asked Questions
Is there a minimum indemnity cover required for surgeons in India?
No regulatory minimum was found from IRDAI or the medical councils. Some hospital empanelment contracts specify a figure, which is a contractual requirement rather than a legal one.
What is the average medical negligence award in India?
No systematic published dataset exists. Figures circulating as averages are anecdotal, and widely quoted large awards are outliers rather than benchmarks.
Should a surgeon prefer a higher per-claim limit?
Surgical claims tend to be fewer and larger, which is generally an argument for a higher AOA relative to the annual aggregate. The right answer depends on your practice and the terms offered.
Do defence costs reduce the sum insured?
In the Indian doctors’ wordings examined, yes. Money spent defending a claim reduces what remains for an award, which is a reason not to size cover too tightly.
Does my hospital’s cover count towards this?
Usually not in full. Institutional policies typically protect the institution and may exclude individual professional acts. Read the contract rather than assuming.
How often should I review my sum insured?
At every renewal, and whenever your procedure mix, volume or practice setting changes. A limit chosen five years ago describes a practice you may no longer run.