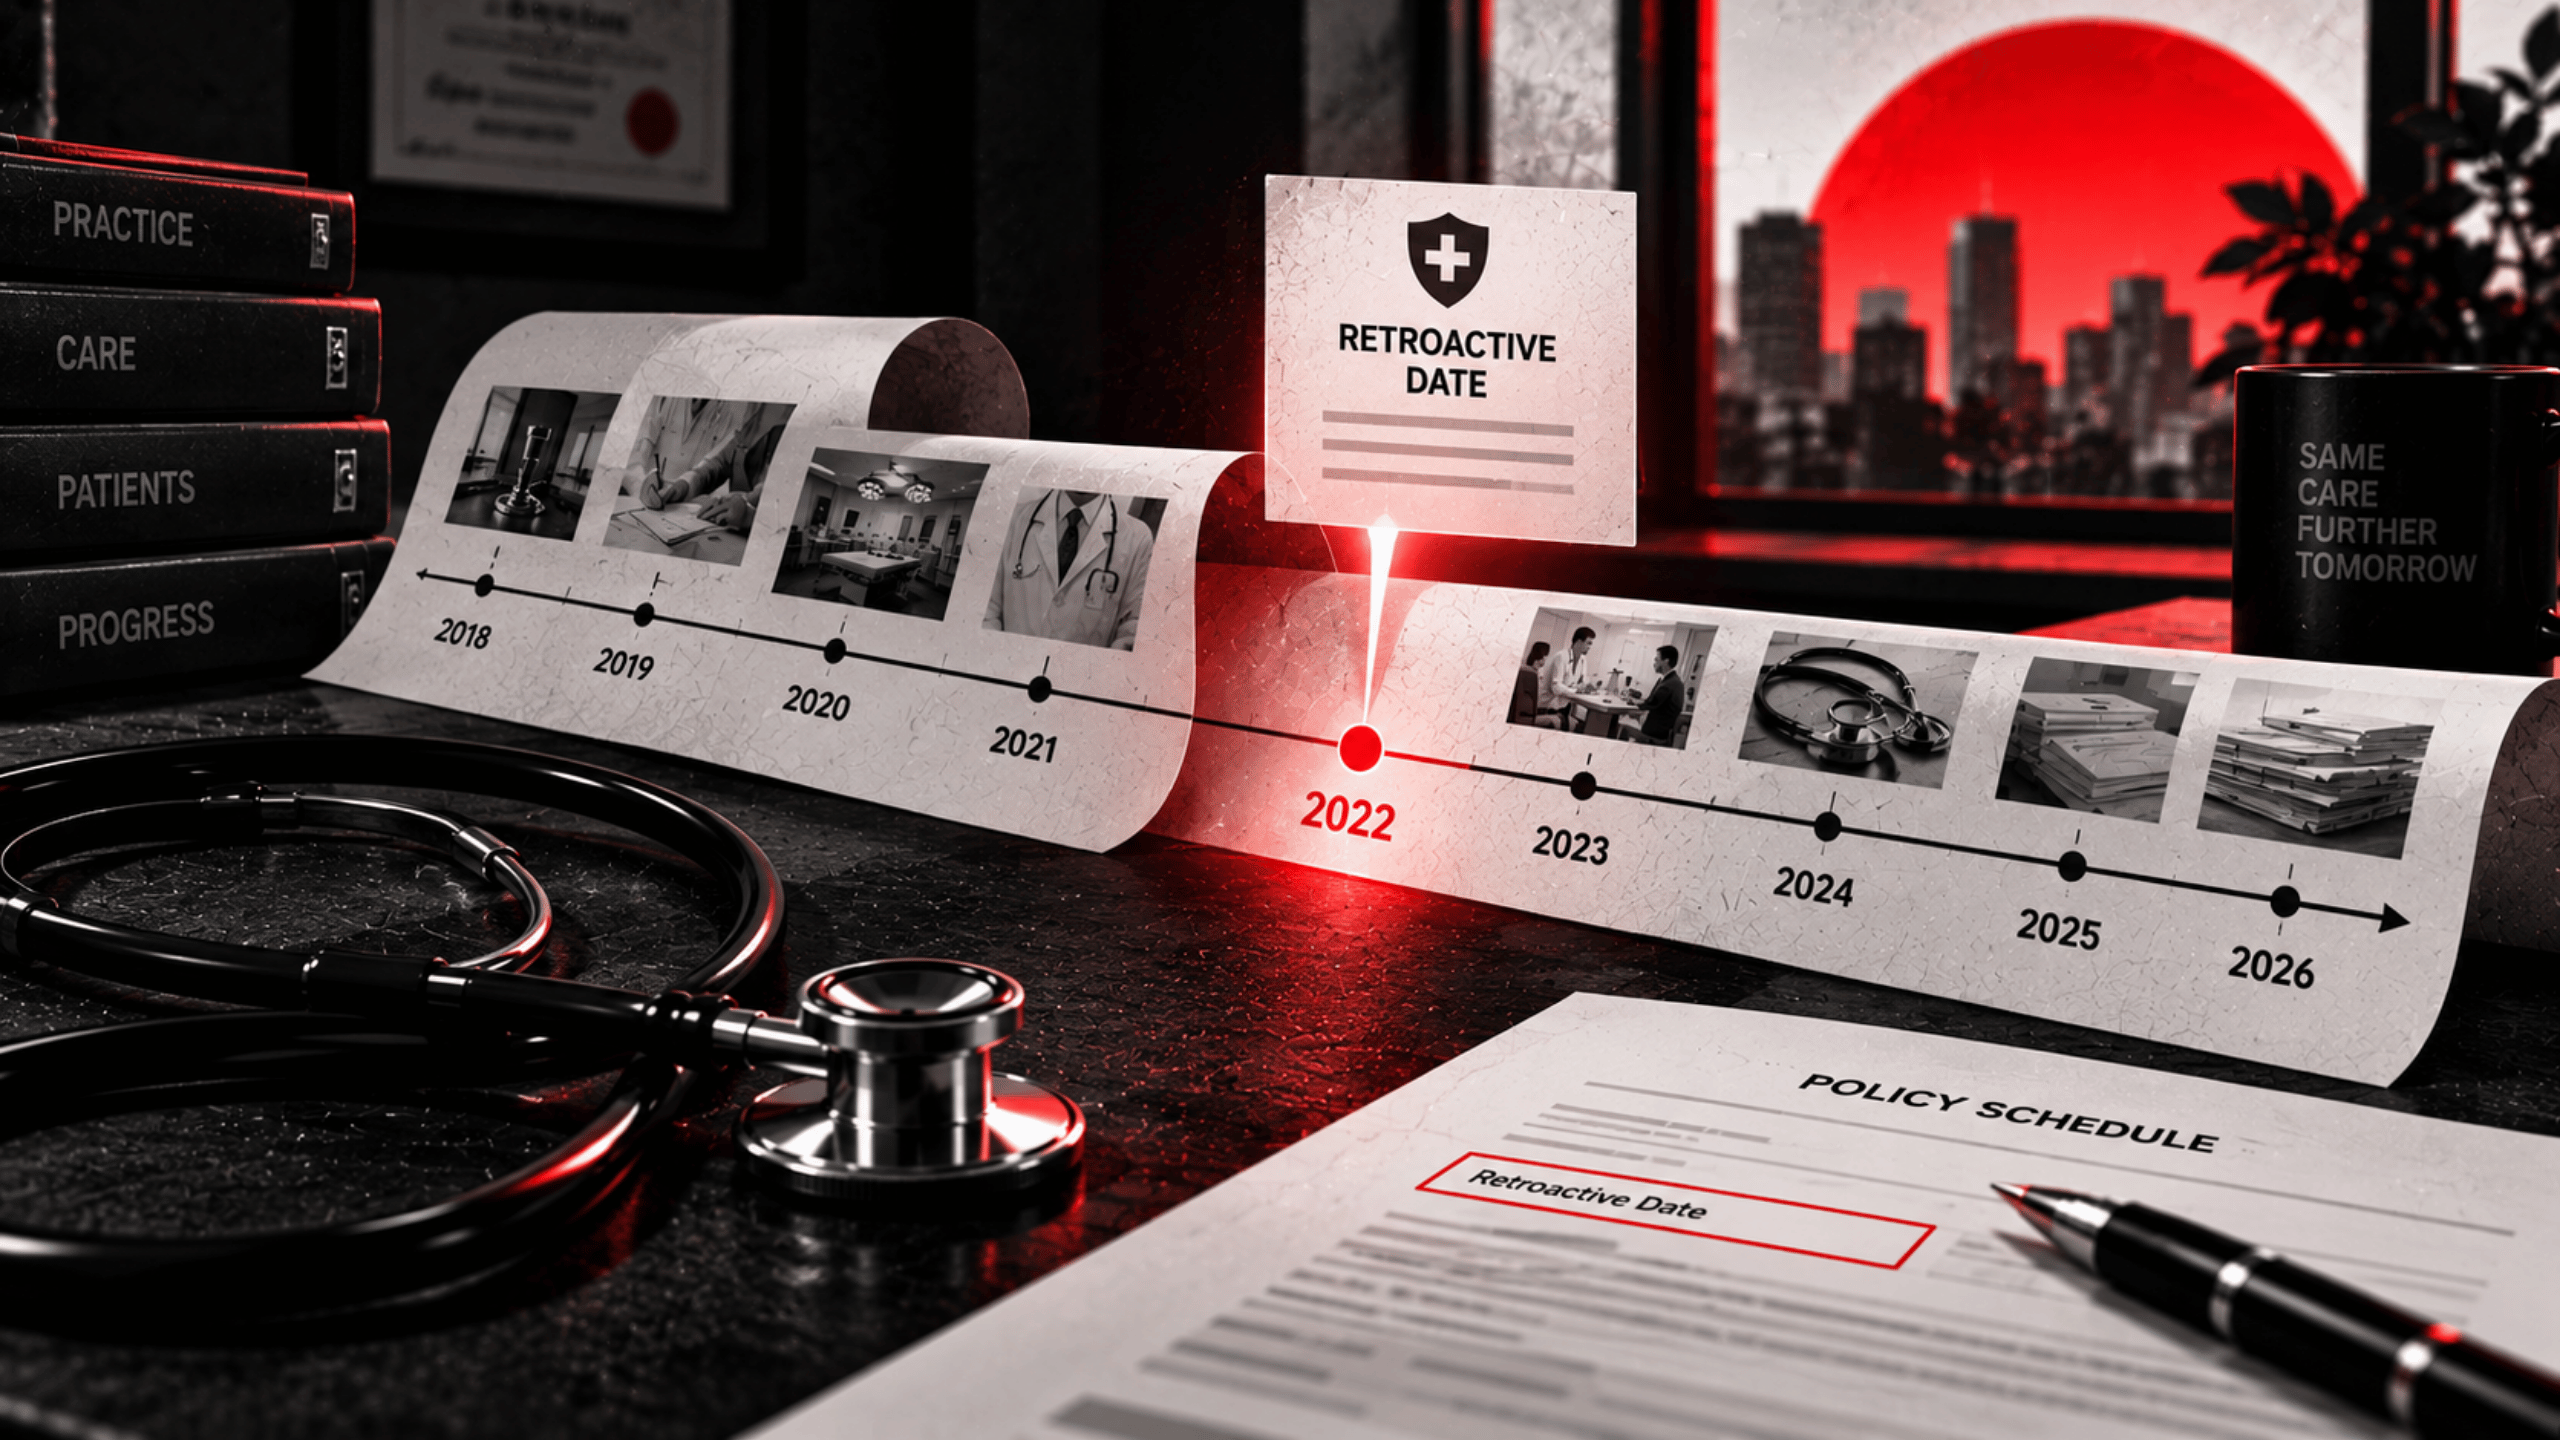
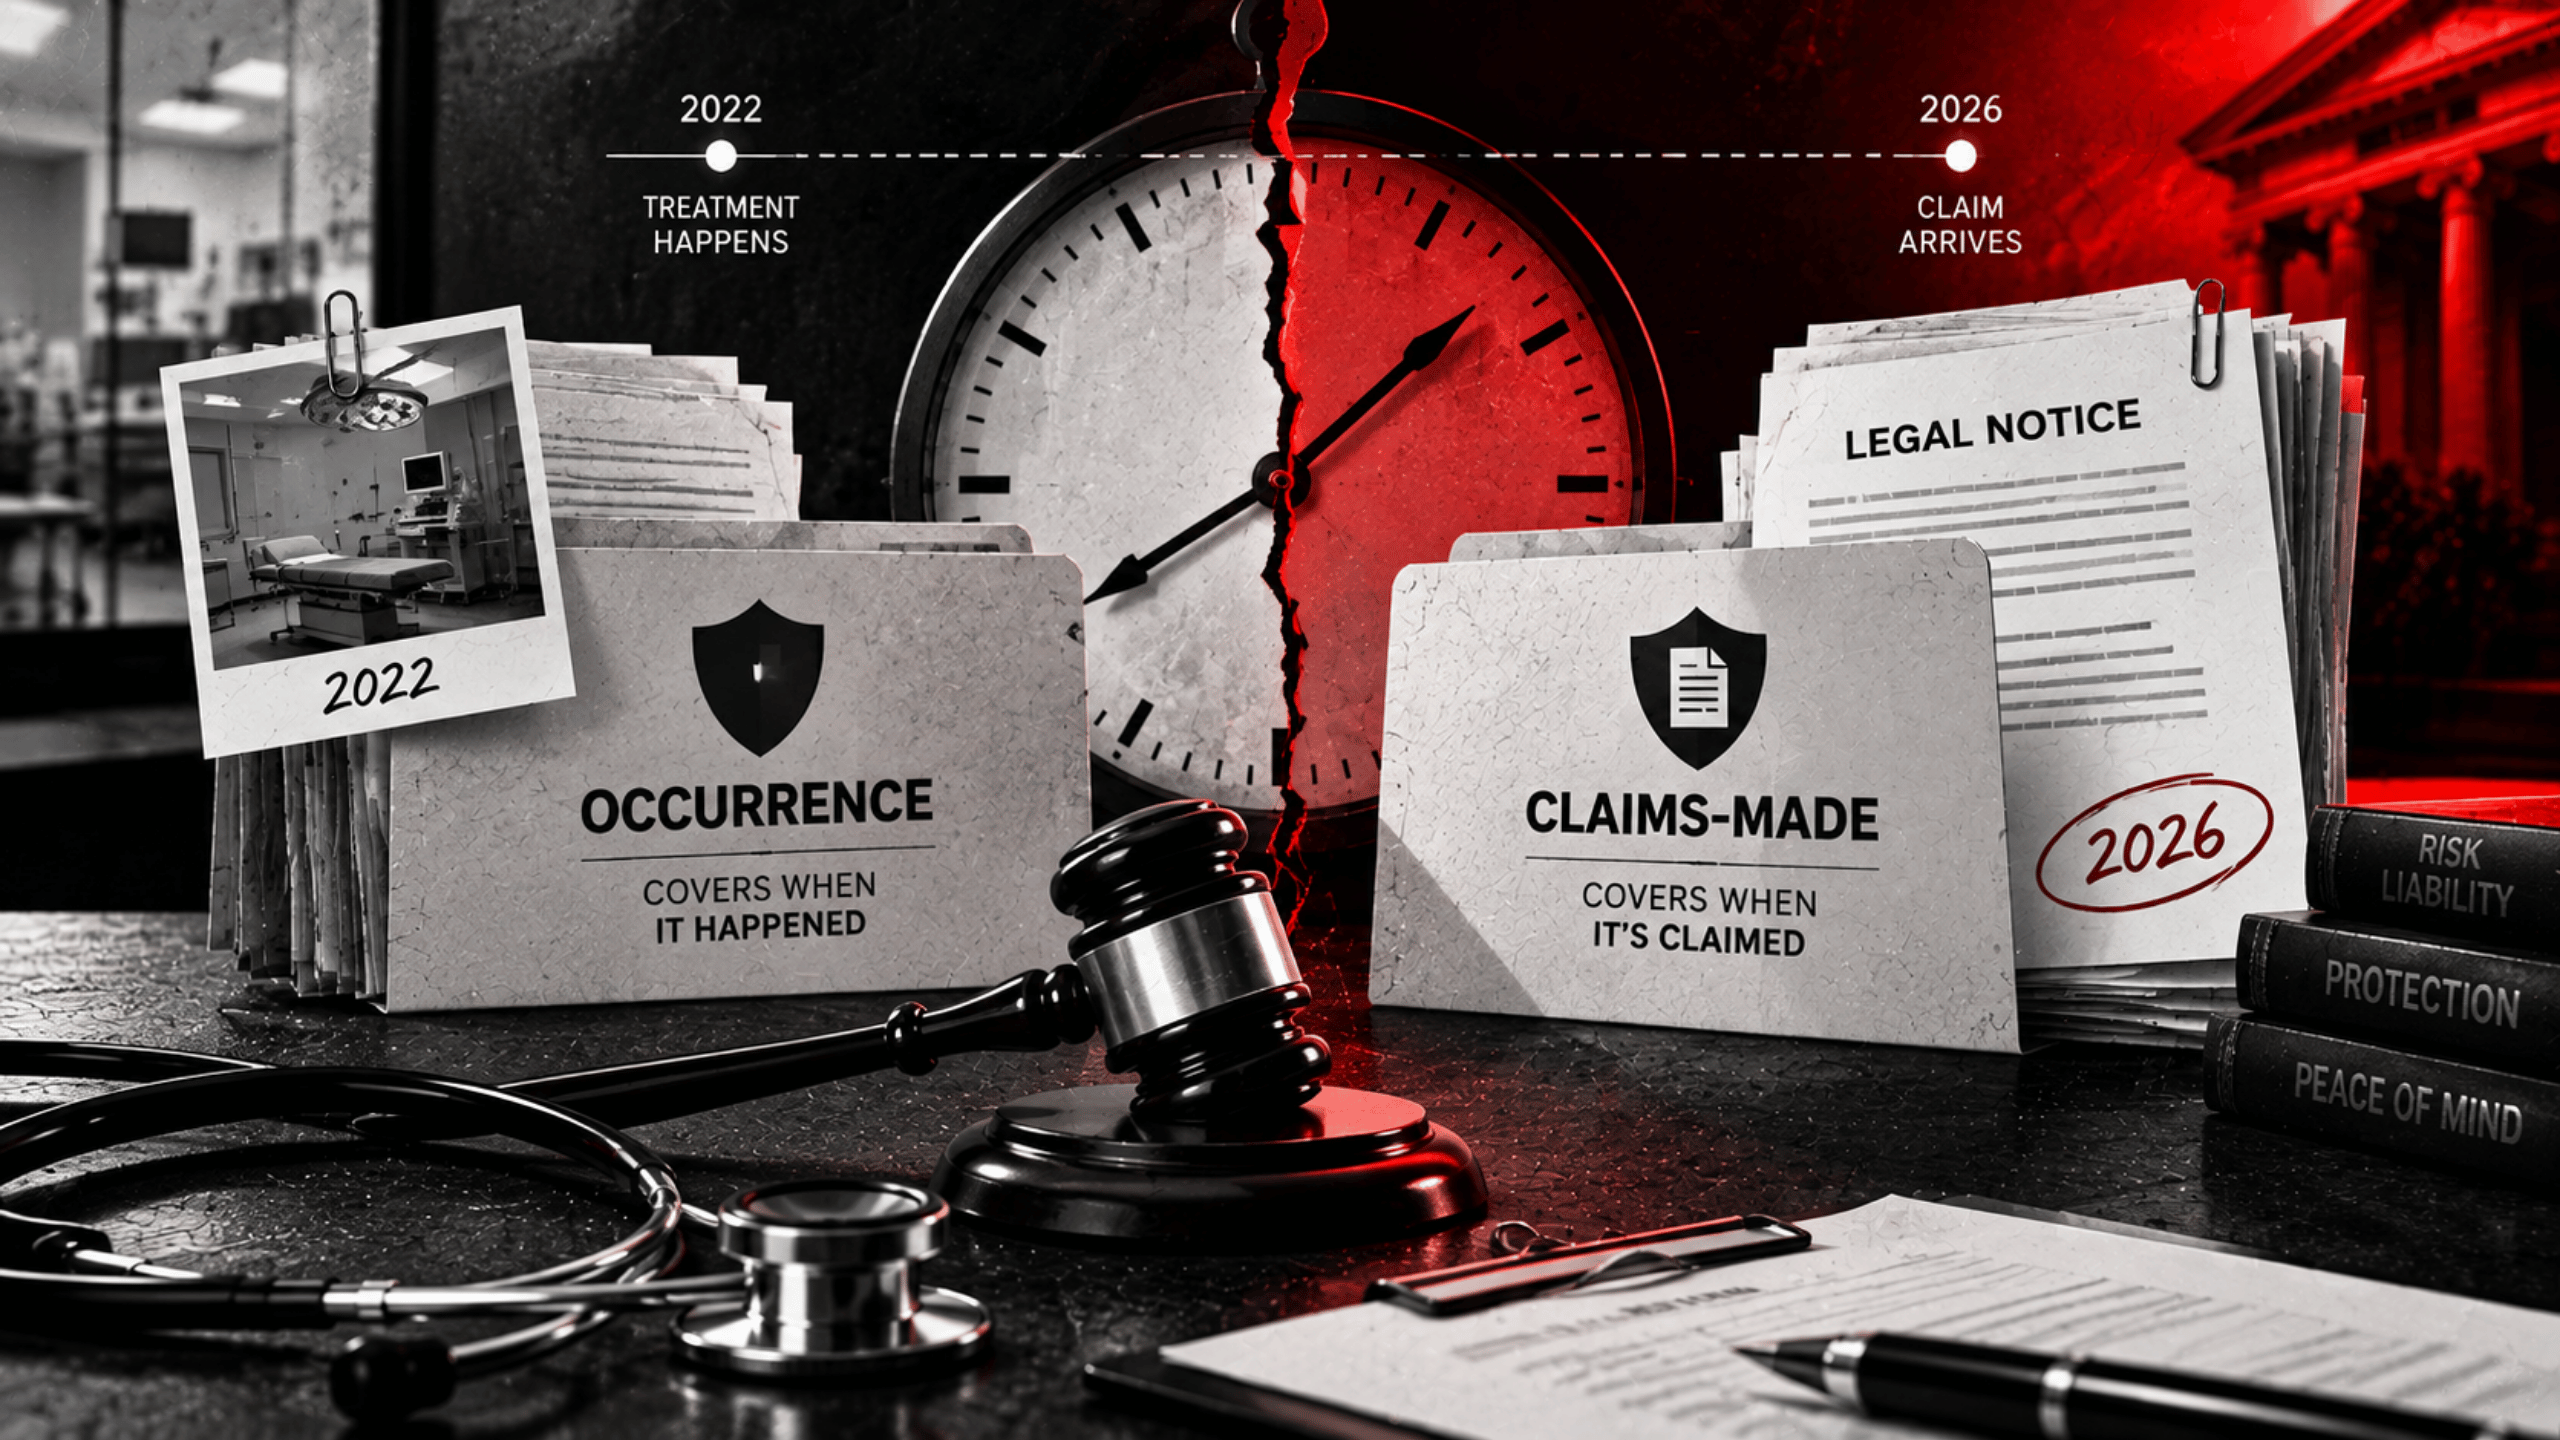
A patient you treated in 2022 suddenly files a medical negligence complaint in 2026.
You were fully insured back in 2022.
Furthermore, you are actively insured right now.
You hold two policies from two different insurance companies. Consequently, any reasonable person would assume that one of these policies will respond to the legal notice.
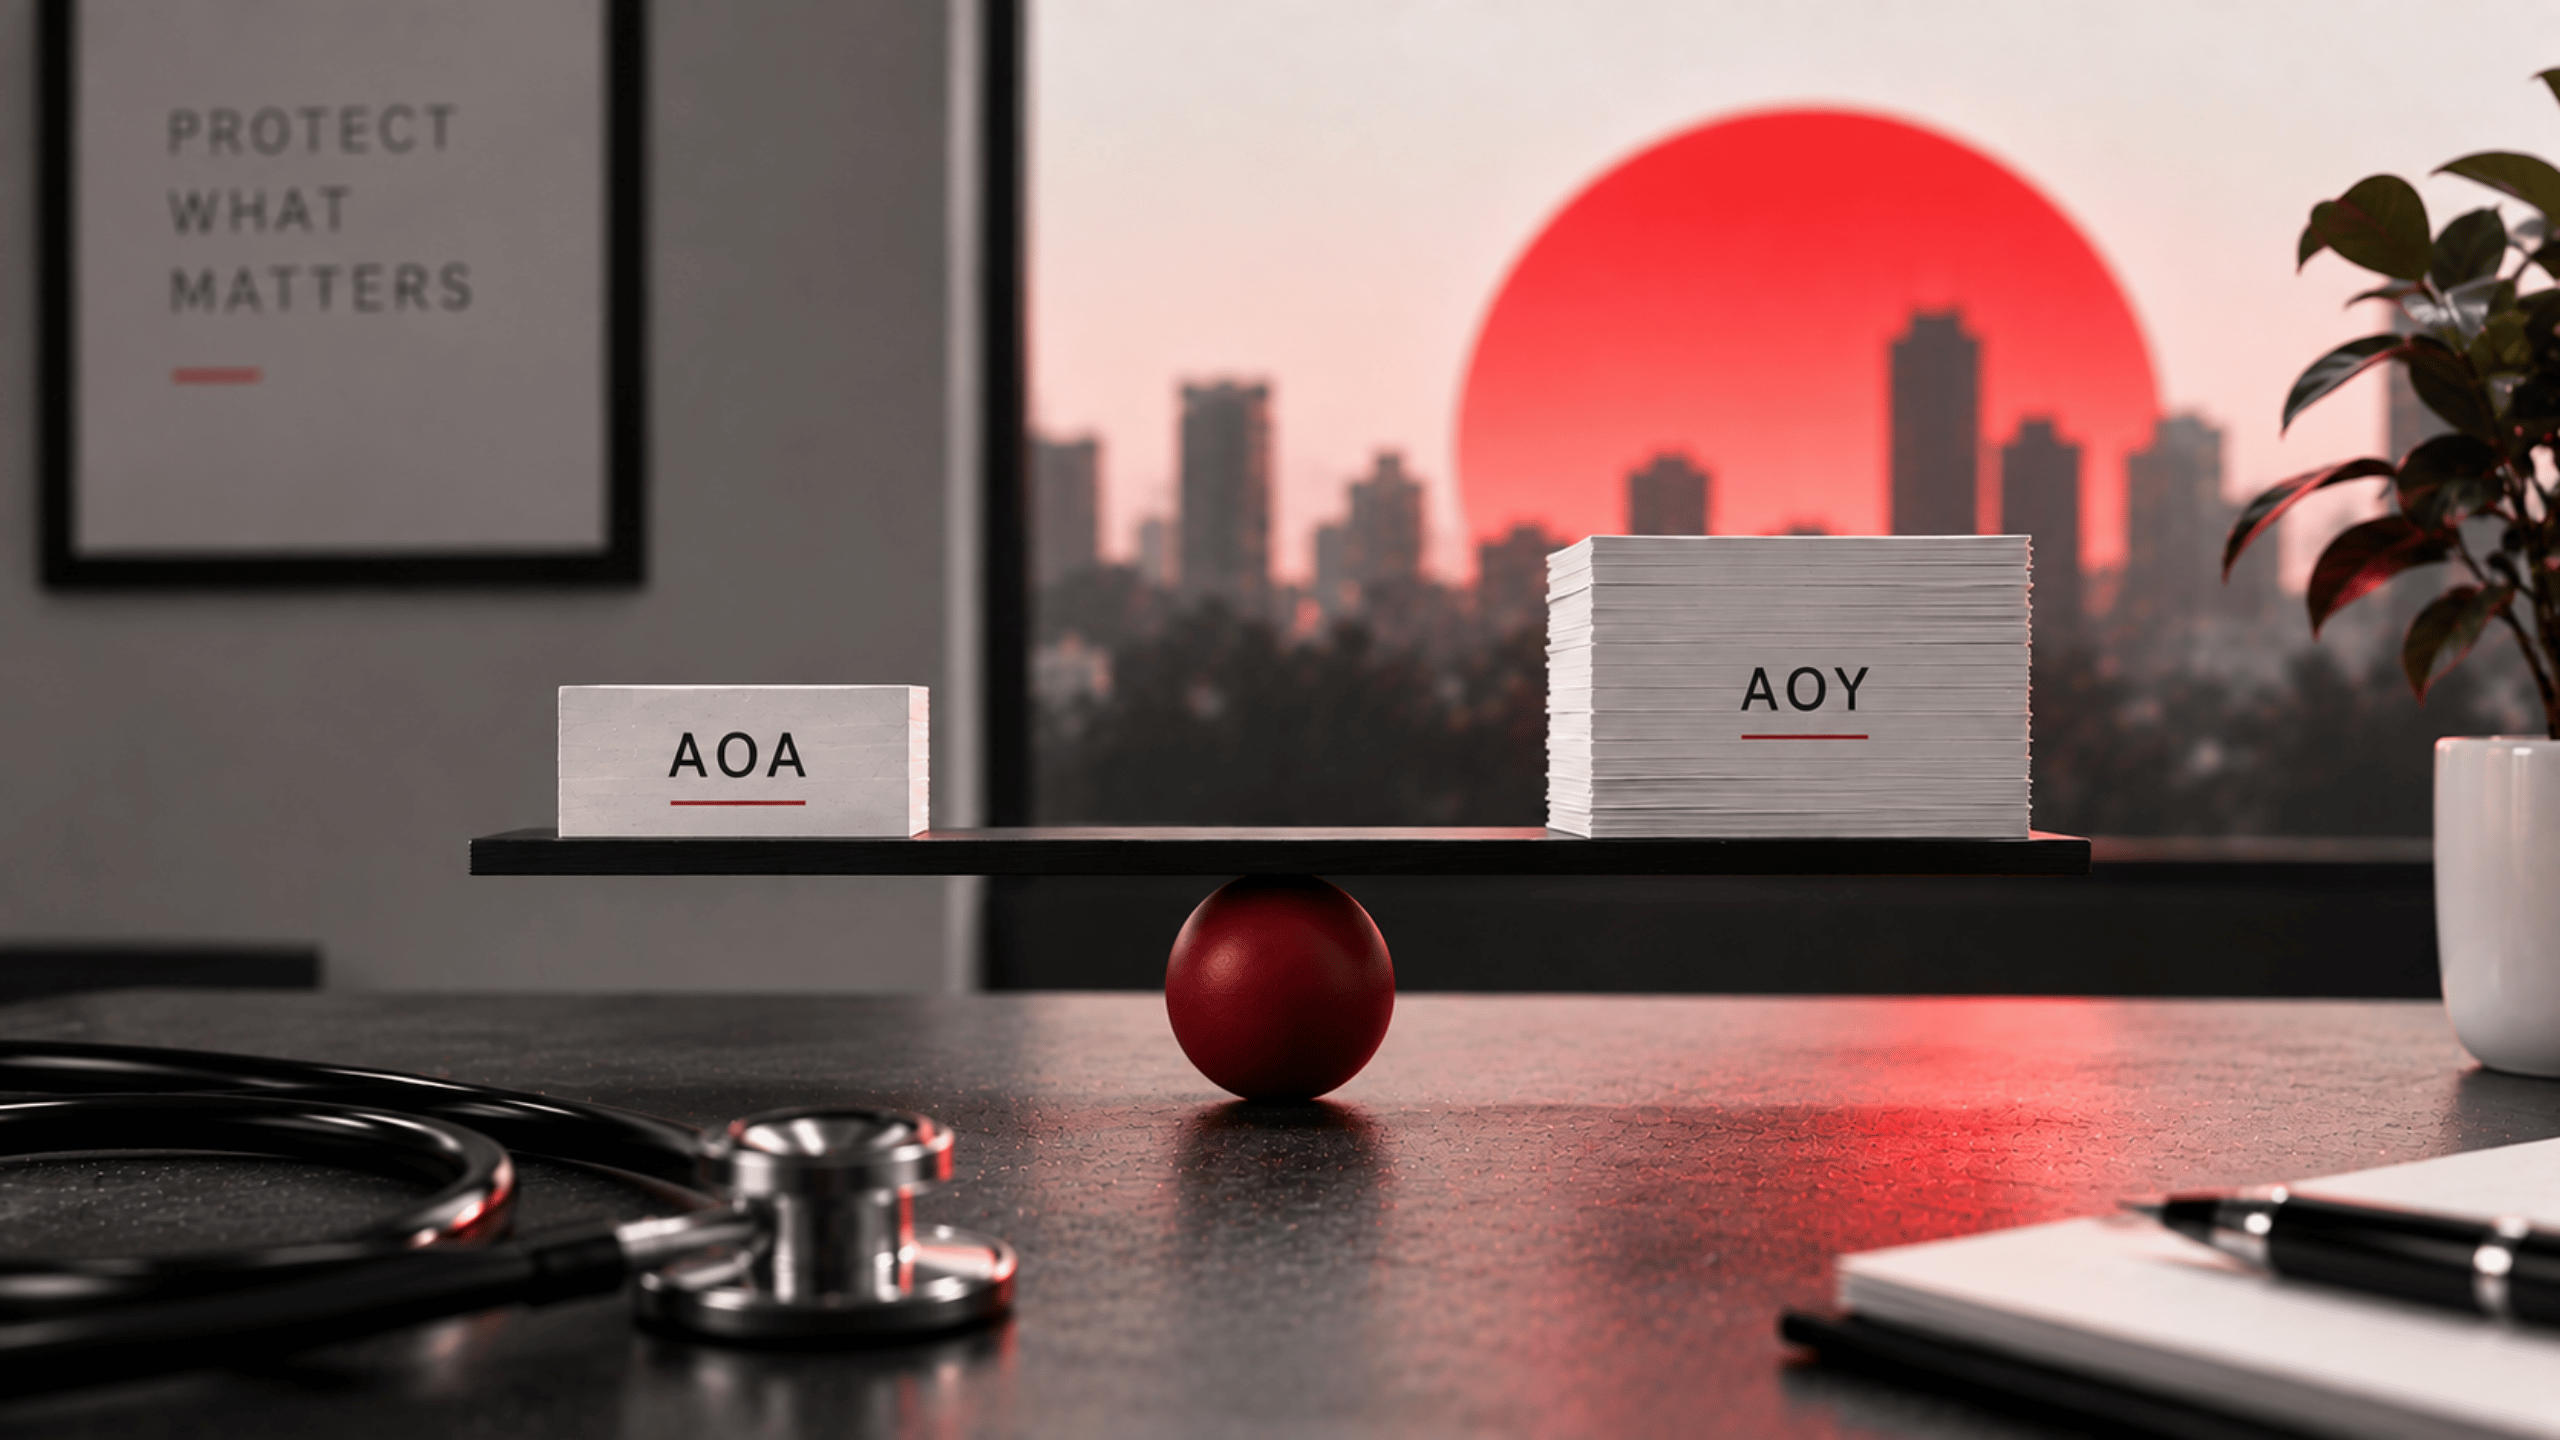
However, which policy actually responds depends entirely on a single contractual phrase that most medical practitioners never read. Understanding the real-world claims made vs occurrence policy India framework sounds like an academic exercise until a legal file lands on your desk. At that exact moment, this single clause decides everything regarding your financial survival.
Understanding Claims Made Vs Occurrence Policy India Triggers
Every professional liability contract relies on a specific policy trigger. Specifically, the trigger is the exact legal event that obligates an insurer to respond to a claim.
- Claims-made trigger: The active policy that responds is the one in force when the patient claim is first made against you in writing. However, the original treatment must fall on or after your established retroactive date.
- Occurrence trigger: The policy that responds is the one that was actively in force when the treatment or incident physically happened, regardless of when the legal claim eventually arrives.
Under a standard occurrence wording, your 2022 policy would automatically answer the 2026 complaint. Conversely, under claims-made wording, your current 2026 policy must respond. Therefore, your current policy only covers you if your retroactive date reaches all the way back to 2022 without an unbroken gap. You can review official regulatory updates on the Insurance Regulatory and Development Authority of India (IRDAI) portal to understand how policy triggers operate in Indian general insurance.
What The Indian Insurance Market Actually Writes
So which of these two insurance structures are you currently holding in your clinic? For doctors practicing across India, the market position is settled. However, it is vital to understand why this standard exists rather than simply taking it on trust.
Professional indemnity wordings issued by Indian general insurers for healthcare practitioners are written on a claims-made basis. Specifically, the contractual language remains consistent across major insurance providers. The policy responds exclusively where a formal claim is first made in writing against the insured during the active policy period. Furthermore, any clinical acts committed before the specified retroactive date are strictly excluded.
This reality is established market practice rather than a statutory legal requirement. Specifically, no regulation explicitly compels this structure. Therefore, you should treat claims-made cover as the standard market reality you will encounter. If an intermediary offers you a policy labeled as occurrence cover, read the trigger clause carefully. You can verify statutory contract principles on the official India Code repository.
Why Claims Made Vs Occurrence Policy India Dictates Doctor Behavior
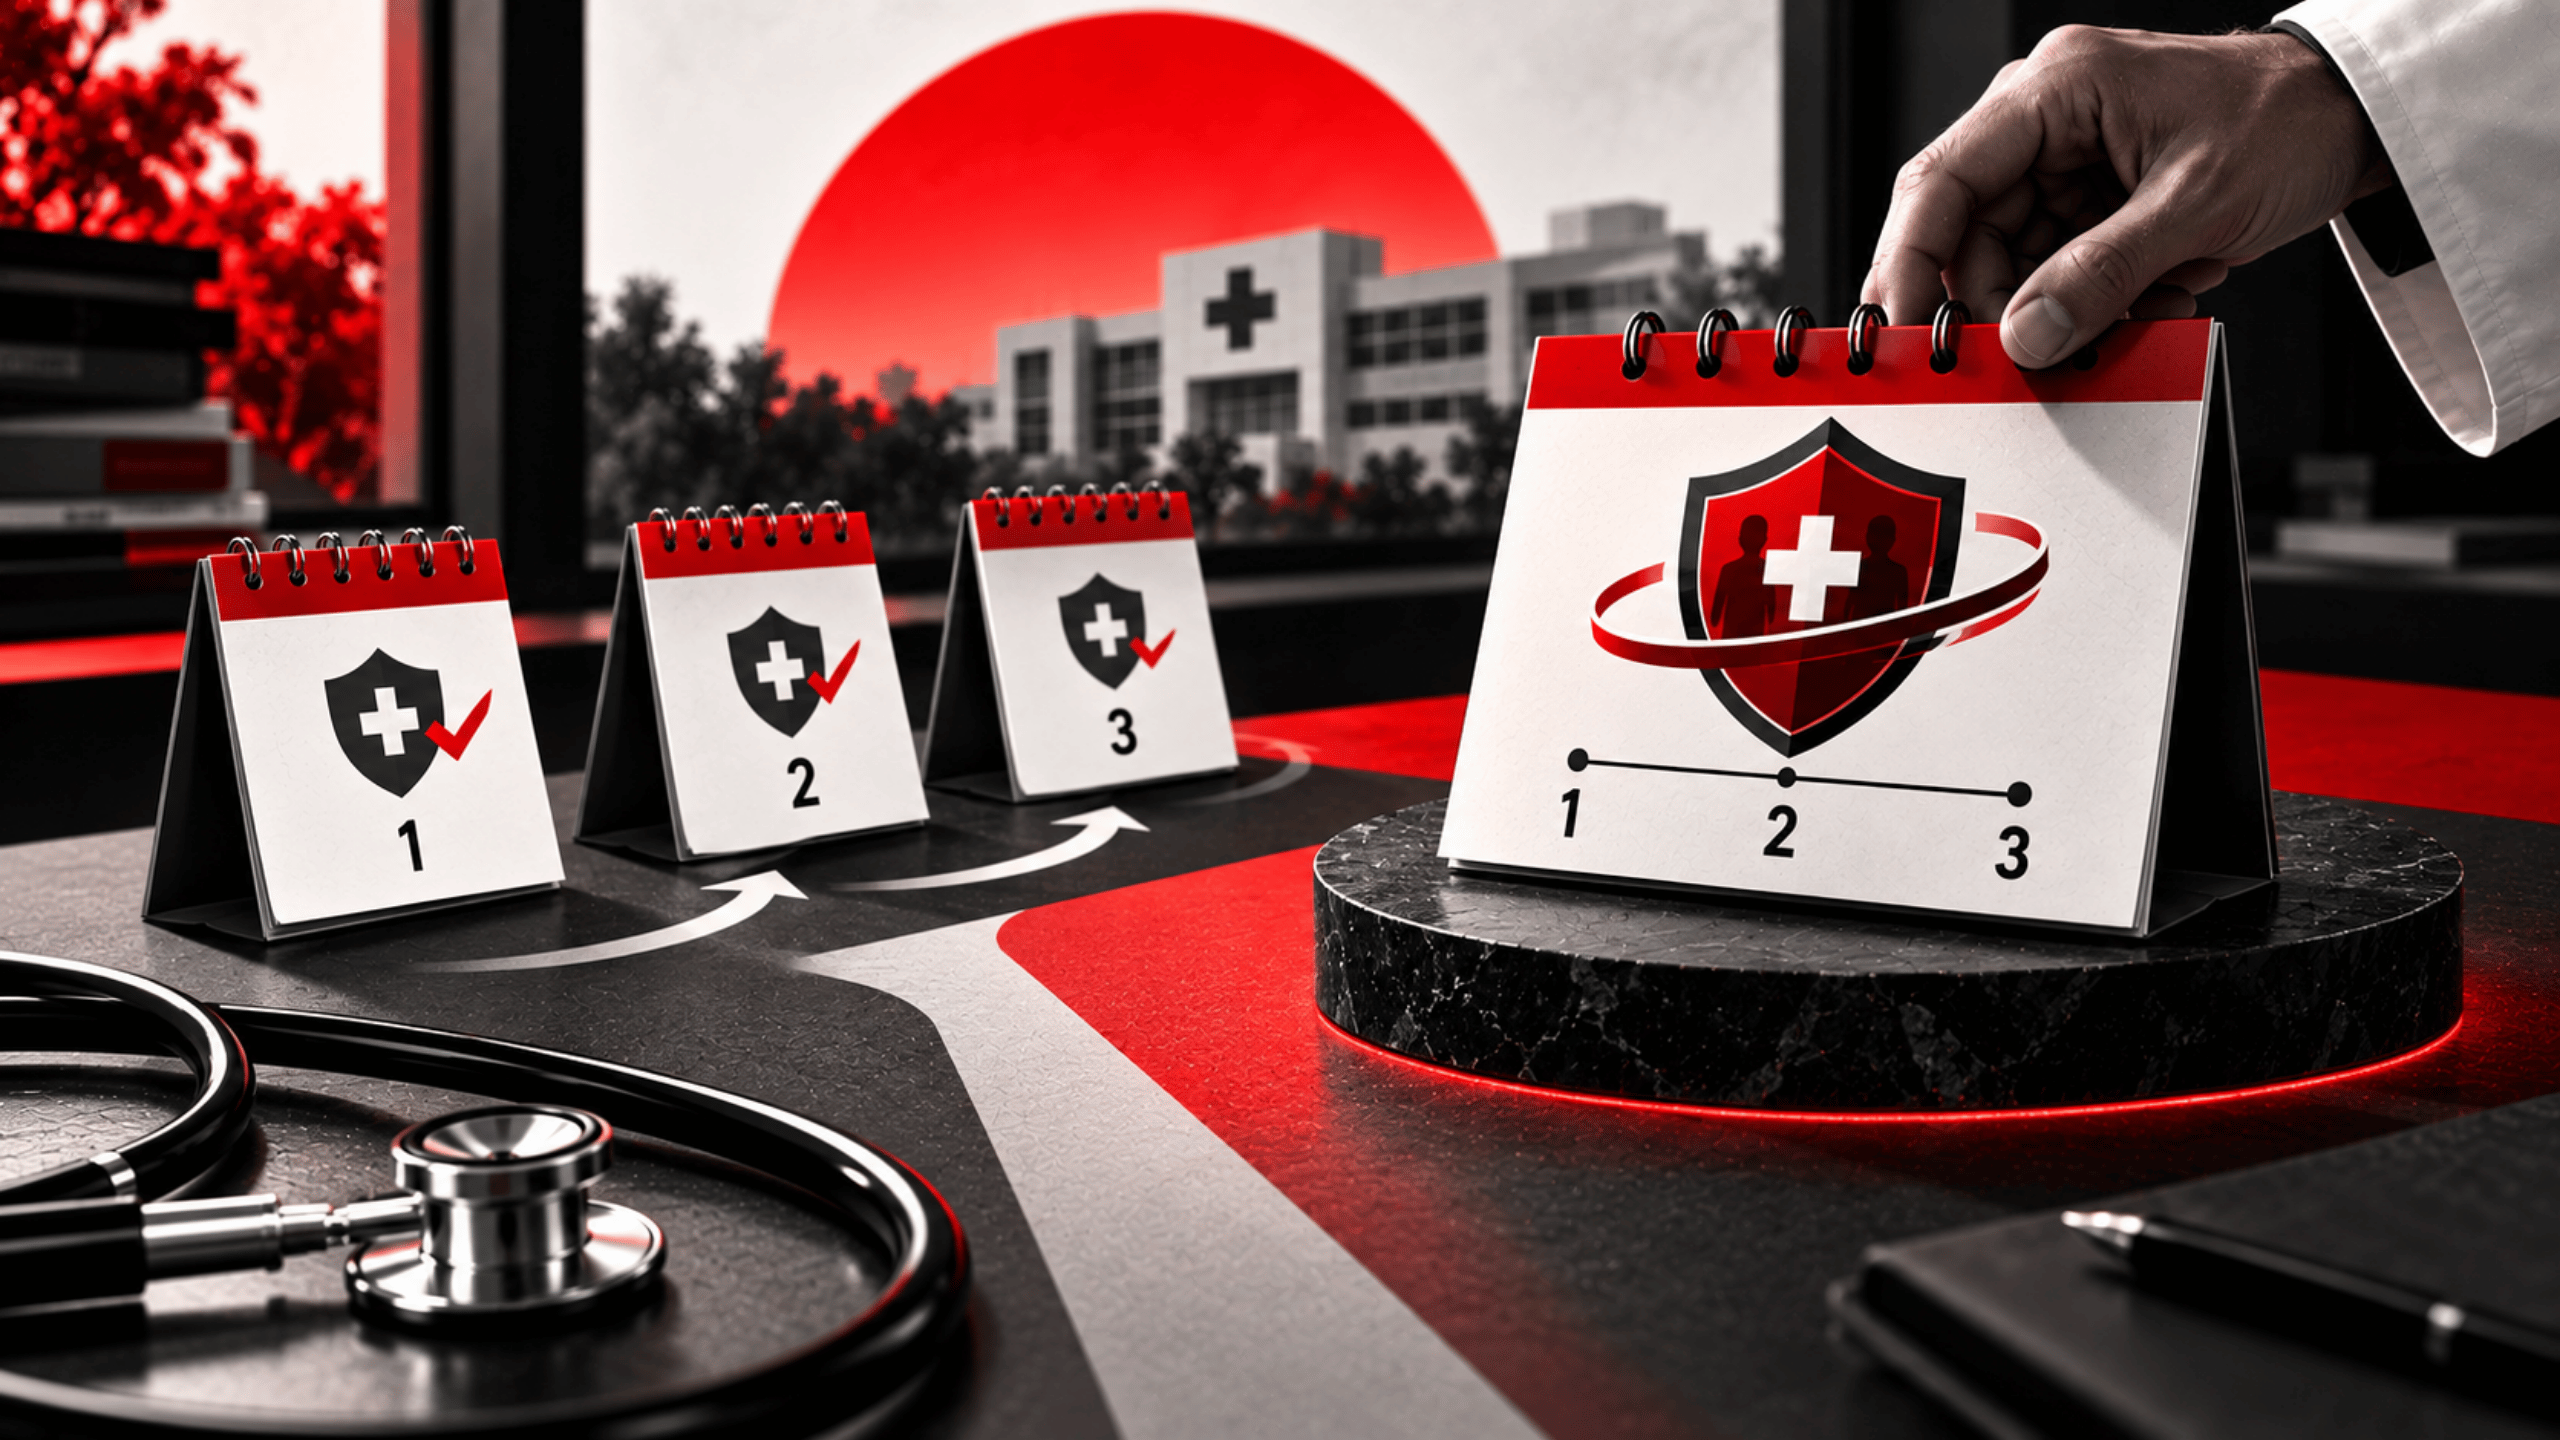
The practical weight of the claims made vs occurrence policy India distinction shows up in your daily administrative habits rather than in marketing brochures. If your policy were occurrence-based, professional insurance would function as a series of self-contained annual blocks. Consequently, buying cover in 2022 would protect your 2022 treatments forever.
However, claims-made cover does not work that way. Therefore, three essential operational habits must follow from this reality:
- Never allow a policy lapse: Coverage for past clinical work exists only while an active policy is live. Consequently, a single gap removes protection for your entire past practice, not just for the uninsured days.
- Protect your retroactive date: Your retroactive date is the anchor that reaches backward. Continuous annual renewal is what preserves this date permanently.
- Plan for practice retirement: When you stop renewing your policy, your legal ability to report claims about past treatment stops immediately.
This final point is the exact scenario doctors encounter least prepared, usually at retirement. Under occurrence cover, stopping clinical practice ends your risk exposure alongside your practice. Conversely, under claims-made cover, your legal exposure outlives your active practice while the policy does not. You can review professional conduct standards on the National Medical Commission (NMC) website to align your risk management strategy.
Reading Your Own Insurance Schedule In Two Minutes
You do not need to read fifty pages of legal fine print to establish where your coverage stands. Specifically, you can locate three critical items on your policy schedule within two minutes.
First, check the policy trigger clause. Look explicitly for language referencing a claim first made in writing during the policy period. Second, locate the retroactive date and verify that it matches the exact inception date of your very first indemnity policy. Third, check for any extended reporting provisions that apply after your policy ends.
If these three elements do not align with your expectations, contact your insurance broker immediately. Most doctors who discover an administrative discrepancy discover it in time to fix it. Conversely, those who fail to check usually read their schedule for the exact first time with a consumer court notice already in hand.
Key Takeaway For Medical Practitioners
An occurrence policy insures a single year of work. Conversely, a claims-made policy protects a continuous medical career. Consequently, your annual renewal date, rather than your initial purchase date, is what keeps your past practice safe. Fully grasping the claims made vs occurrence policy India market reality is the single best way to safeguard your financial future.
5 FAQ SECTION
What is the difference between claims-made and occurrence cover?
Claims-made responds based on when the formal claim is first made against you in writing, provided it falls after your retroactive date. Occurrence responds based on when the clinical incident occurred, regardless of when the claim arrives.
Which basis is used for doctors indemnity in India?
Professional indemnity wordings issued by Indian insurers for medical practitioners are written on a claims-made basis. This is standard market practice across the Indian insurance industry.
Is occurrence basis professional indemnity available in India?
Claims-made is what you will encounter in the Indian market. If a policy is described as occurrence-based, read the trigger clause in the policy wording carefully before relying on that description.
Why does claims-made make policy continuity so important?
Because coverage for past clinical work exists only while a policy remains live and your retroactive date reaches back continuously. A break in cover resets your retroactive date and removes past protection.
Does my old expired policy cover a claim filed today?
Generally no. Under claims-made wording, the policy in force on the day the claim is formally made against you in writing is the only policy that responds to the dispute.