Almost nobody discovers a gap in their cover while simply reading a policy.
They typically discover it on the phone directly to a broker.
They usually sit with a legal letter physically in front of them.
They desperately ask a question they falsely assumed had an obvious answer.
So rather than reading another boring clause by clause summary, here is the harsh reality.
Specifically, knowing what does professional indemnity not cover doctors prevents massive financial disasters in practice.
One: The Complaint About Work You Did Before You Were Insured
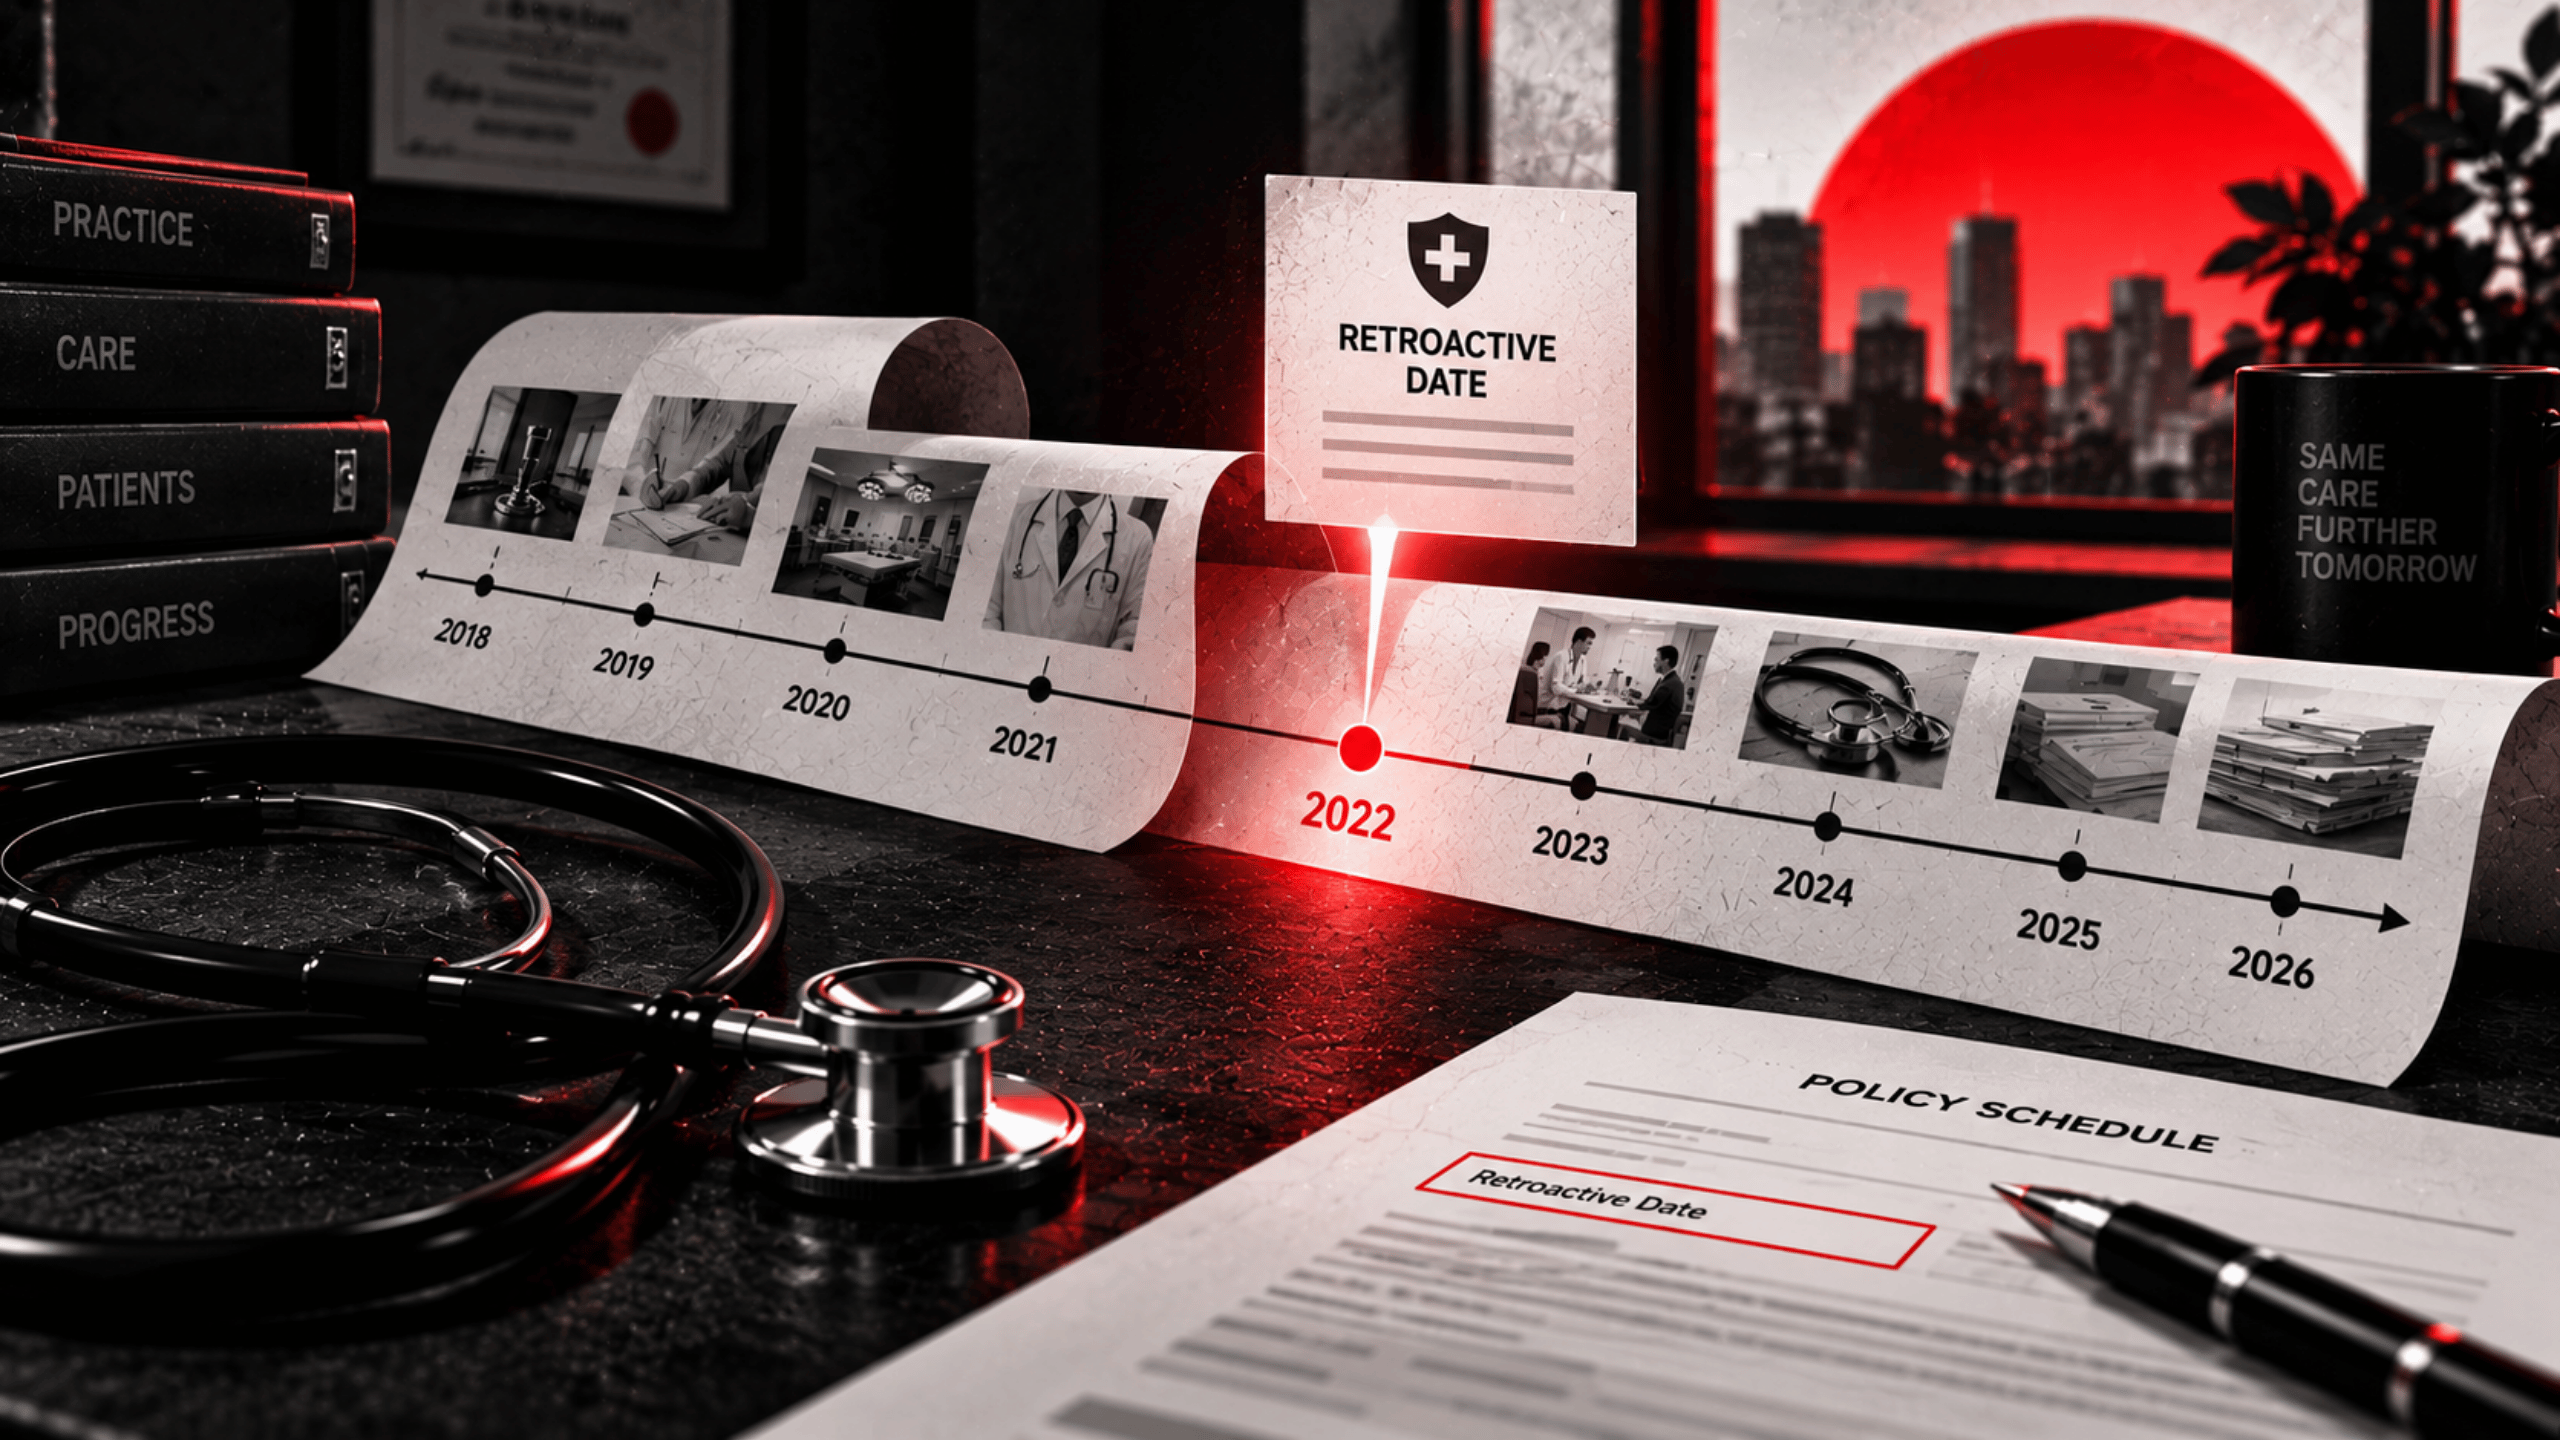
You bought your very first policy in 2021. However, the patient complaint concerns a procedure from 2019. Your retroactive date is the absolute line. Specifically, treatment before it strictly sits outside the active policy. This is absolutely not a technicality applied unkindly at claim stage. Conversely, it is printed clearly on your active schedule.
Consequently, it is the single most common reason a doctor with valid cover finds a claim officially declined. You can securely verify policy timelines directly on the Insurance Regulatory and Development Authority of India (IRDAI) portal.
Two: The Police Case
A patient’s family formally files a serious complaint. Consequently, it becomes a criminal matter rather than a simple compensation claim.
Professional indemnity is strictly built around civil liability. Specifically, it heavily covers your obligation to compensate a patient for loss strictly caused by negligence.
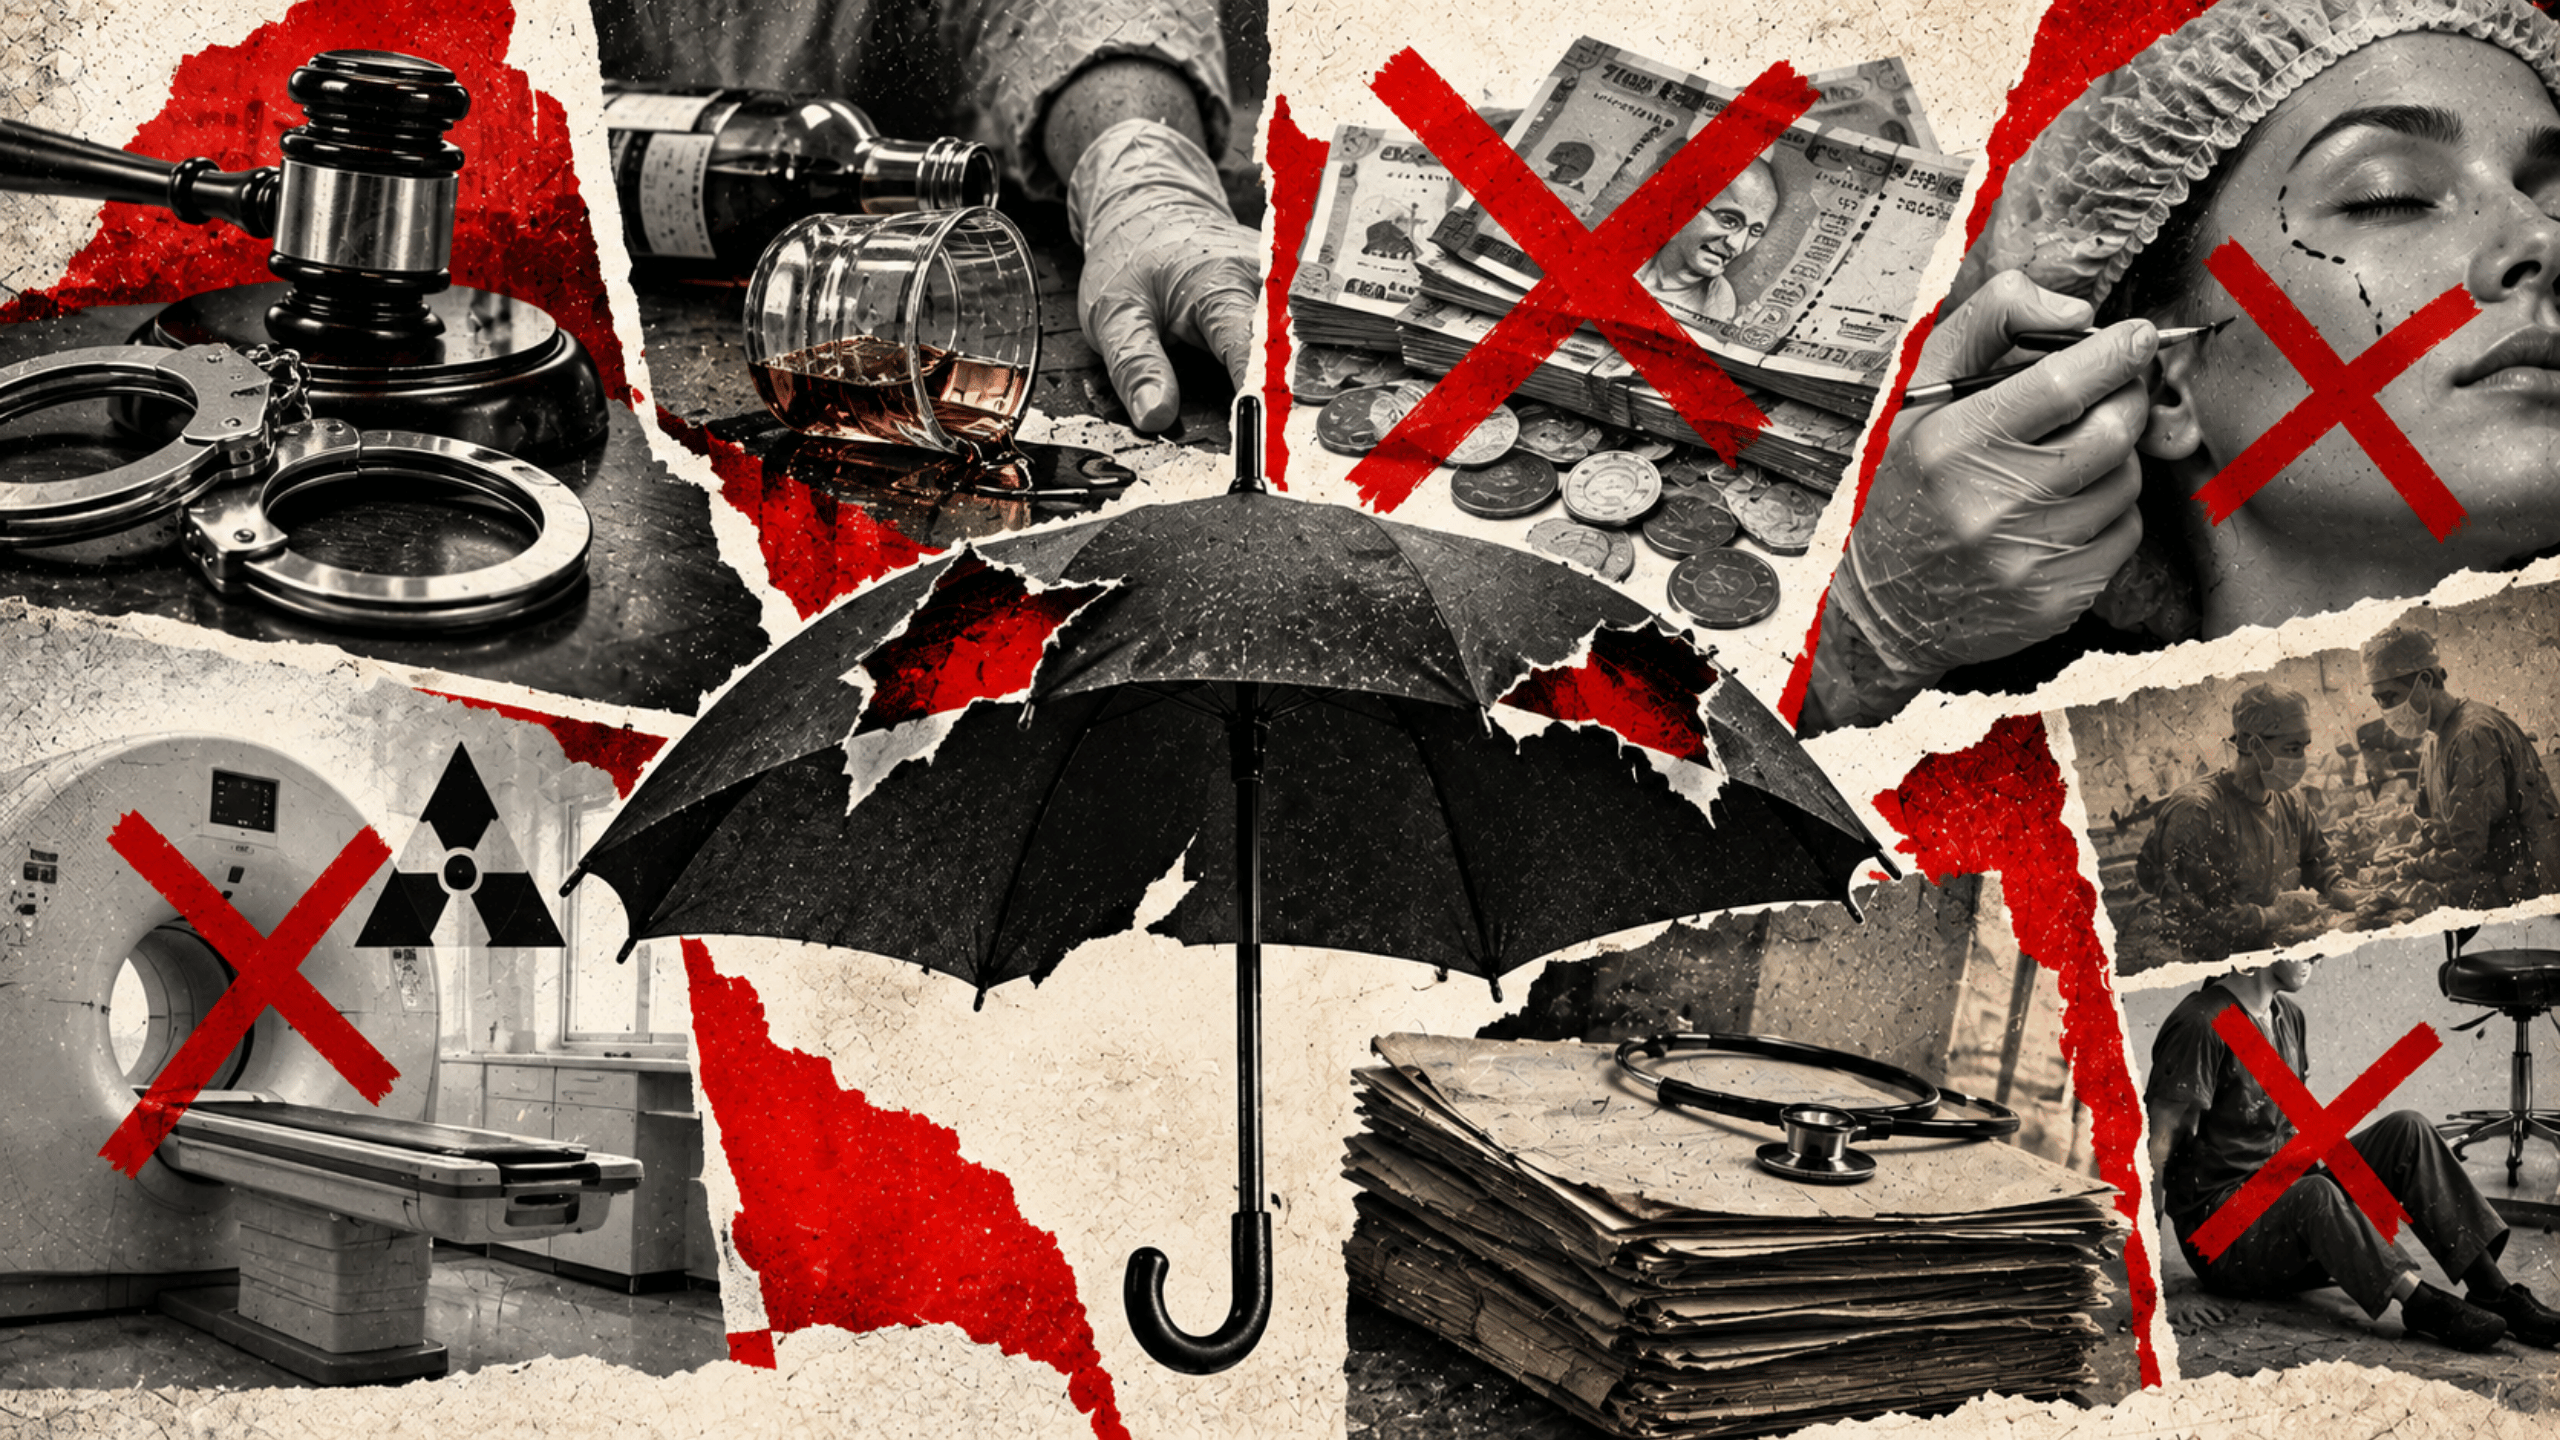
Criminal acts and conduct in strict breach of law are standard exclusions. Furthermore, fines and penalties are completely excluded separately from civil damages. That absolutely does not mean you are without options. It means the options are purely legal rather than insurance based. Therefore, the sooner you actively know which of the two you are strictly in, the better your defense goes.
Doctors lose precious time assuming an insurer will safely take over. The policy was simply never built to answer criminal charges. Therefore, clearly understanding what does professional indemnity not cover doctors saves your practice from crucial delays.
Three: The Procedure You Did Not Realise Was Carved Out
A dermatologist adds a brand new aesthetic procedure to the practice. A physician suddenly begins offering a weight management programme. Neither doctor actively tells the insurer. They mistakenly assume it is absolutely not a formal change of specialty.
Indian wordings commonly exclude certain cosmetic procedures and strict treatment for weight reduction. Furthermore, they may heavily restrict procedures performed under general anaesthesia outside a proper hospital setting.
Therefore, a quiet expansion of clinical scope is highly dangerous. Specifically, it is one of the easiest ways to end up working outside your own policy completely. Always maintain strict compliance with the National Medical Commission (NMC) professional guidelines.
Four: The Injury That Happened In Your Clinic, Not In Your Care
A visitor slips heavily in the clinic corridor. A nurse is seriously injured handling heavy medical equipment.
Neither incident involves your specific clinical judgement at all.
- Public liability: Injury to a general visitor on your premises is strictly a public liability matter.
- Employer’s liability: Injury to staff strictly arising from employment heavily falls completely outside professional indemnity.
- Property damage: Severe damage to equipment or physical premises belongs exclusively under a property policy.
- Cyber and data: A massive data breach involving patient records is usually addressed securely by separate cover.
None of those specific gaps actively mean you are completely uninsured. They simply mean the cover safely lives in a completely different policy.
Consequently, the honest answer to what does professional indemnity not cover doctors is very often not nothing, but simply somewhere else. The time to find out which policy actually applies is absolutely not the week it actually happens. You can carefully study standard liability definitions under the Indian Contract Act.
Five: The Claim That Arrives After You Stop Renewing
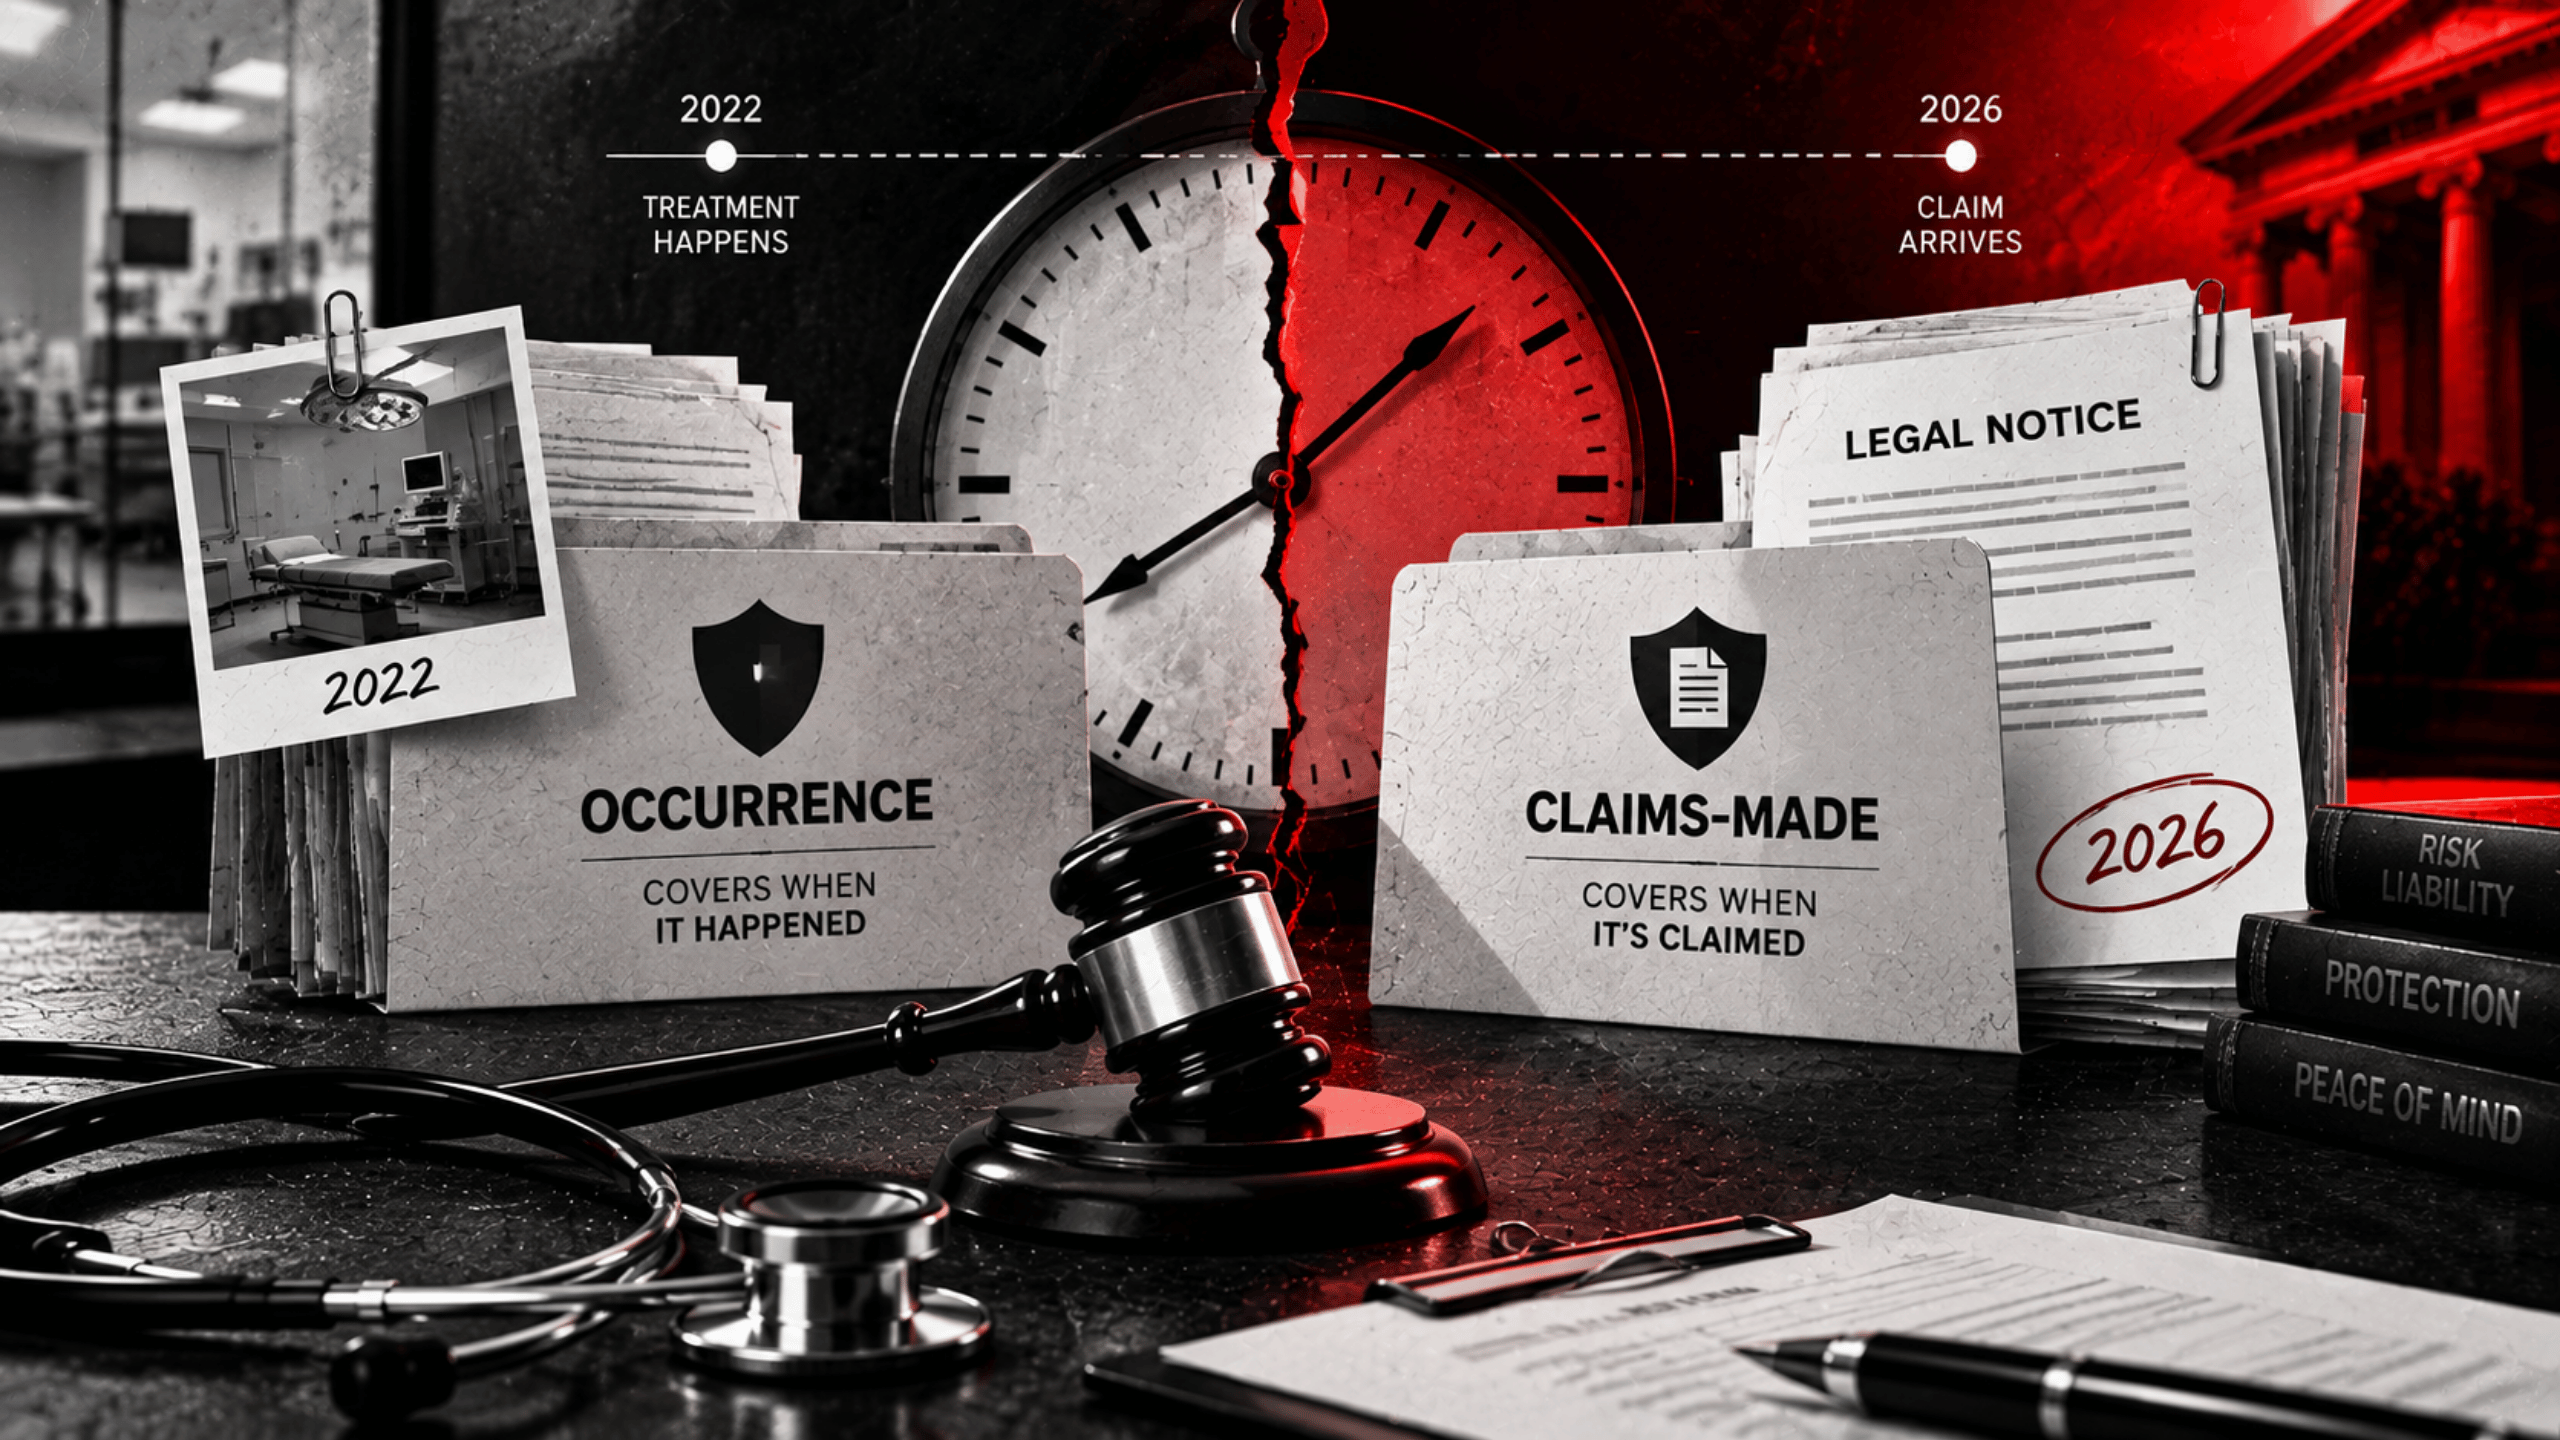
You finally retire. You completely stop renewing your insurance. However, a legal notice suddenly arrives eighteen months later regarding treatment from your exact last working year.
Claims made cover strictly responds only while a policy is completely live. Being fully insured on the exact day of the treatment is absolutely not the active test. This is a highly difficult sentence to read for the very first time with a legal notice physically in your hand.
This is the specific gap doctors meet last. Furthermore, it is the exact one that most often catches a highly careful practitioner who did everything else right.
The Takeaway On Your Career Protection
Your policy absolutely does not cover everything. Furthermore, it was simply never explicitly meant to. Spend one single evening finding out exactly which of these five directly applies to you. Find out exactly what sits safely behind the ones that do.
Do this strictly while all five are still completely hypothetical. Take this exact list to your broker immediately. Ask about each specific point clearly in writing, and strictly file the answers with your active schedule.
Ultimately, mastering exactly what does professional indemnity not cover doctors safely protects your lifelong medical legacy forever.
5 FAQ SECTION
Does professional indemnity cover criminal proceedings against a doctor?
No. Criminal acts and clinical conduct in strict breach of law are standard exclusions. Furthermore, fines and statutory penalties are explicitly excluded separately from civil damages.
Are injuries to my clinic staff or visitors safely covered?
Generally not. Staff injuries actively arising from employment strictly fall under employer’s liability. Conversely, visitor injuries usually fall completely under separate public liability policies.
What if I start performing a procedure my policy explicitly excludes?
You must absolutely tell your insurer before you actively start. A specific change in scope that is completely undisclosed can officially leave you working entirely outside your own cover.
Is a patient claim about treatment before my first policy covered?
Absolutely not, if it officially predates your printed retroactive date. Everything strictly before that specific date sits entirely outside any policy you currently hold today.
What happens to clinical claims filed after I stop practising completely?
Under claims made cover, the policy must be actively live exactly when the claim is made. Always ask your specific insurer what your wording explicitly provides right before your final policy absolutely lapses.