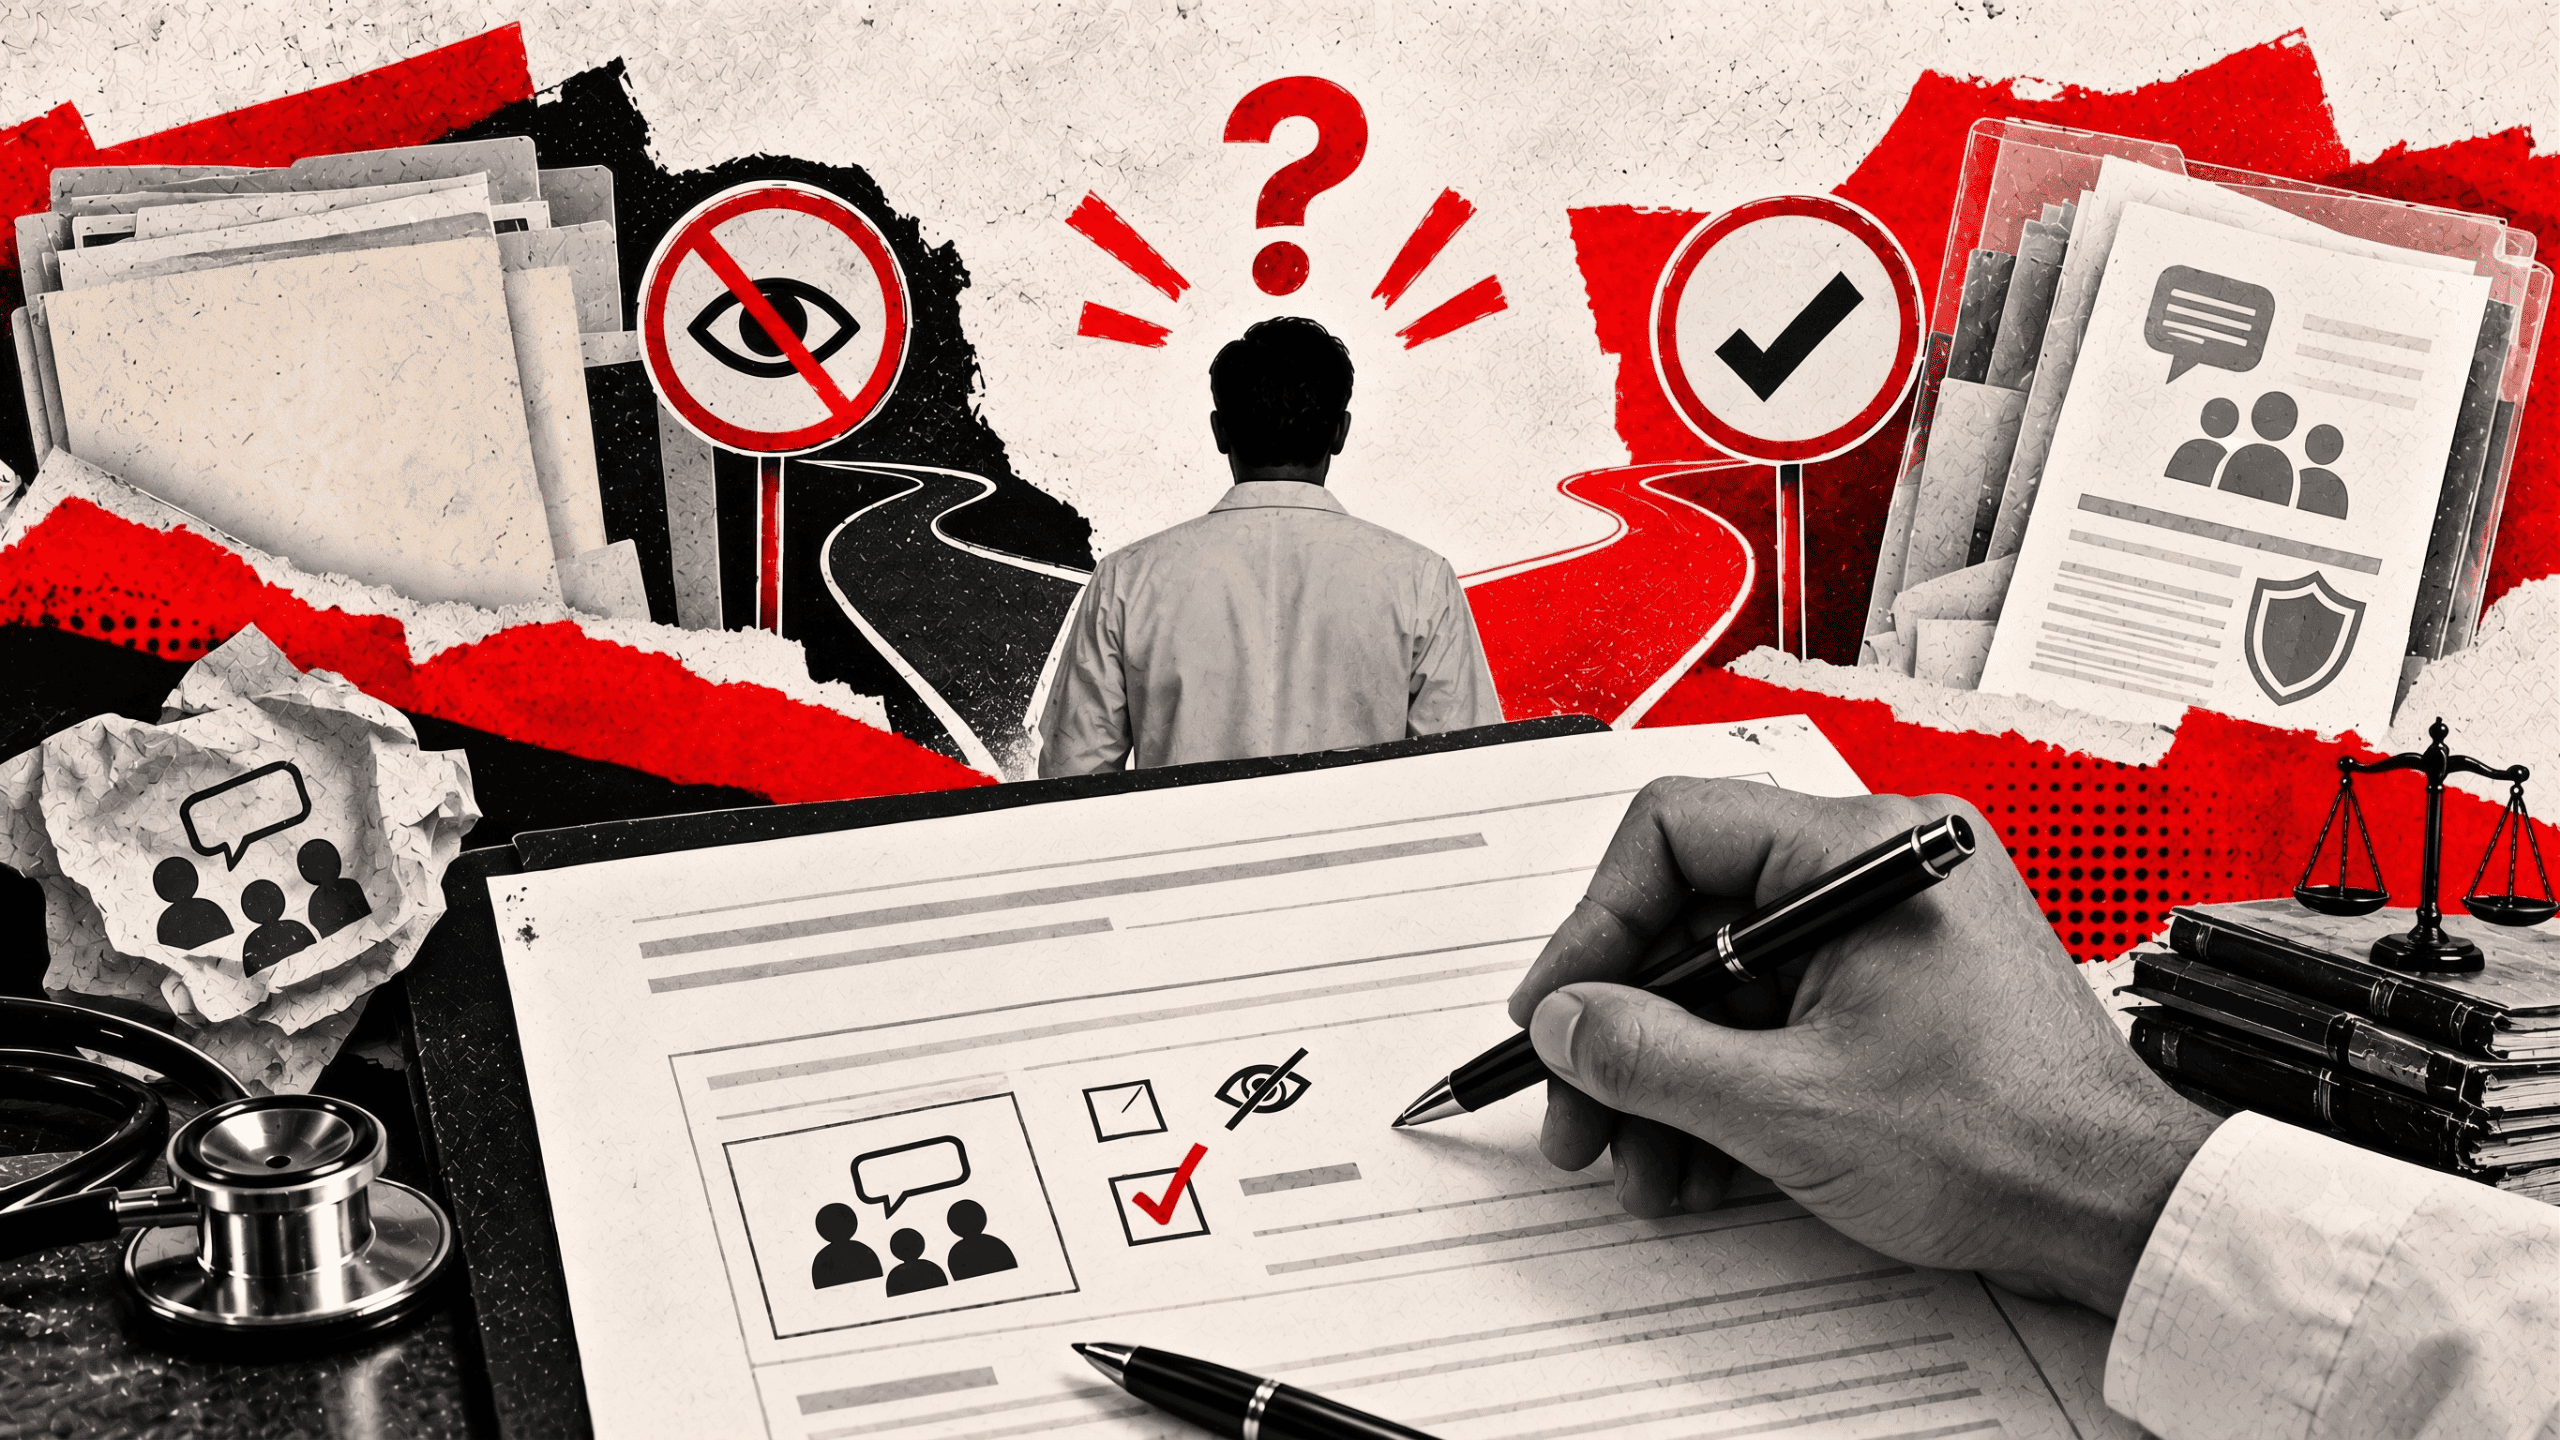
You are on the exact last page of an insurance proposal form.
It is eleven at night.
One specific box asks whether any complaint has ever been made against you.
Three years ago, a family wrote to your hospital. Specifically, they were unhappy with a clinical outcome.
You met them, and it was quickly resolved. Furthermore, nothing was ever legally filed.
Consequently, you sit there and think. Specifically, do I need to declare past complaint when buying indemnity cover for something that closed years ago?
Would anyone ever actually know?
They absolutely would. Insurers investigate liability claims properly. Therefore, the moment they look is the exact moment you need the policy to hold securely.
Why Disclosing Medical Complaints Matters
The underwriter pricing your cover has never watched you operate. Furthermore, they have never read a case sheet or spoken to your patient. All they have is your printed form.
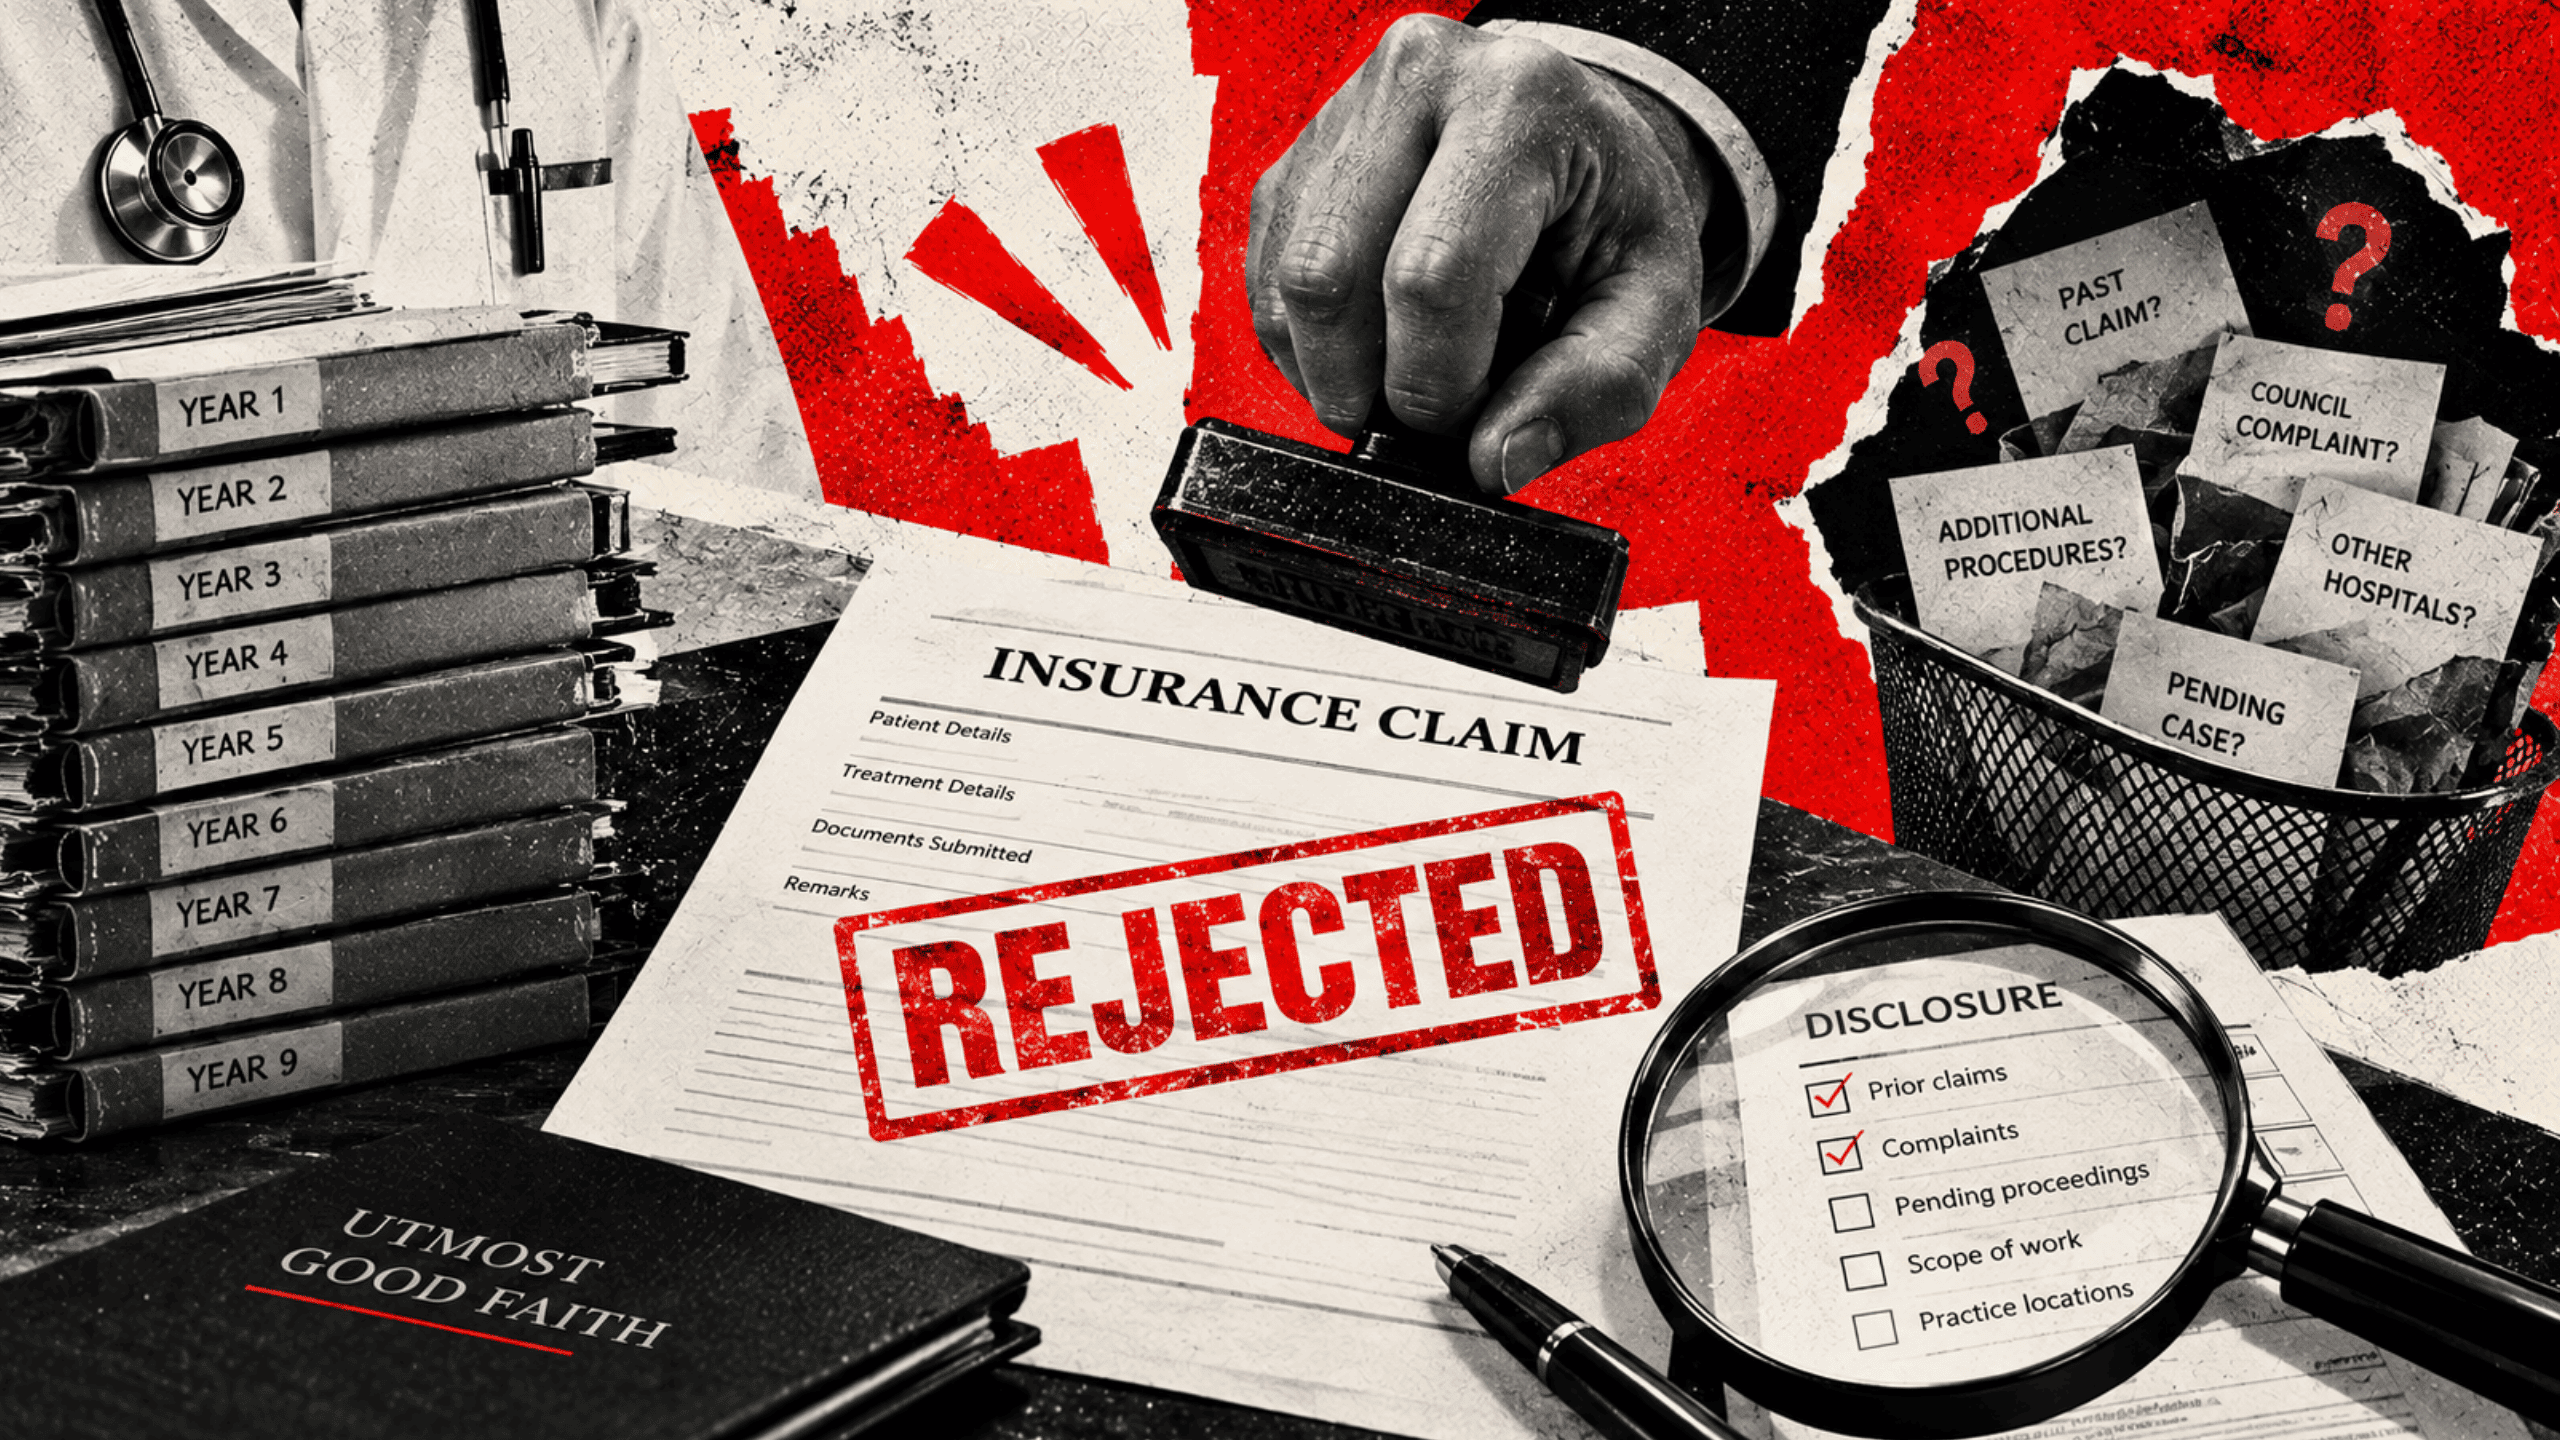
So, Indian law firmly puts the duty on you. Under utmost good faith, you must strictly disclose every material fact. This includes anything that would reasonably affect whether the insurer accepts your medical risk. Answering only what is strictly asked is not enough. You can read more about utmost good faith under the Indian Contract Act.
It is worth separating two things doctors conflate here. Declaring a complaint is not an admission that you did something clinically wrong. Conversely, it is simply a factual statement that an event happened. Therefore, the insurer is legally entitled to know this before agreeing to carry you.
What Insurers Count As A Past Complaint
Doctors read this word very narrowly. However, insurers absolutely do not.
- Written grievances: A letter or email to you, your clinic, or a hospital administrator.
- Council references: Anything reported to a State Medical Council or the National Medical Commission.
- Legal notices: From a patient advocate, whether or not a consumer case followed.
- Internal enquiries: A hospital committee examining an adverse outcome.
- Prior claims: Anything reported to a previous insurer, including matters closed without payment.
Verbal complaints sit in a grey zone. A raised voice at reception that went nowhere is generally not expected. However, anything recorded or acted on must be declared.
The True Cost Of Silence During Indemnity Insurance Renewal
Play the medical timeline forward. The exact mechanism is what makes this worth taking seriously.
Nothing happens at purchase. The policy issues easily. You renew for years, and everything looks completely fine. That is precisely the hidden problem. Consequently, the severe consequence is deferred to the one day you cannot absorb it.
When you finally file a claim, the investigator reviews hospital complaint registers. They check correspondence and prior insurer records. Therefore, the undeclared matter inevitably surfaces. The claim is quickly repudiated for material non disclosure. Furthermore, the policy may be treated as completely void from the start. Years of premium and the vital defence you were counting on disappear together. Check guidelines on IRDAI to understand policy voiding rules. This is exactly why asking do I need to declare past complaint when buying indemnity is so crucially important.
Will Declaring Past Medical Negligence Complaints Raise Your Premium?
This is the real fear behind do I need to declare past complaint when buying indemnity cover. However, it is mostly misplaced. Underwriters see medical complaints constantly. A long career with a perfectly blank record is highly unusual.
- One resolved complaint: Usually means no change at all, especially if it closed without payment.
- A paid claim: May attract a modest financial loading, much like a motor claim at renewal.
- Repeated similar complaints: Prompts questions about protocols, and sometimes triggers a specific exclusion.
- Live or serious matters: Usually results in one named exclusion, with the rest of the cover completely intact.
In most cases, declaring simply changes the paperwork. It does not change the actual price. Set that against a repudiated claim, and it stops being a difficult decision.
How To Declare Past Grievances In Five Minutes
Disclosure is a professional skill. Doing it badly can create confusion where none existed. Therefore, keep it factual, complete, and completely unemotional.
State the facts only. Include the exact date, what the grievance was, and how it closed. Provide absolutely no defensiveness and no clinical argument. Attach the closure letter if you have one. Furthermore, ask your previous insurer for a claims experience letter so nothing is missed. Finally, keep a written acknowledgement that the disclosure was formally received.
The Final Rule For Indemnity Insurance Application
If you are unsure whether something qualifies, simply put it on the form. Let the professional underwriter decide.
Nobody has ever lost a legal claim for declaring too much. Conversely, plenty have lost one for declaring too little. The massive difference is just five minutes on a form you fill in once a year. Understanding do I need to declare past complaint when buying indemnity fully protects your hard earned medical practice. For dispute resolution queries, always check with the Council for Insurance Ombudsmen.
5 FAQ SECTION
Do I need to declare verbal complaints from patients?
Only if they were recorded, escalated, or acted upon. A passing expression of dissatisfaction that went nowhere is generally not expected. If it reached a register, an email, or a committee, declare it.
Will a resolved complaint get my application rejected?
Very rarely. Insurers expect complaints across a medical career. A single resolved matter usually results in no change to terms at all. Outright rejection is strictly reserved for serious or repeated issues.
What if the complaint was against my clinic staff, not me?
Declare it. If it arose from treatment under your supervision or in your establishment, it forms part of your risk profile. Therefore, an insurer will regard it as highly material.
How far back should I check my records?
Five to seven years is the usual expectation. However, some proposal forms ask about your entire career. Read the question exactly as worded and answer that period honestly.
Does declaring a complaint mean it will be excluded from cover?
Not necessarily. Closed matters are typically noted and nothing more. An exclusion is normally applied only where a dispute is still live or a claim is reasonably foreseeable.