help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

What Counts as Already Knowing

coveryouadmin by coveryouadmin
October 12, 2026
in Blog
Reading Time: 4 mins read
0 0
0
Medical Indemnity Insurance: Protecting Doctors Against Legal Claims

Every medical decision carries responsibility. Medical indemnity insurance helps doctors navigate negligence claims and protect their professional interests.

A relative raised her voice at your reception desk in March.

Nothing was filed. Nobody wrote anything down. You bought a new policy in June without thinking about it again.

In October a notice arrives about that same patient.

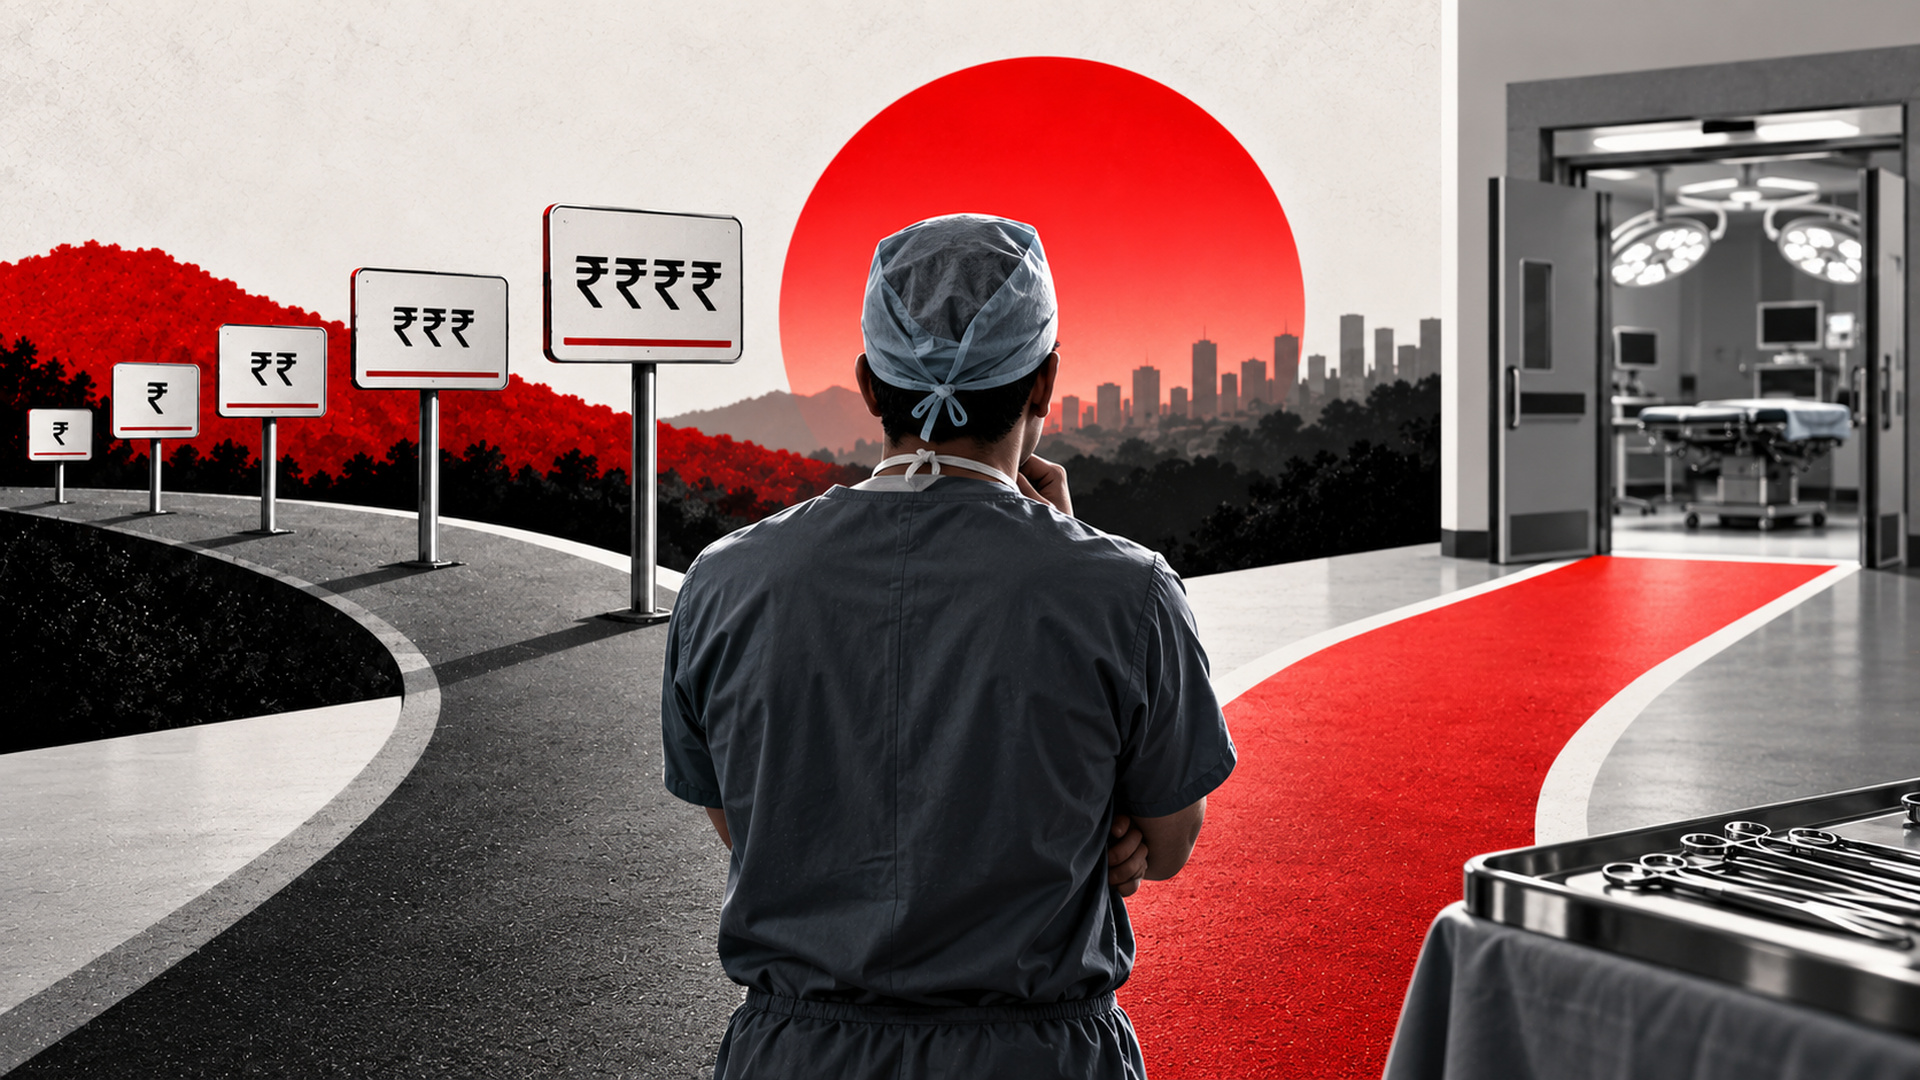
Whether your new policy answers it is decided by one clause: the prior known circumstances exclusion indemnity wordings carry, and how much it reaches back.

Two Different Clauses, Often Confused

Doctors tend to treat this as one idea. It is two, and they bite differently.

  • The retroactive date exclusion: Excludes treatment given before a date on your schedule, whether or not you knew anything. The retroactive date is a calendar test.
  • The prior known circumstances exclusion: Excludes matters you already knew about at inception, even where the treatment falls comfortably inside the policy period. This is a knowledge test.

A claim can clear the first and fail the second. That is precisely the scenario in the example above.

How Wide The Knowledge Test Goes

The second is the one worth understanding properly, because the prior known circumstances exclusion indemnity insurers apply does not turn on paperwork at all.

One Indian wording excludes claims or circumstances known to the insured prior to inception. Another, more explicitly, excludes anything arising from a circumstance that at inception may reasonably have been expected by the insured to give rise to a claim.

Read that standard carefully. It is not asking whether you expected to be sued. It is asking whether a reasonable practitioner in your position would have seen a claim coming.

Which makes an unrecorded complaint, a difficult family meeting, an internal review or an adverse outcome you discussed with a colleague all potentially relevant — regardless of whether anything formal followed.

The Gap Nobody Closes

Here is the honest weakness in these wordings, and it is worth knowing before you need it.

None of the Indian policies examined actually defines “circumstance” or “known circumstance”. The prior known circumstances exclusion indemnity policies rely on is drafted around a term that is left to argument at claim stage — when the insurer has the file, the correspondence and the benefit of hindsight, and you have a memory of a conversation in March.

That asymmetry is the reason this clause is worth managing rather than hoping about. One wording examined appears to rely on the retroactive date alone with no separate knowledge exclusion, so the position genuinely differs between products. Ask your insurer which applies to yours, in writing, before you need the answer.

The Provision That Works In Your Favour

It is not all one way, and the counterweight is in the same part of the document.

Some wordings carry the mirror image, and it is undersold. If you notify a circumstance during the policy period — giving your reasons for anticipating a claim and full particulars of dates, acts and people — a claim arising later is treated as having been made at the time you reported it.

That locks the matter into the policy that was live when you first saw trouble, instead of leaving it to be argued about under the next one. Not every Indian doctors’ wording has this extension, so check whether yours does.

What To Do This Month

  • Report circumstances, not just claims: Anything you would mention to a colleague as “this might come back” belongs in an email to your insurer.
  • Do it in writing: And keep the acknowledgement with your schedule.
  • Disclose at every renewal: Renewal is a fresh proposal, not an administrative click. Undeclared matters are how valid policies fail.
  • Ask whether your wording has the extension: Circumstance notification is a real benefit, and it is not universal.

The Takeaway

The prior known circumstances exclusion indemnity insurers apply is not about bad faith. It is about the date you first had reason to worry.

Report the worry when you have it, and the date stops being something to argue about later.

Frequently Asked Questions

What is a prior known circumstance?

A fact or situation known to you before the policy incepted that could reasonably be expected to lead to a claim. Wordings exclude claims arising from such circumstances even where the treatment falls inside the policy period.

Is ‘known circumstance’ defined in Indian policies?

In the wordings examined, no. The term is left undefined, which is why it is often argued at claim stage. One wording supplies an objective standard of what may reasonably have been expected.

Is this the same as the retroactive date exclusion?

No. The retroactive date is a calendar test about when treatment happened. The known circumstances exclusion is a knowledge test about what you were aware of at inception.

Does an informal complaint count?

It can. If a reasonable practitioner would have seen a possible claim, it may qualify even if nothing was filed. Reporting it removes the argument.

What is circumstance notification?

A provision in some wordings allowing you to report a situation that may give rise to a claim. A later claim is then treated as made when you reported it, locking it into that policy.

Does every Indian doctors’ policy have that provision?

No. It was found in some wordings and not in others, so check yours specifically with the insurer.
Tags: circumstance notification clauseclaims made policy doctorsdisclosure insurance Indiadoctor liability insurancedoctor risk protectionhealthcare risk managementinsurance non disclosureknown circumstance insurancemedical indemnity claim rejectedmedical malpractice cover Indiapolicy wording doctorsprior known circumstances exclusion indemnityprofessional indemnity exclusions Indiaprofessional liability Indiaretroactive date exclusion
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

One Crore or Fifty Lakh?

Next Post

The Procedure You Never Declared

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Clock beside a pending medical indemnity insurance claim file, illustrating delays in claim review and settlement.
Blog

How Long Does a Claim Actually Take?

October 12, 2026
Doctor reviewing a rejected medical indemnity insurance claim alongside policy documents, exclusions and legal considerations.
Blog

Your Claim Was Rejected. Now What?

October 12, 2026
Doctor evaluating different medical specialties alongside a professional indemnity insurance checklist.
Blog

Choosing a Sum Insured by Specialty

October 12, 2026
Medical Indemnity Insurance: Why Claims Get Rejected
Blog

The Procedure You Never Declared

October 12, 2026
₹50 lakh vs ₹1 crore hospital indemnity insurance coverage comparison in India.
Blog

One Crore or Fifty Lakh?

September 29, 2026
Hospital indemnity insurance cost in India illustrated through varying financial risk levels and clinical exposure
Blog

How Much Cover Is Enough for a Surgeon?

September 29, 2026
Next Post
Medical Indemnity Insurance: Why Claims Get Rejected

The Procedure You Never Declared

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • How Long Does a Claim Actually Take?
  • Your Claim Was Rejected. Now What?
  • Choosing a Sum Insured by Specialty
  • The Procedure You Never Declared
  • What Counts as Already Knowing

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In