help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

One Crore or Fifty Lakh?

coveryouadmin by coveryouadmin
September 29, 2026
in Blog
Reading Time: 3 mins read
0 0
0
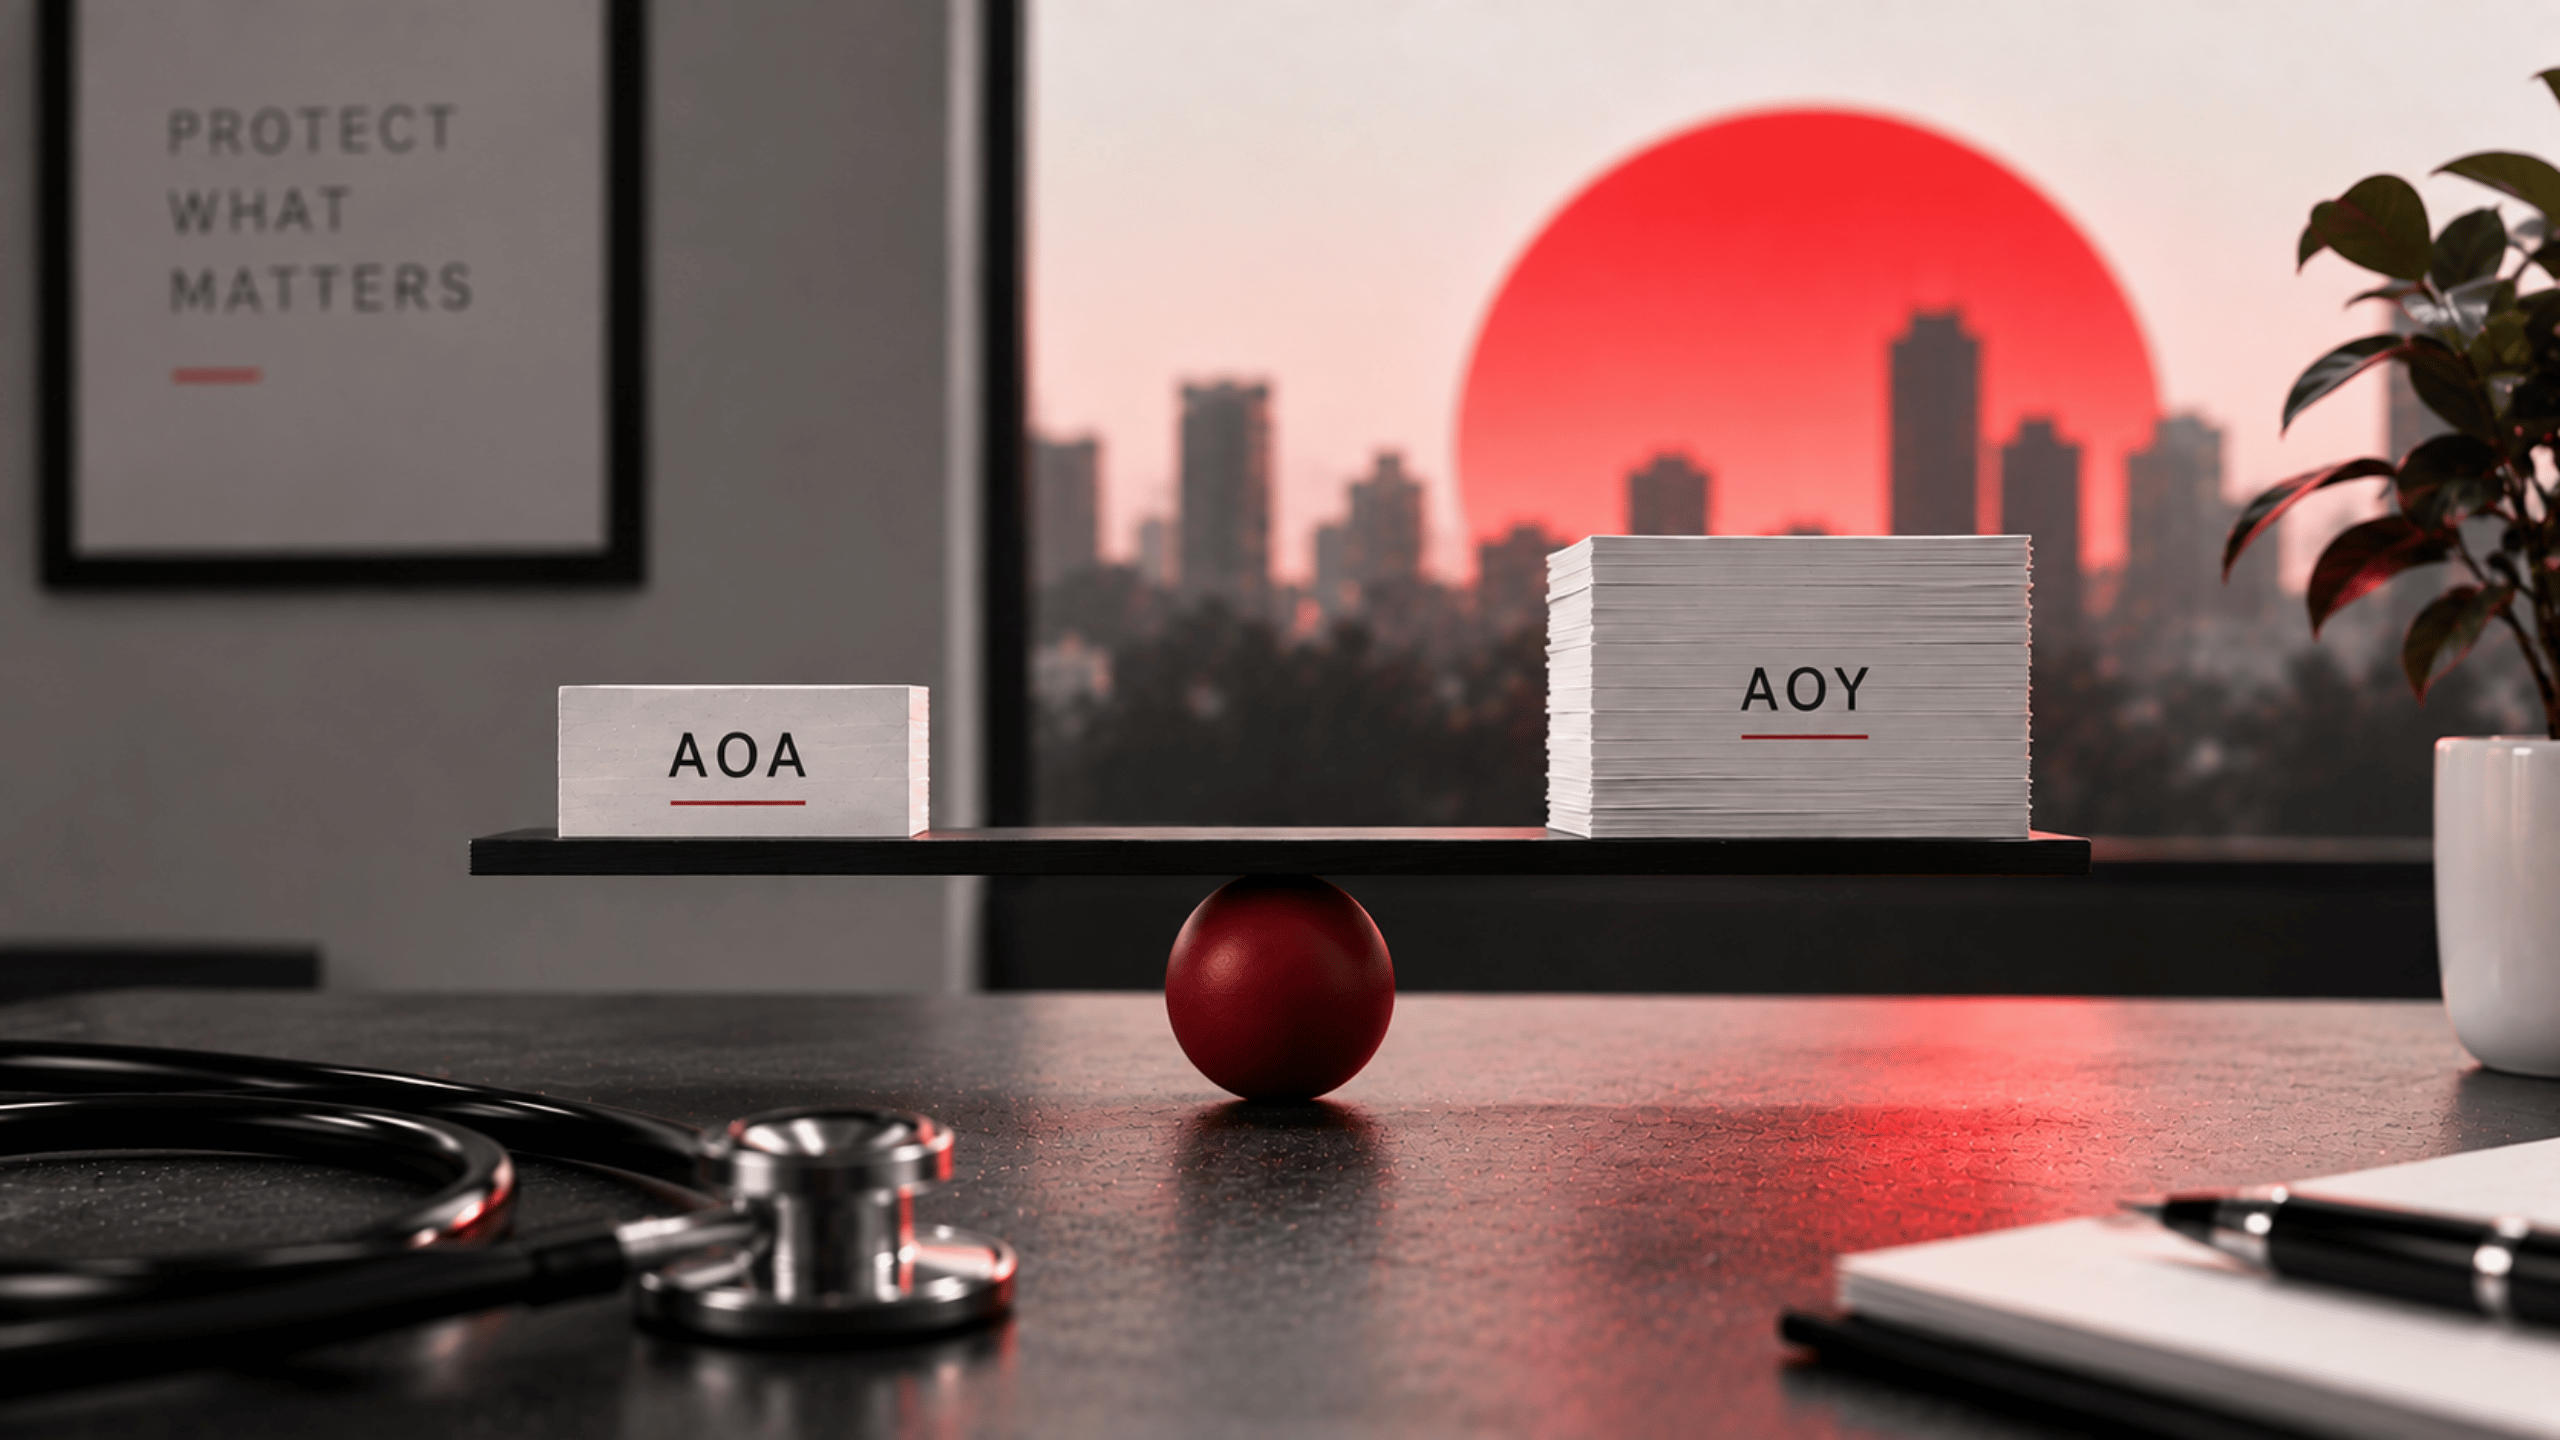
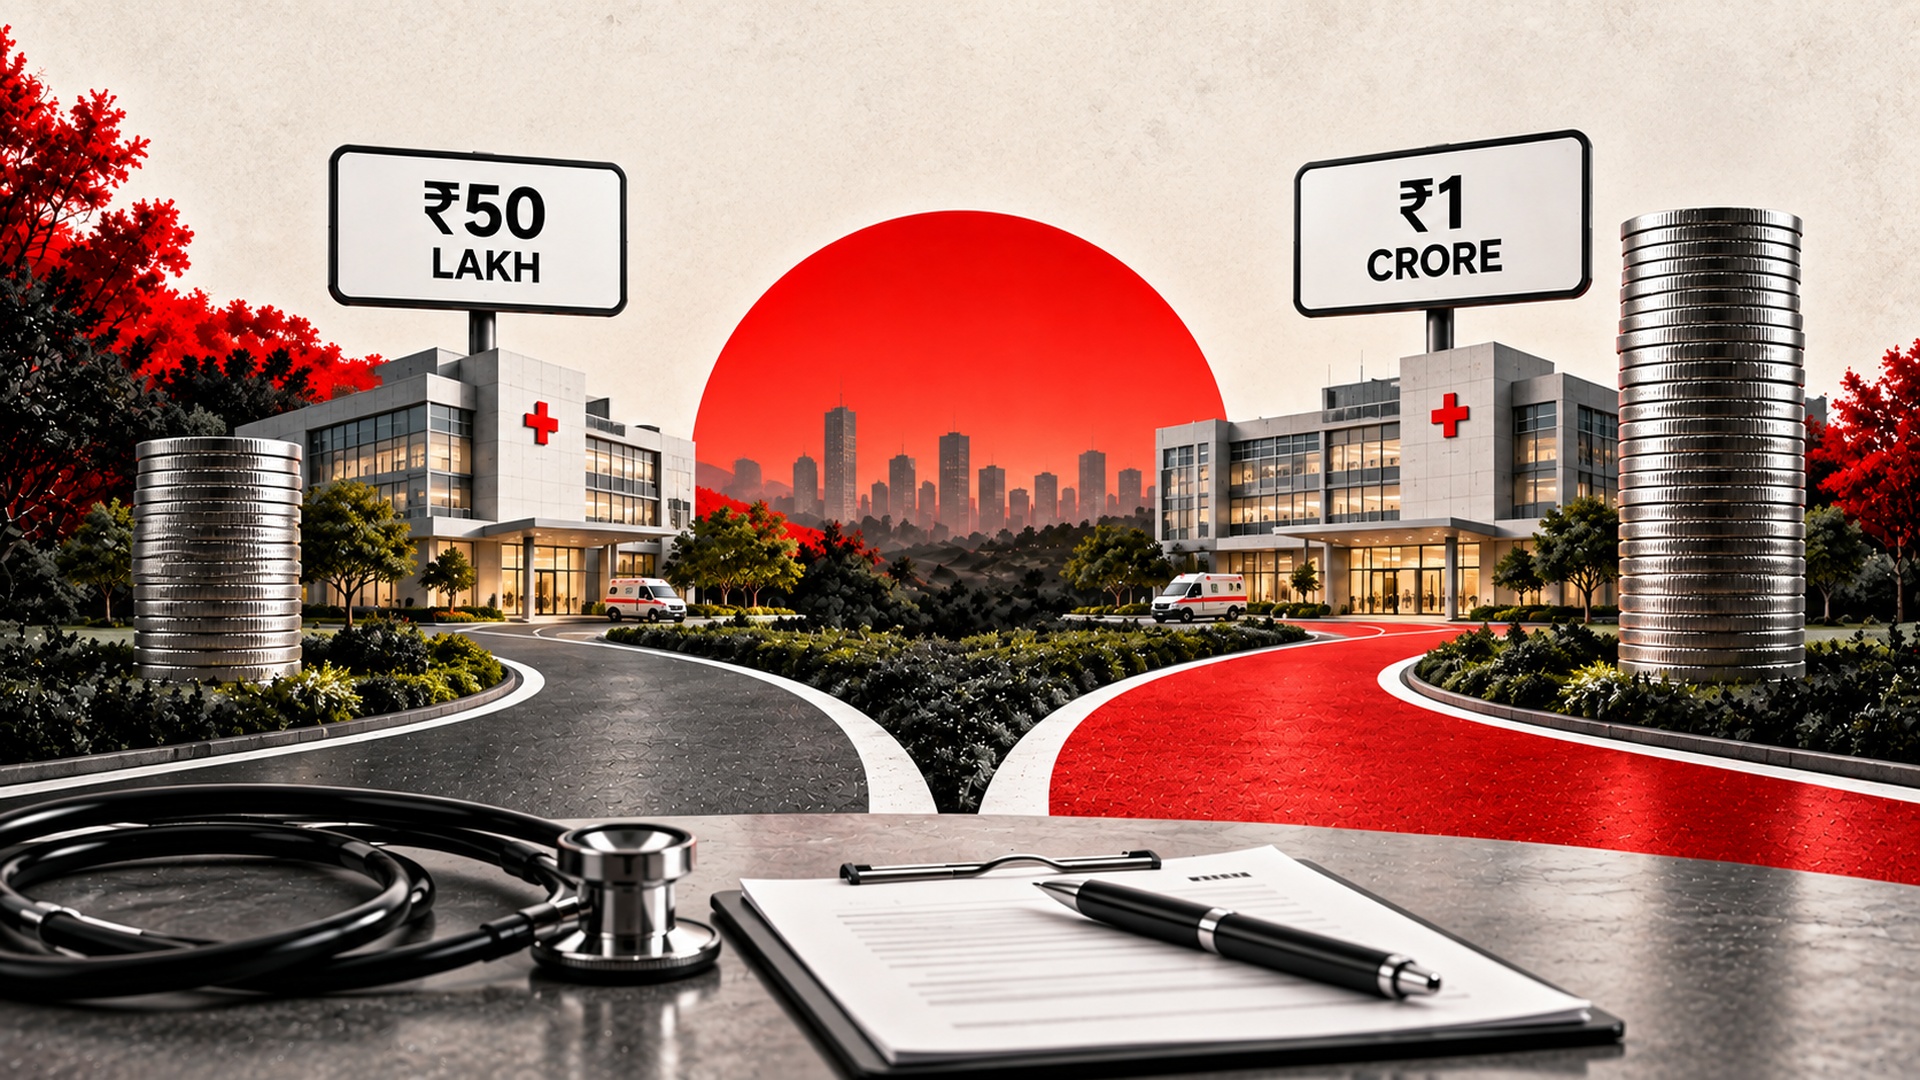
₹50 lakh vs ₹1 crore hospital indemnity insurance coverage comparison in India.

50 lakh or ₹1 crore? The right hospital indemnity structure depends on the hospital’s actual exposure, not the headline figure alone.

Two quotes, side by side.

Same insurer, same specialty, same excess. One says fifty lakh. One says a crore.

The premium difference is smaller than you expected, which somehow makes the decision harder rather than easier.

So here is 1 crore vs 50 lakh indemnity cover doctor by doctor — what actually separates them, and what the premium gap is not telling you.

Start With What The Number Is Not

Neither figure is a pot of compensation waiting for a patient. In Indian doctors’ wordings, defence costs are paid from inside the limit and reduce it as they are spent.

So the working figure is always lower than the headline. A defence running four or five years through a consumer commission consumes part of the cover before anyone has decided whether you were negligent at all.

On a fifty lakh limit that erosion is proportionally heavier. It is the first real argument for the larger number, and it has nothing to do with expecting a catastrophic award — only with how long Indian matters take.

Then Look At The Shape, Not Just The Size

Most people comparing 1 crore vs 50 lakh indemnity cover doctor quotations are comparing one number against another. There are really four.

A crore at a 1:4 ratio caps any single claim at twenty-five lakh. Fifty lakh at 1:1 lets one claim draw the whole fifty.

Read that twice, because it inverts the intuition. For a doctor whose realistic exposure is one serious claim rather than several, the smaller policy with the better ratio can be the stronger one. Whichever you choose, the AOA and AOY figures belong on the quotation in writing, not discovered later on the schedule.

Where 1 Crore vs 50 Lakh Indemnity Cover Doctor Choices Actually Diverge

The honest differentiators are few, and none of them are marketing.

  • Severity of your worst case: Not your average matter. The single outcome that would follow you.
  • How long you will be exposed: Every year you renew adds another year of treated patients who can still bring a claim.
  • Length of a likely defence: Consumer matters commonly run years, and cost runs with them.
  • Contractual minimums: Some empanelment agreements specify a figure. Check before you compare.
  • Whether you carry the shortfall: Anything above the limit is personal, so the question is what you could absorb.
  • Room to move later: Limits are usually revisited at renewal, subject to underwriting.

What The Premium Gap Is Really Telling You

Which leaves the thing that made the decision feel hard in the first place.

A small difference in premium between the two is not evidence that the risk is small. Liability pricing is not linear: the probability of a claim reaching the upper layer is low, so the extra cover is comparatively cheap to add.

That is an argument for buying the higher limit if your exposure justifies it, not an argument that the limit hardly matters. Cheap cover you never need costs a little. Missing cover you do need costs everything above the limit, out of your own savings, for as long as it takes to pay.

One caveat worth stating plainly: a larger sum insured does not make a claim more likely to be paid. Whether a claim is payable is decided by the wording, the exclusions and what you disclosed. The limit only decides how much is there once it is.

The Takeaway

1 crore vs 50 lakh indemnity cover doctor decisions are settled by two things: what your worst single claim would cost, and how much of the limit the defence will eat before you get there.

Pick the number for the outcome you could not absorb. Then check the ratio, because the shape decides what the number is worth.

Frequently Asked Questions

Is one crore of indemnity cover better than fifty lakh?

Not automatically. A higher aggregate with a narrow per-claim ratio can pay less on a single serious claim than a lower aggregate at 1:1. Compare the AOA and AOY figures, not just the headline.

Why is the premium difference so small?

Liability premium does not rise in proportion to the limit, because the likelihood of a claim reaching the upper layer is low. That makes additional cover comparatively inexpensive.

Do defence costs come out of either limit?

In the Indian doctors’ wordings examined, yes. Defence spending reduces the limit, which affects the smaller sum insured proportionally more.

What happens if a claim exceeds my limit?

Anything above the limit is your personal liability. That is the exposure the choice of sum insured is really about.

Can I increase my limit later?

Usually at renewal, subject to underwriting acceptance. Discuss it before the renewal date rather than after the schedule is issued.

Does a bigger sum insured make a claim more likely to be paid?

No. Whether a claim is payable turns on the wording, the exclusions and disclosure. The limit only decides how much is available once it is.
Tags: 1 crore vs 50 lakh indemnity cover doctorAOA AOY ratiodefence costs sum insureddoctor insurance premiumdoctor liability insurancedoctor risk protectionhealthcare risk managementindemnity cover selectionindemnity sum insured comparisoninsurance limit of indemnitymedical malpractice cover Indiamedical negligence compensationmedico legal costprofessional indemnity limits Indiaprofessional liability doctors
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

How Much Cover Is Enough for a Surgeon?

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Hospital indemnity insurance cost in India illustrated through varying financial risk levels and clinical exposure
Blog

How Much Cover Is Enough for a Surgeon?

September 29, 2026
Doctor facing legal documents, scales of justice and a court setting representing a professional indemnity insurance claim.
Blog

Defence Costs: Inside or On Top?

September 21, 2026
Five Moments You Assume You Are Covered
Blog

Five Moments You Assume You Are Covered

September 17, 2026
The Exclusions Page, in Plain Language
Blog

The Exclusions Page, in Plain Language

September 18, 2026
Run-Off Cover: After You Stop Practising
Blog

You Retire. The Claims Window Does Not

September 17, 2026
AOA and AOY: What the Ratio Means
Blog

AOA, AOY and the Ratio You Pick

September 17, 2026

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • One Crore or Fifty Lakh?
  • How Much Cover Is Enough for a Surgeon?
  • Defence Costs: Inside or On Top?
  • Five Moments You Assume You Are Covered
  • The Exclusions Page, in Plain Language

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In