help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

Multi-Year or Annual Renewal?

coveryouadmin by coveryouadmin
September 17, 2026
in Blog
Reading Time: 4 mins read
0 0
0
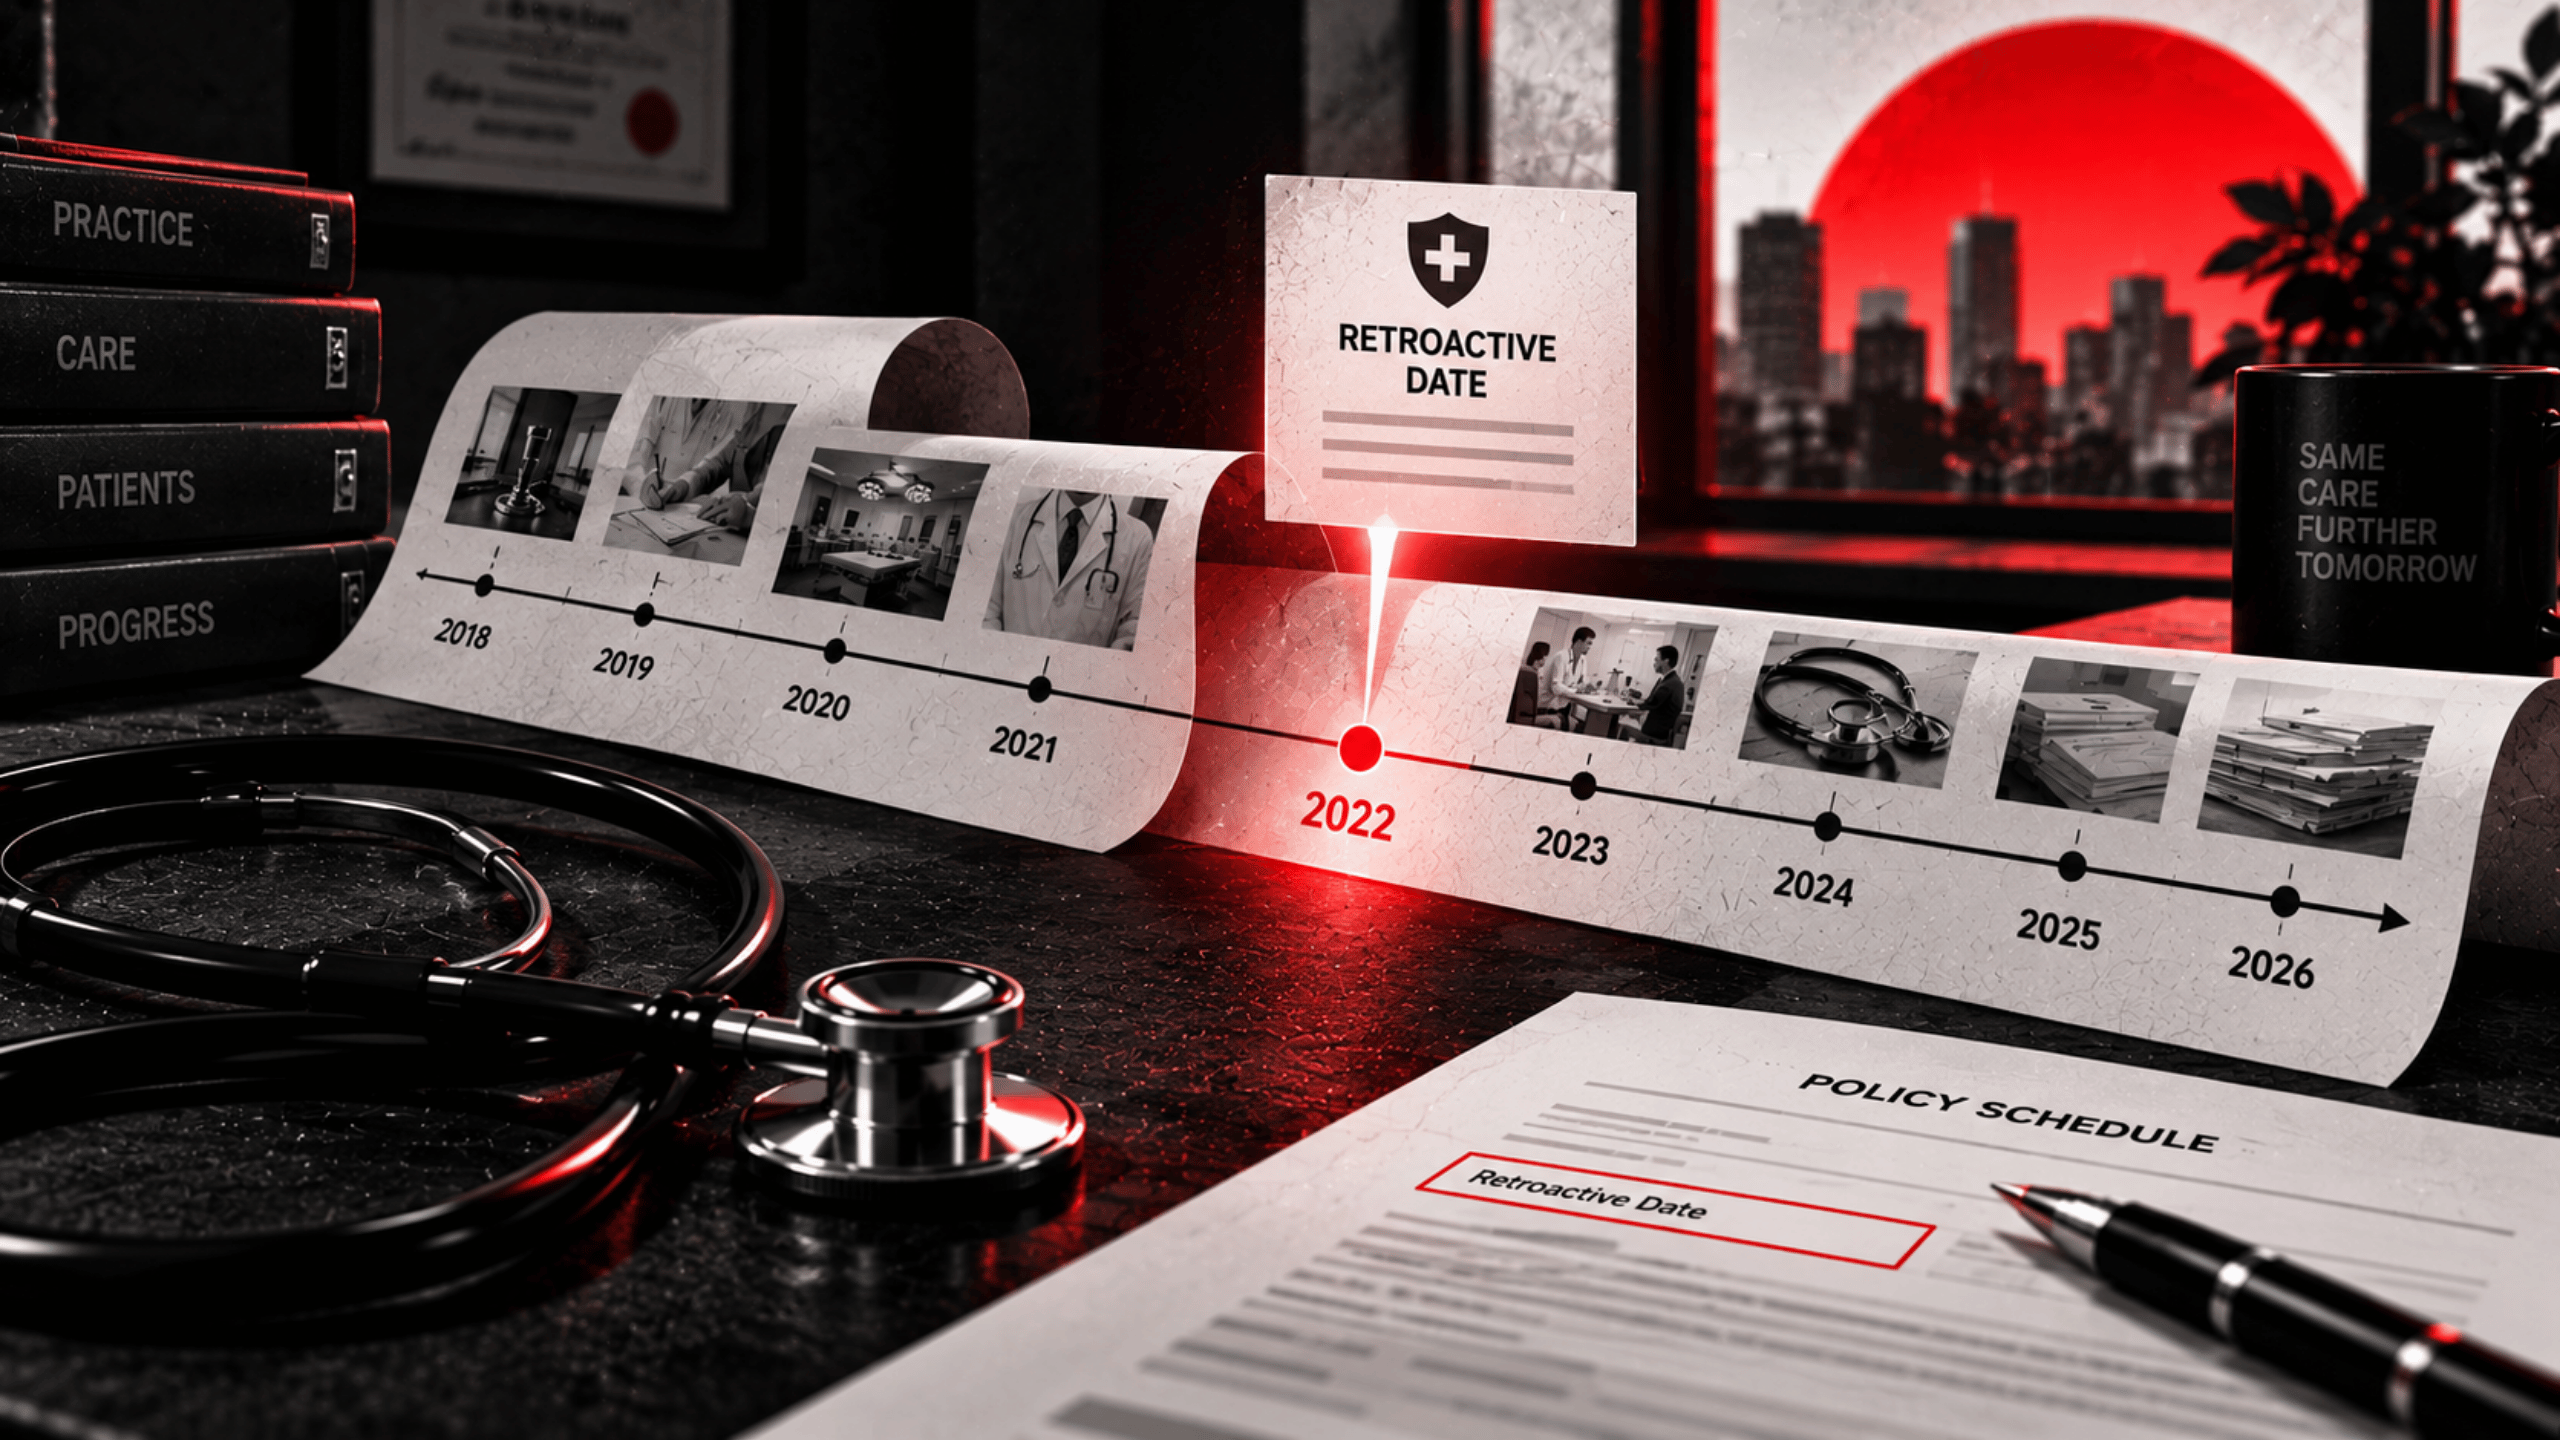
Red, black and white editorial image showing consecutive insurance calendar periods progressing into continuous medical professional protection.

Annual or multi-year—the real priority is keeping your protection continuous.

You forgot your renewal once.

It happened exactly three years ago.

You caught the dangerous lapse four days late.

Consequently, that highly stressful memory simply refuses to leave you.

Therefore, locking your cover in for three years sounds incredibly appealing.

Specifically, it feels like the perfect permanent solution to your own worst habit.

However, before you start searching blindly, you must understand the rules first.

Evaluating the multi-year indemnity policy vs annual renewal debate requires absolute clarity.

There is exactly what the Indian regulator legally permits.

Conversely, there is what insurance companies actually offer on the shelf today.

What The Regulator Allows For Long Term Insurance Policies

The insurance regulator issued a highly important master circular recently. Specifically, this June 2024 circular strictly governs general insurance business. It clearly provides that general insurance policies may be issued differently. Therefore, policies can legally run on an annual, long term, or short term basis. Consequently, long term policy tenure is officially permitted in principle across India. You can review official regulatory updates directly on the Insurance Regulatory and Development Authority of India (IRDAI) portal.

However, being legally permitted is not the exact same as being readily available. Whether any Indian insurer currently files and sells a multi year product remains highly uncertain. Therefore, you must ask your specific insurer directly. Do not blindly assume the answer either way.

Why Annual Professional Indemnity Renewal Remains The Norm

Ask any experienced broker about doctor insurance policies in India. Almost every single medical practitioner currently holds a standard one year policy. Furthermore, the real reason for this is absolutely not market inertia. Conversely, the financial product is deliberately built around an annual rhythm. Specifically, these structural reasons actively work directly in your professional favor. Professional indemnity is strictly written on a claims made basis. Consequently, this unique legal structure actively pushes the entire product towards annual cycles. You can track shifting medical practice guidelines comprehensively on the National Medical Commission (NMC) website.

  • Risk changes yearly: A new clinical procedure or hospital alters your exposure.
  • Disclosure is annual: Patient claims and legal notices are declared at each renewal.
  • Limits get revisited: The exact sum insured you needed previously may not suit you now. Review your medical liability insurance limits regularly.
  • Policy wordings evolve: Insurance terms and legal definitions change constantly between filings.

None of that makes a longer tenure strictly wrong. However, it clearly explains exactly why the market settled here permanently.

What Continuous Insurance Coverage Options Compete On

Here is the exact point most of this debate misses completely. The benefit people genuinely want is absolutely not the long tenure itself. Conversely, doctors desperately want continuous insurance coverage forever. Specifically, they want to completely avoid any dangerous coverage gaps. Furthermore, they want absolute retroactive date preservation. Continuity is completely achievable on a standard annual policy. It simply requires a highly reliable calendar reminder. Therefore, it requires a fully working bank payment mandate. Renew precisely on time every single year. Consequently, your retroactive date holds exactly as it would under a longer contract.

Which completely reframes the multi-year indemnity policy vs annual renewal choice into something far more useful. Specifically, it is absolutely not about which tenure is inherently better. Conversely, it is simply about what actually stops you from missing a critical date. You can carefully review statutory contract rules under the Indian Contract Act to understand policy continuity.

Critical Questions Before Signing A Long Term Policy Tenure

If a longer tenure is formally offered to you, proceed very carefully. Therefore, ask these specific questions before signing anything. Furthermore, you must get these exact answers firmly in writing.

  • What happens to the retroactive date: It must firmly carry your original date forward.
  • How disclosure works mid term: Confirm exactly how you report a sudden practice change.
  • Whether coverage limits can be revised: Clarify if upgrading requires a brand new policy. Ensure your doctor insurance renewal process is clear.
  • How premium is paid: Confirm the exact payment structure before assuming instalments exist.
  • How cancellation works: Refunds strictly apply to completely uncommenced policy years.

What Actually Protects Your Retroactive Date Preservation

Whichever tenure you ultimately choose, the protective behavior remains absolutely identical. Set two strict calendar reminders right now. Specifically, set them forty five and fifteen days before expiry. Set them strictly in your own personal calendar immediately. Therefore, stop relying on the insurance company to chase you. Verify your bank payment mandate actually works perfectly. Failed mandates cause significantly more policy lapses than simple forgetfulness does. Furthermore, read your policy schedule the exact moment it arrives. Check the retroactive date, the specialty, and the exact financial limits. Disclose anything that changed during the year clearly in writing.

A longer policy is simply a modern convenience. Conversely, continuous proactive protection is your ultimate financial shield. Therefore, set your renewal reminders right away. This is the one step no insurance product can ever do for you. Understanding the multi-year indemnity policy vs annual renewal differences keeps your medical practice completely safe. Ultimately, mastering the multi-year indemnity policy vs annual renewal decision secures your long term professional peace of mind.

5 FAQ SECTION

Does IRDAI permit multi year general insurance policies?

Yes. The June 2024 master circular provides that policies may be issued on an annual, long term, or short term basis. However, actual product availability strictly depends on the individual insurer.

Can I buy a three year professional indemnity policy as a doctor?

You must ask your specific insurer. Long term tenure is permitted in principle. Conversely, the actual availability of a multi year doctors indemnity product varies significantly today.

Would a multi year policy protect my retroactive date better?

Not inherently. What strictly preserves your retroactive date is completely unbroken cover. Therefore, an annual policy renewed exactly on time achieves the exact same legal outcome.

Can I pay a long term premium in monthly instalments?

Do not blindly assume so. Instalment premium arrangements differ vastly by product and specific insurer. Therefore, confirm the exact payment structure clearly in writing before fully committing.

What happens if I cancel a policy longer than one year?

Under the current circulars, refund rules differ based on tenure. Specifically, for terms over one year, refunds apply strictly to policy years where risk cover has not yet commenced
Tags: continuous insurance coveragedoctor insurance planningdoctor insurance renewal Indiadoctor liability insurancehealthcare risk managementinsurance policy cancellation refundIRDAI master circular general insurancelong term insurance policy IRDAImedical indemnity Indiamedical malpractice covermulti-year indemnity policy vs annual renewalpolicy tenure general insuranceprofessional indemnity doctorsprofessional indemnity renewalretroactive date preservation
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

Can You Insure Without a Registration Number?

Next Post

Claims-Made vs Occurrence, Explained

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Five Moments You Assume You Are Covered
Blog

Five Moments You Assume You Are Covered

September 17, 2026
The Exclusions Page, in Plain Language
Blog

The Exclusions Page, in Plain Language

September 17, 2026
Run-Off Cover: After You Stop Practising
Blog

You Retire. The Claims Window Does Not

September 17, 2026
AOA and AOY: What the Ratio Means
Blog

AOA, AOY and the Ratio You Pick

September 17, 2026
Retroactive Date: The Line That Decides
Blog

The Most Important Date on Your Policy

September 17, 2026
Claims-Made vs Occurrence: When Does Your Cover Respond?
Blog

Claims-Made vs Occurrence, Explained

September 17, 2026
Next Post
Claims-Made vs Occurrence: When Does Your Cover Respond?

Claims-Made vs Occurrence, Explained

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Five Moments You Assume You Are Covered
  • The Exclusions Page, in Plain Language
  • You Retire. The Claims Window Does Not
  • AOA, AOY and the Ratio You Pick
  • The Most Important Date on Your Policy

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In