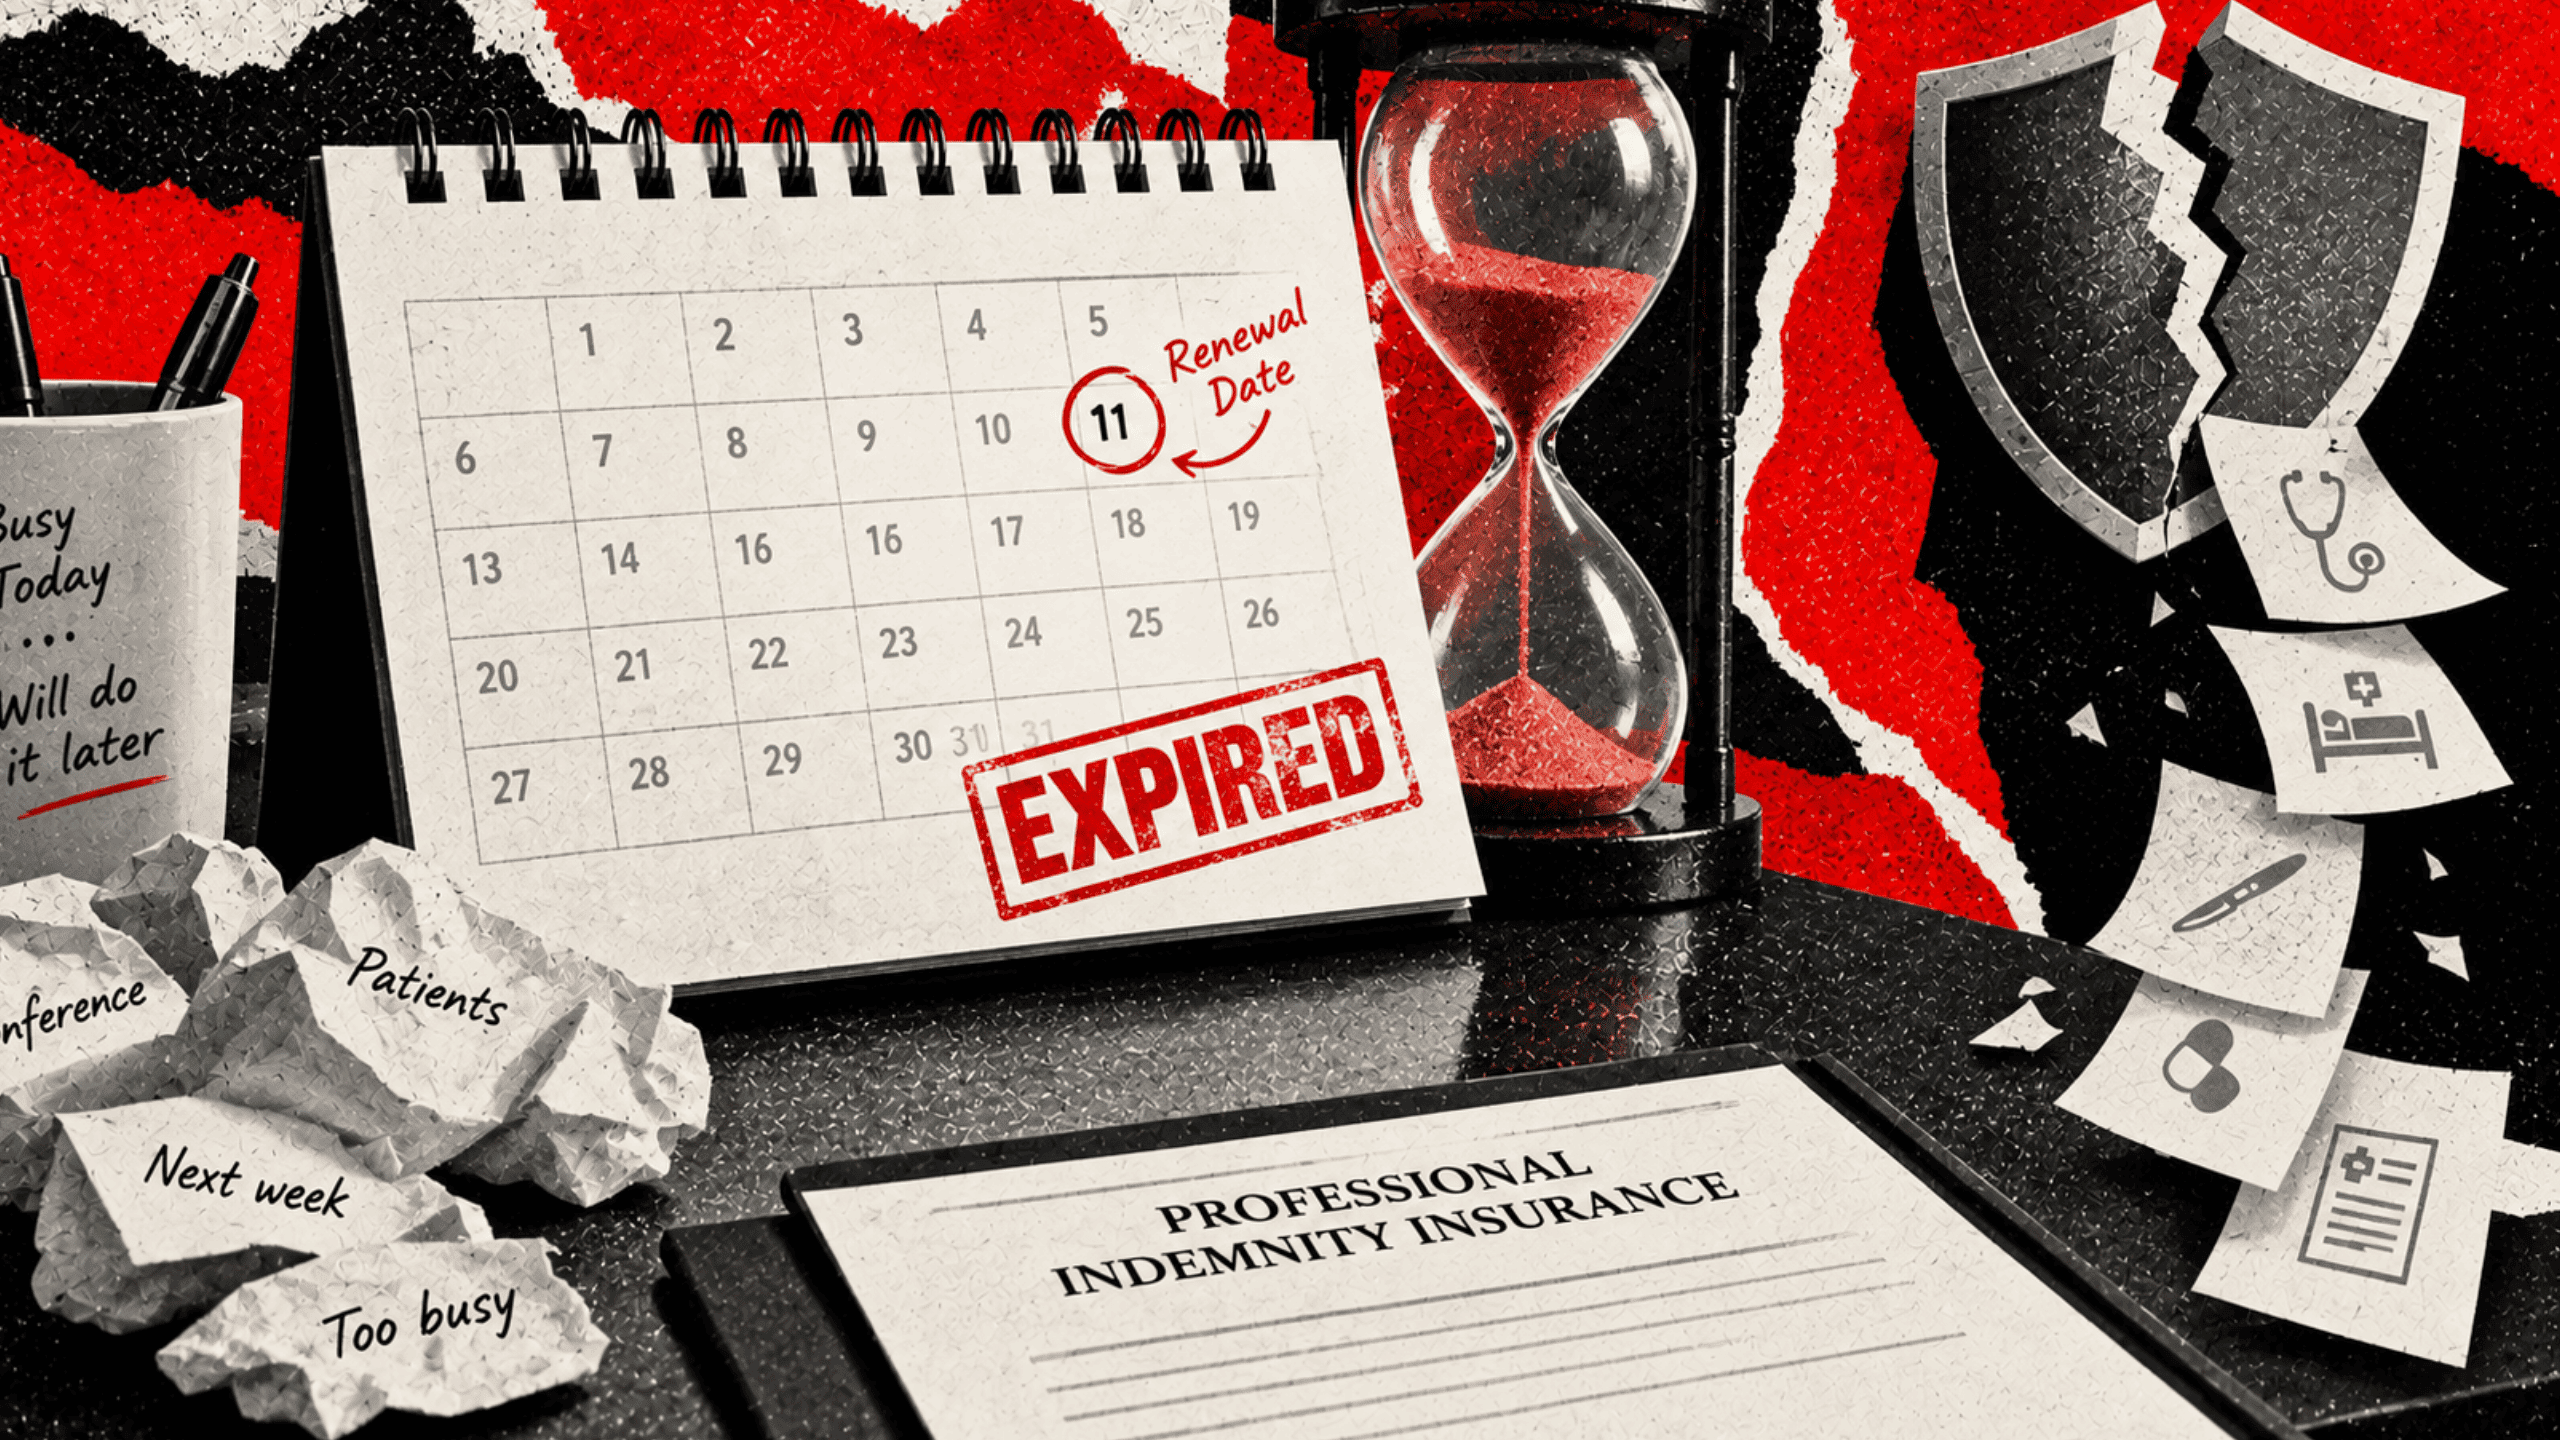
The renewal notice arrives during a particularly bad fortnight.
You fully mean to deal with it on Sunday.
However, Sunday quickly becomes next weekend.
A medical conference intervenes.
Consequently, when you finally open the email, the policy expired eleven days ago.
Nothing feels fundamentally different. The clinic runs smoothly. Patients come regularly. Furthermore, nobody mentions it.
Ask exactly what happens if indemnity policy lapses, and most doctors picture a small gap in cover.
Conversely, the reality is significantly worse. Therefore, it stays completely invisible until the exact day it becomes catastrophic.
The Expected Damage Of Uninsured Days
Two separate things break when a policy lapses. Doctors usually only see the first one.
From the precise minute after expiry, there is absolutely no cover. Specifically, you get no legal defence costs, no representation, and no settlement funding.
Every consultation, procedure, prescription, and referral in that specific window sits entirely on you. If a patient treated then brings a legal claim in 2029, there is no valid contract for the insurer to respond to.
Defending a consumer matter in India commonly runs into several lakh rupees before any award is considered. Furthermore, there is a severe working consequence too. Many hospitals and empanelment contracts strictly require proof of current cover. Consequently, a lapse can completely interrupt your ability to practise at all until it is properly fixed. Verify these strict requirements through the National Medical Commission.
What Happens If Indemnity Policy Lapses And Dates Reset
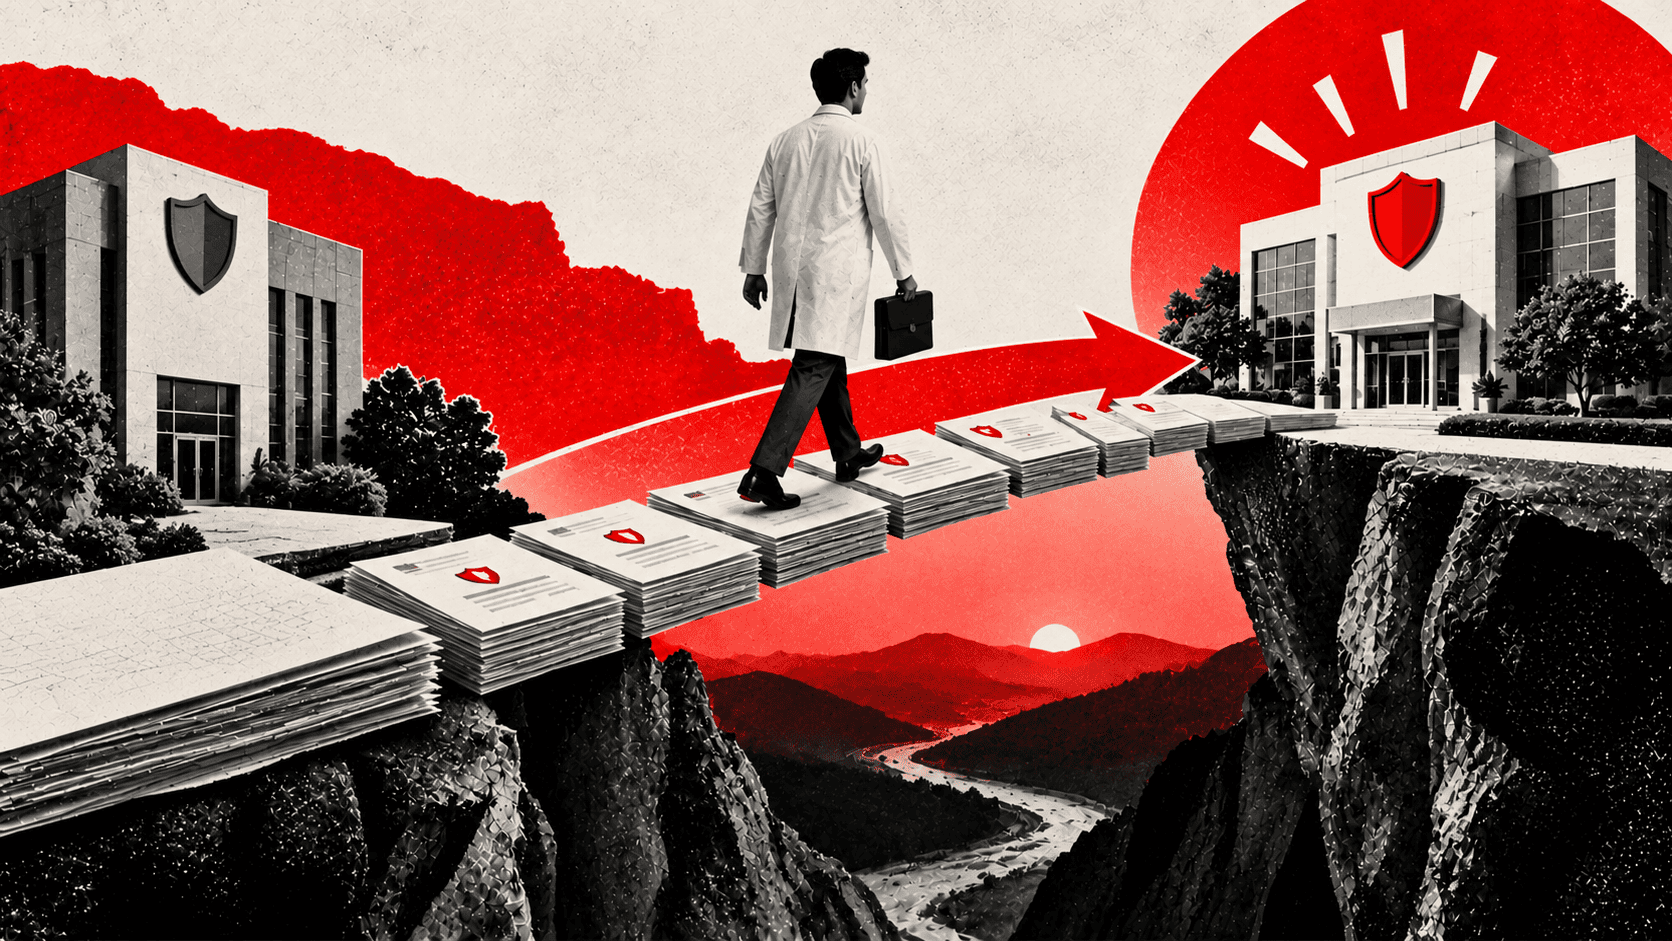
Here is the exact part that catches experienced doctors. It is exactly what happens if indemnity policy lapses that nobody mentions at renewal. Under strict claims made wording, a lapse does not only strip cover for the immediate gap. Specifically, it resets your retroactive date completely.
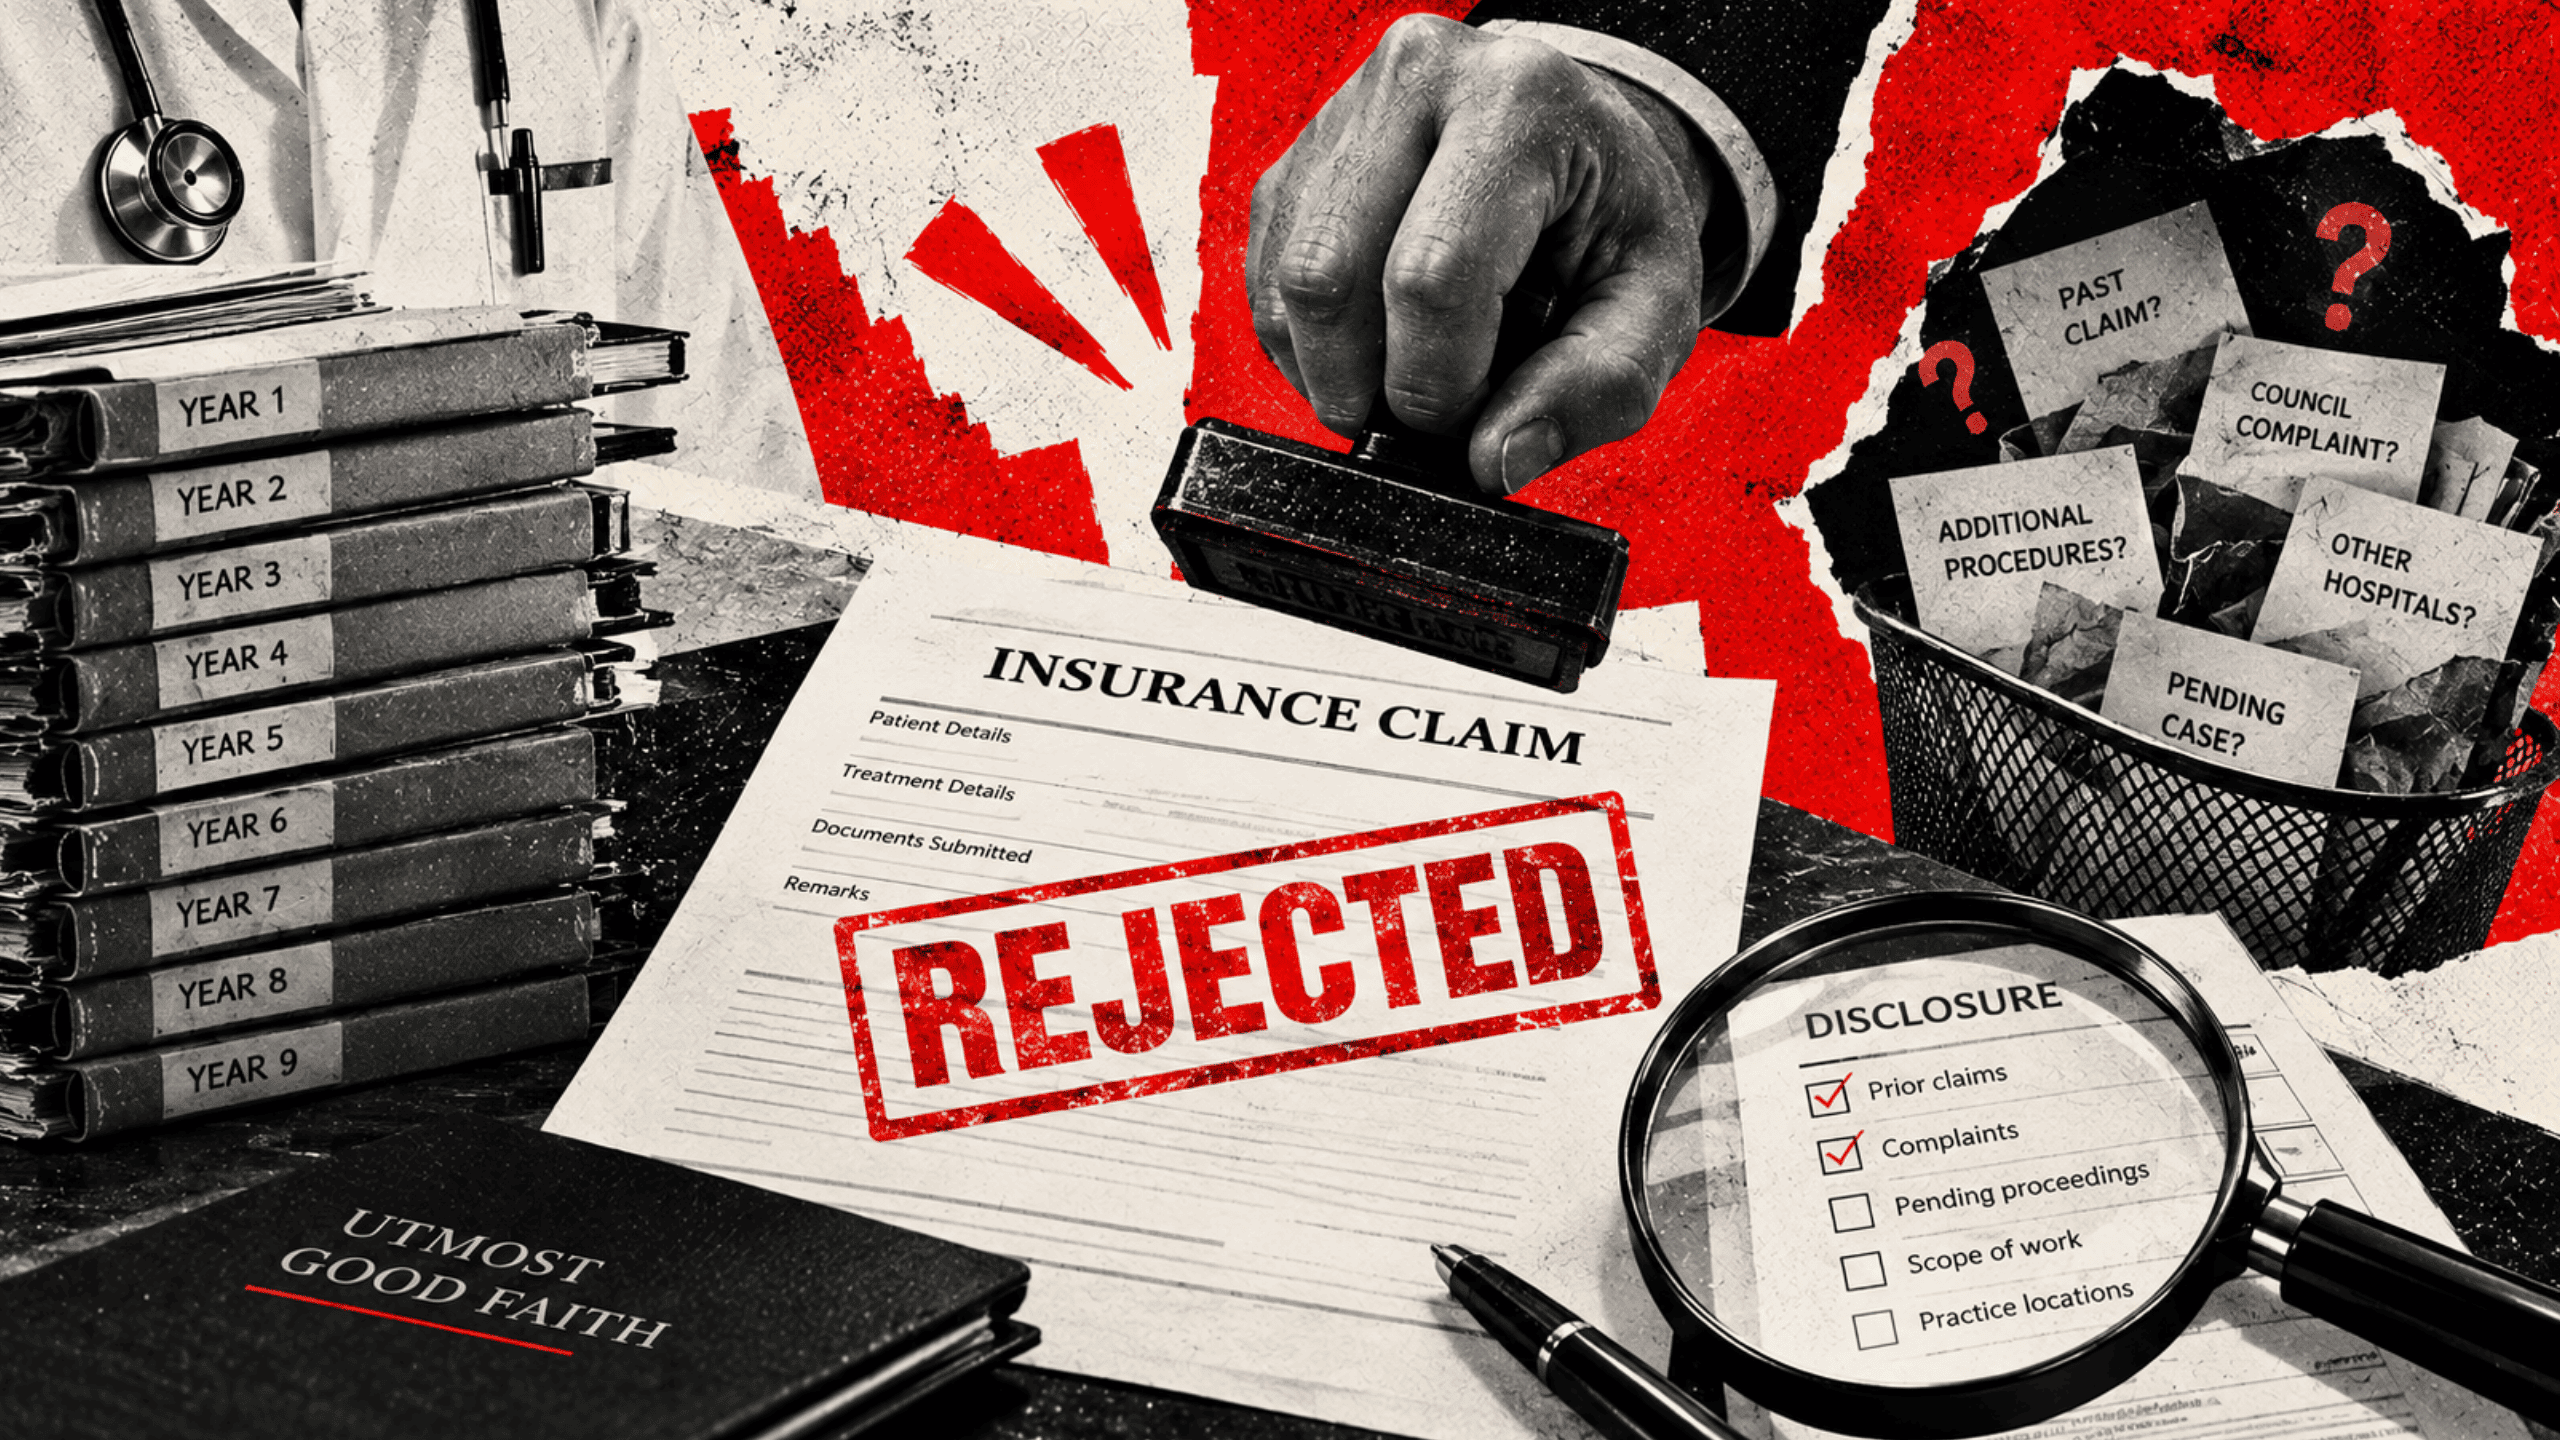
When you reinstate or buy fresh, the new schedule carries today’s date. Therefore, the fifteen years you insured continuously and paid for faithfully now fall completely outside the active policy.
So, eleven days does not simply create an eleven day hole. It can systematically erase your entire insured history at once. Furthermore, nothing sold afterwards will ever give it back.
Picture how that actually plays out. A senior surgeon lets a policy slip during a hospital transition. They reinstate six weeks later with a completely new retroactive date. Two years on, a legal notice arrives about an operation performed well before the lapse. The claim is refused completely and correctly. The medical treatment predates the new date. Furthermore, the old policy was not live when the claim was filed. Therefore, both limbs of the test fail at once. Understand your legal standing deeply under the Indian Contract Act.
Why A Policy Grace Period Does Not Exist
Doctors wrongly assume indemnity works exactly like a life policy with thirty days built in. It absolutely does not. Consequently, that dangerous assumption turns a simple missed date into a full month of complacency.
- Liability cover is date strict: The policy either was in force on the relevant date, or it absolutely was not.
- Reinstatement is not automatic: Most insurers treat a lapsed policy as a completely fresh proposal.
- Continuity is usually gone: Even where a policy is properly revived, prior acts are often not restored.
- Nothing covers the gap: No insurer will retrospectively cover uninsured days. Check the official IRDAI guidelines regarding strict policy reinstatement.
Recovering When Your Indemnity Insurance Lapses
Move today rather than waiting for this weekend. The liability gap grows every single hour. Therefore, your options narrow significantly with it.
- Check the exact date: Read the printed schedule rather than trusting your memory.
- Call the insurer today: Ask specifically about reinstatement with continuous cover. Some allow it within a very short window.
- Buy fresh if they refuse: A brand new policy dated today still beats nothing by a massive margin.
- Declare the gap honestly: Hiding a lapse adds a severe non disclosure problem to an existing coverage problem.
- Document the interim: Keep highly meticulous records of every single patient seen while uninsured. Review cases at the National Consumer Disputes Redressal Commission to understand rising litigation trends.
Preventing The Indemnity Policy Gap
Set two strict reminders in your own calendar. Place them forty five and fifteen days out. Use an auto debit facility. Then, actively verify the debit actually went through. Failed bank mandates are a highly common cause of lapse. Renew a full fortnight early. Consequently, there is absolutely no penalty for it.
Final Thoughts On Preserving Your Medical Cover
A sudden lapse costs you two major things. It costs cover for the immediate gap, and cover for everything before it.
The first consequence is temporary. Conversely, the second is permanently damaging. No premium you pay later buys it back. Check your exact expiry date tonight. It is definitively the most important date in your entire professional calendar. Fully understanding what happens if indemnity policy lapses protects your hard earned career.
5 FAQ SECTION
Is there a grace period for professional indemnity insurance in India?
Generally no. Unlike life insurance, liability cover is strictly date bound. Some insurers permit reinstatement within a short window. However, that is a rare concession, not a guaranteed grace period.
Can a claim from my lapse period ever be covered?
No. No insurer will retrospectively cover days when no policy was in force. Treatment given during the gap remains permanently at your personal cost.
What happens to my retroactive date after a lapse?
It is usually reset completely to the start date of the new policy. That completely removes cover for all your earlier practice. Consequently, this is exactly why a short lapse causes disproportionate harm.
How do I restore a lapsed indemnity policy?
Contact your insurer immediately. Ask directly about reinstatement with continuity. If that is strictly refused, buy a fresh policy at once and declare the gap on the proposal form.
Will a past lapse make future cover more expensive?
The premium impact is usually minor. The real cost is deeply structural. Specifically, the reset retroactive date leaves your earlier years permanently outside any active policy.