help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

Switching Insurers? Read This First

coveryouadmin by coveryouadmin
September 16, 2026
in Blog
Reading Time: 5 mins read
0 0
0
Switching Insurers? Read This First

A new quote suddenly lands in your inbox in March.

It has the exact same sum insured.

It covers the exact same specialty.

Furthermore, it is twenty per cent cheaper than what you pay right now.

You only have three days before your renewal date.

Consequently, it looks like the easiest financial decision of the month.

It is absolutely not. Specifically, switching indemnity insurer without losing retroactive date is a completely different exercise from switching a basic motor policy. You are not only buying next year. Furthermore, you are carrying forward every single year you have already paid for.

What You Are Actually Carrying With You During An Indemnity Switch

Open your current policy schedule immediately. Find the specific retroactive date. It is usually the exact day your very first policy started. Furthermore, it has quietly survived every single renewal since.

That specific date is what makes today’s policy answer a claim about a surgery you performed in 2017. Under strict claims made wording, the policy must be live when the legal claim is formally filed. Therefore, the medical treatment must fall on or directly after that date. Lose the date, and everything before the switch stops being insurable permanently.

Think of it as a highly valuable asset. You have been paying consistent instalments on it for years. The premium buys next year. Conversely, the date is what you already own. You can explore medical risk management to understand why protecting this asset is absolutely vital.

How A New Insurer Agrees To Honour Your Prior Acts Coverage

This is exactly where the switch is either won or lost. It is entirely administrative. Which is simply another way of saying it is entirely preventable.

They will certainly agree, but only against solid evidence. Portability here is not automatic. It is unlike standard health insurance. There is absolutely no mandated transfer of your clinical history. It only happens because you asked. Furthermore, you produced the correct paperwork. Always review the standard portability guidelines on the IRDAI website. Successful switching indemnity insurer without losing retroactive date strictly requires proper documentation.

  • Current policy schedule: Showing the existing retroactive date explicitly in writing.
  • Prior year schedules: Three to five years, to show a completely unbroken chain.
  • Claims experience letter: Procured directly from the outgoing insurer.
  • A proposal that says so: The explicit written request to preserve prior acts, stated on the form.

Get the prior acts position confirmed on the official quotation before you pay. A verbal assurance from a sales executive is worth absolutely nothing. Consequently, it completely fails when a medical claim is assessed four years later. Always consult a doctor insurance broker for proper written terms.

The Four Ways Doctors Fail At Continuous Insurance Coverage

The complicated process of switching indemnity insurer without losing retroactive date fails in four highly predictable ways. Every single one of them is administrative rather than clinical.

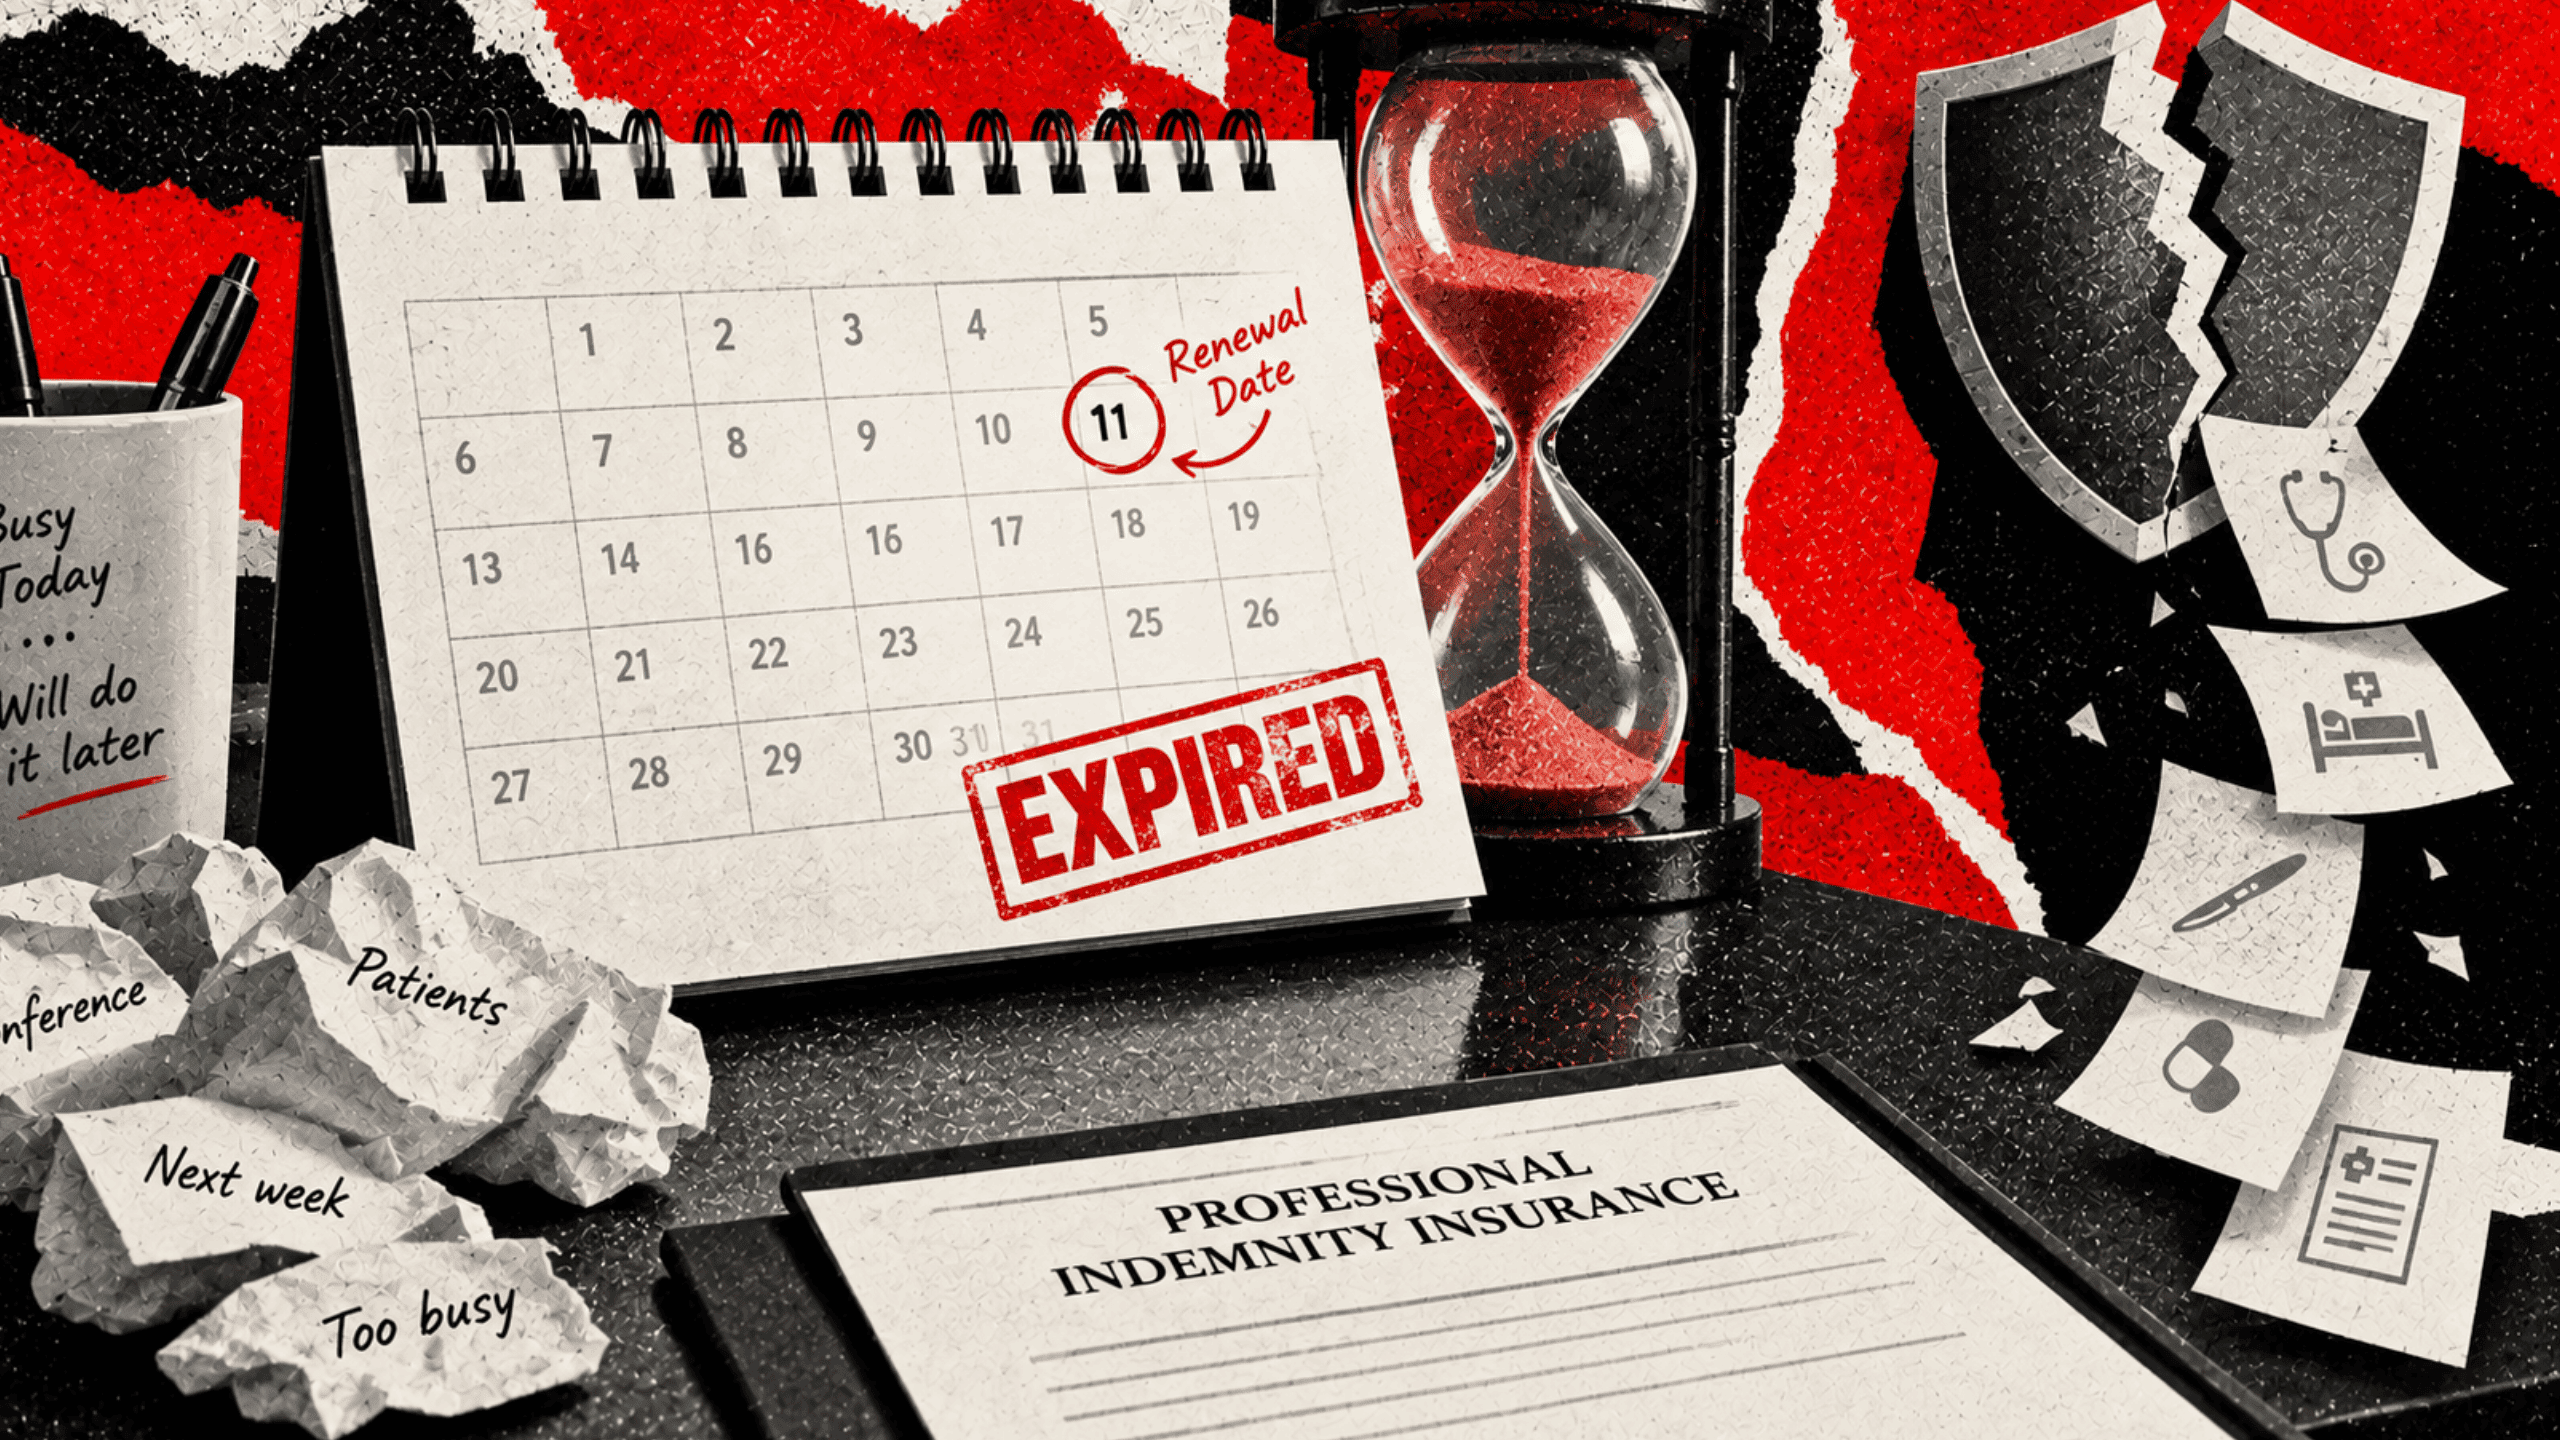
  • Letting the old policy expire first: One uncovered day breaks continuity. Therefore, it resets the date.
  • Assuming it transfers automatically: If it is not printed directly on the new schedule, it absolutely does not exist.
  • Not reading the new policy: Check it the exact day it arrives. Do this while it can still be quickly corrected.
  • Chasing price alone: A cheaper premium with a reset date is a massive downgrade. However, it is aggressively sold as a saving.

The absolute worst version is the doctor who switches simply to save money. They discover the painful reset two years later. By then, they have a serious matter running from a period that no longer has active cover. Consequently, this simple mistake leaves you exposed under the Indian Contract Act. Ensure your professional indemnity cover is thoroughly verified.

Doing Your Doctor Insurance Renewal In The Right Order

Treat this entire process as a strict sequence rather than a quick purchase. Every single failed switch this year happened because someone did step four before step two.

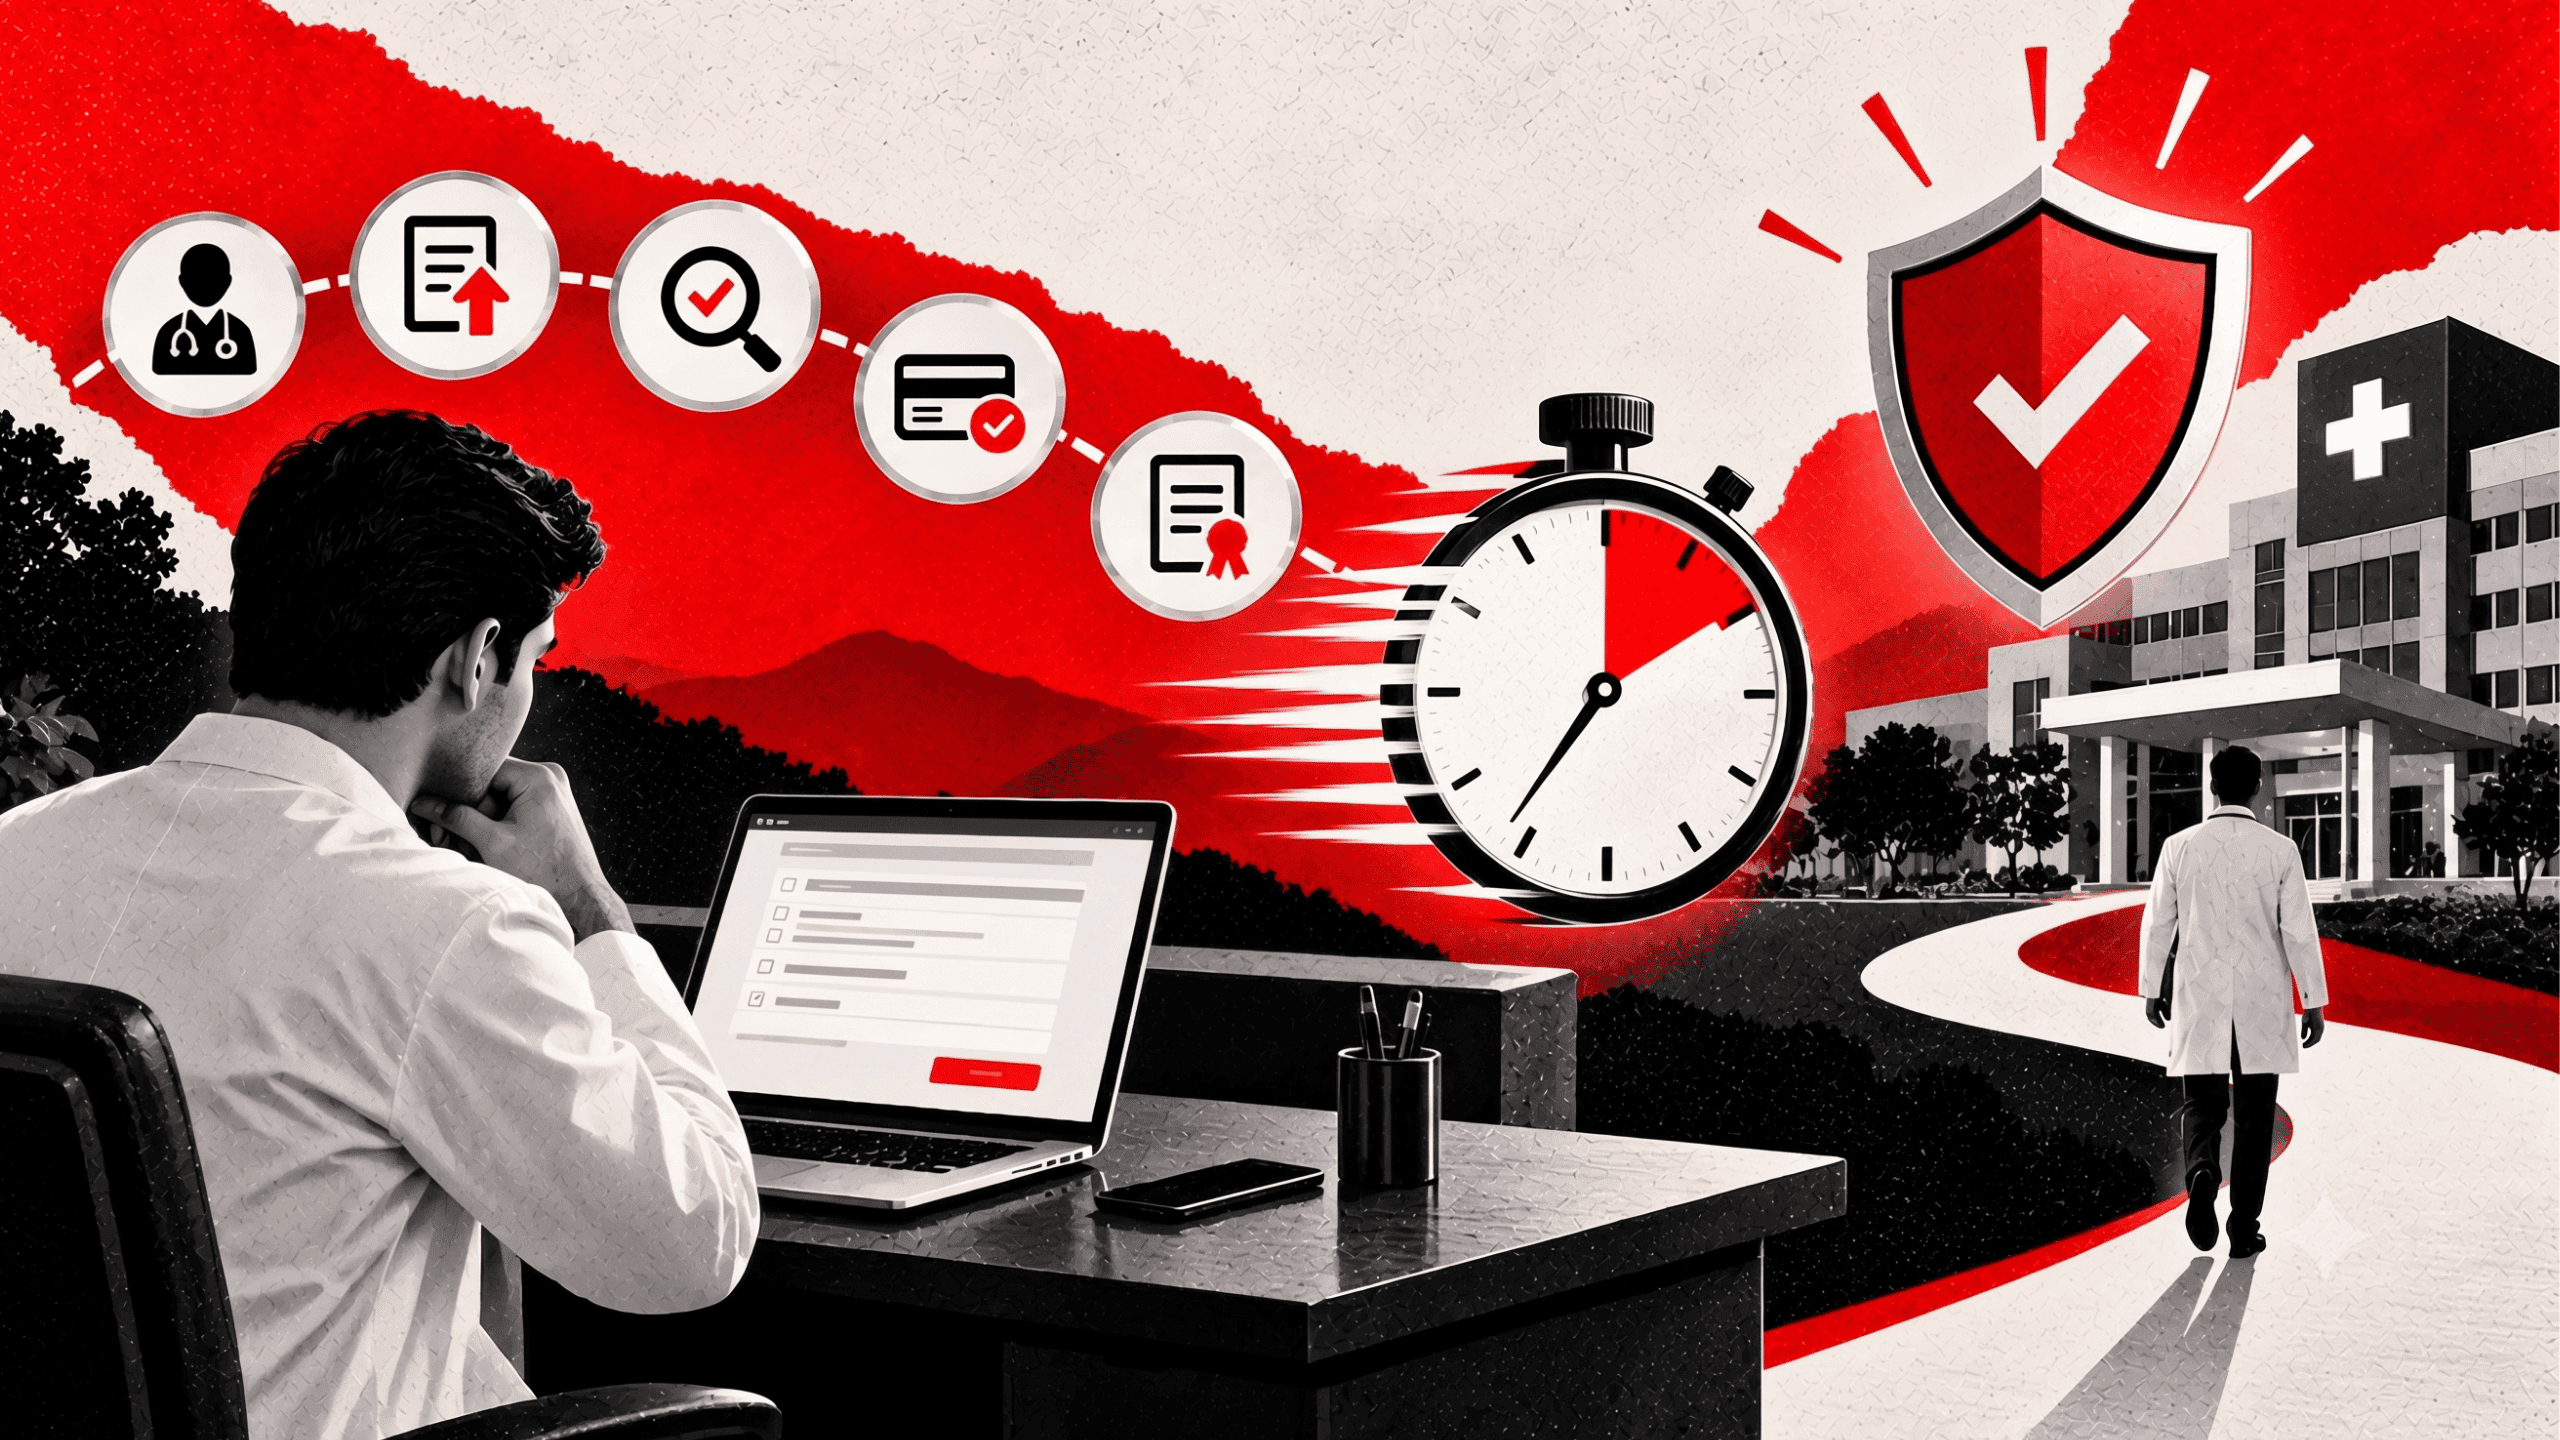
Start a full month before your renewal. Do not start the week of it. Rushed switches are exactly where dangerous gaps appear. Usually, a document took three days to arrive. Meanwhile, the old policy completely expired.

Pull your documents together safely. Get the quote in writing with the retroactive date clearly on it. Set the new policy to start the exact day the old one ends. Pay before expiry rather than exactly on it. Consequently, check the schedule the absolute moment it successfully lands in your inbox.

Sometimes the honest answer is to simply stay. If your current insurer handled a claim extremely well, continuity is highly valuable. If your history includes a properly declared matter, continuity with a known insurer can be worth significantly more than a minor discount. Read the specific wording too. Defence cost treatment matters immensely. Furthermore, sub limits on legal expenses matter substantially more than saving a few thousand rupees.

The One Rule That Governs Medical Liability Porting

No gap. Ever. Not even for a single day.

Keep that strictly, and you get the financial saving and your history together. Break it, and you have quietly paid for years of cover you can no longer legally use. This is tragically exchanged for a minor discount you will have completely forgotten by August. Therefore, executing switching indemnity insurer without losing retroactive date flawlessly is non negotiable. It is the only way to maintain your healthcare legal protection for the long term.

5 FAQ SECTION

Can I change insurers without losing my retroactive date?

Yes. Indian insurers routinely accept an existing retroactive date where continuous prior cover can be evidenced. Provide your previous schedules and specifically ask for the date to be confirmed in writing on the new policy.

What documents preserve my retroactive date when porting?

Your current policy schedule is required. Ideally, provide three to five years of prior schedules, and a claims experience letter from the outgoing insurer. Without these, the new insurer has absolutely no basis to backdate.

What if there is a gap between my old and new policy?

Even a single one day gap breaks continuity completely. The new insurer will instantly treat you as a fresh customer. Therefore, they set the retroactive date at inception, leaving all your earlier practice completely uninsured.

Will the new insurer cover claims from my past practice period?

Only for treatment on or after the retroactive date clearly shown on the new schedule. If your original date is successfully carried across, past work stays covered. If it is reset, it absolutely does not.

Should I overlap the two policies to be safe?

A same day handover is usually sufficient and effectively avoids paying twice. However, if dates are awkward, a very short overlap is far safer than running any risk of a gap.
Tags: continuous indemnity covercontinuous insurance coveragedoctor insurance brokerdoctor insurance renewaldoctor liability insurancehealthcare legal protectioninsurer migration IndiaIRDAI portability rulesmedical liability portingmedical malpractice renewalmedical risk managementprior acts coverageprofessional indemnity switchretroactive date preservationswitching indemnity insurer without losing retroactive date
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

One Old Complaint. Declare It Or Not?

Next Post

Eleven Days Uncovered: An Indemnity Policy Lapse

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Protection Beyond the Age Barrier
Blog

Still Practising At 68? The Age Limit Myth

September 16, 2026
Racing the Clock to Get Covered
Blog

Covered By Tonight? Policy Activation Timelines Explained

September 16, 2026
One Case Behind You, Future Risk Ahead
Blog

A Pending Case And A New Insurance Policy

September 16, 2026
The Gap That Breaks Your Protection
Blog

Eleven Days Uncovered: An Indemnity Policy Lapse

September 16, 2026
The Complaint That Comes Back
Blog

One Old Complaint. Declare It Or Not?

September 16, 2026
The Claim That Never Gets Through
Blog

Paid Every Premium, Still Rejected

September 16, 2026
Next Post
The Gap That Breaks Your Protection

Eleven Days Uncovered: An Indemnity Policy Lapse

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Still Practising At 68? The Age Limit Myth
  • Covered By Tonight? Policy Activation Timelines Explained
  • A Pending Case And A New Insurance Policy
  • Eleven Days Uncovered: An Indemnity Policy Lapse
  • Switching Insurers? Read This First

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In