It is August.
Your hospital empanelment renewal notice just arrived.
Suddenly, you realize you do not hold a personal policy.
You open an online portal quickly.
You select your medical specialty carefully.
Then, a very reasonable thought occurs.
The financial year is already half gone.
Therefore, do you only pay half the price?
Many doctors ask about indemnity insurance mid year purchase pro rata terms when buying cover.
However, the most common assumption about indemnity insurance mid year purchase pro rata pricing is completely wrong.
Specifically, the calculation does not work the way most medical practitioners assume.
Conversely, understanding how your policy year works will save you from major confusion.
Mid-Year Purchase: What You Actually Pay
You enter your details online. The full annual premium appears on your screen. This often causes immediate confusion. Doctors assume mid-year purchases automatically come with a fifty percent discount. However, insurance contracts operate on annual terms. The word pro-rata does apply elsewhere in your policy. Specifically, it applies during mid-term policy cancellations. Conversely, it does not apply to your initial purchase date.
Your Policy Year Is Not The Financial Year
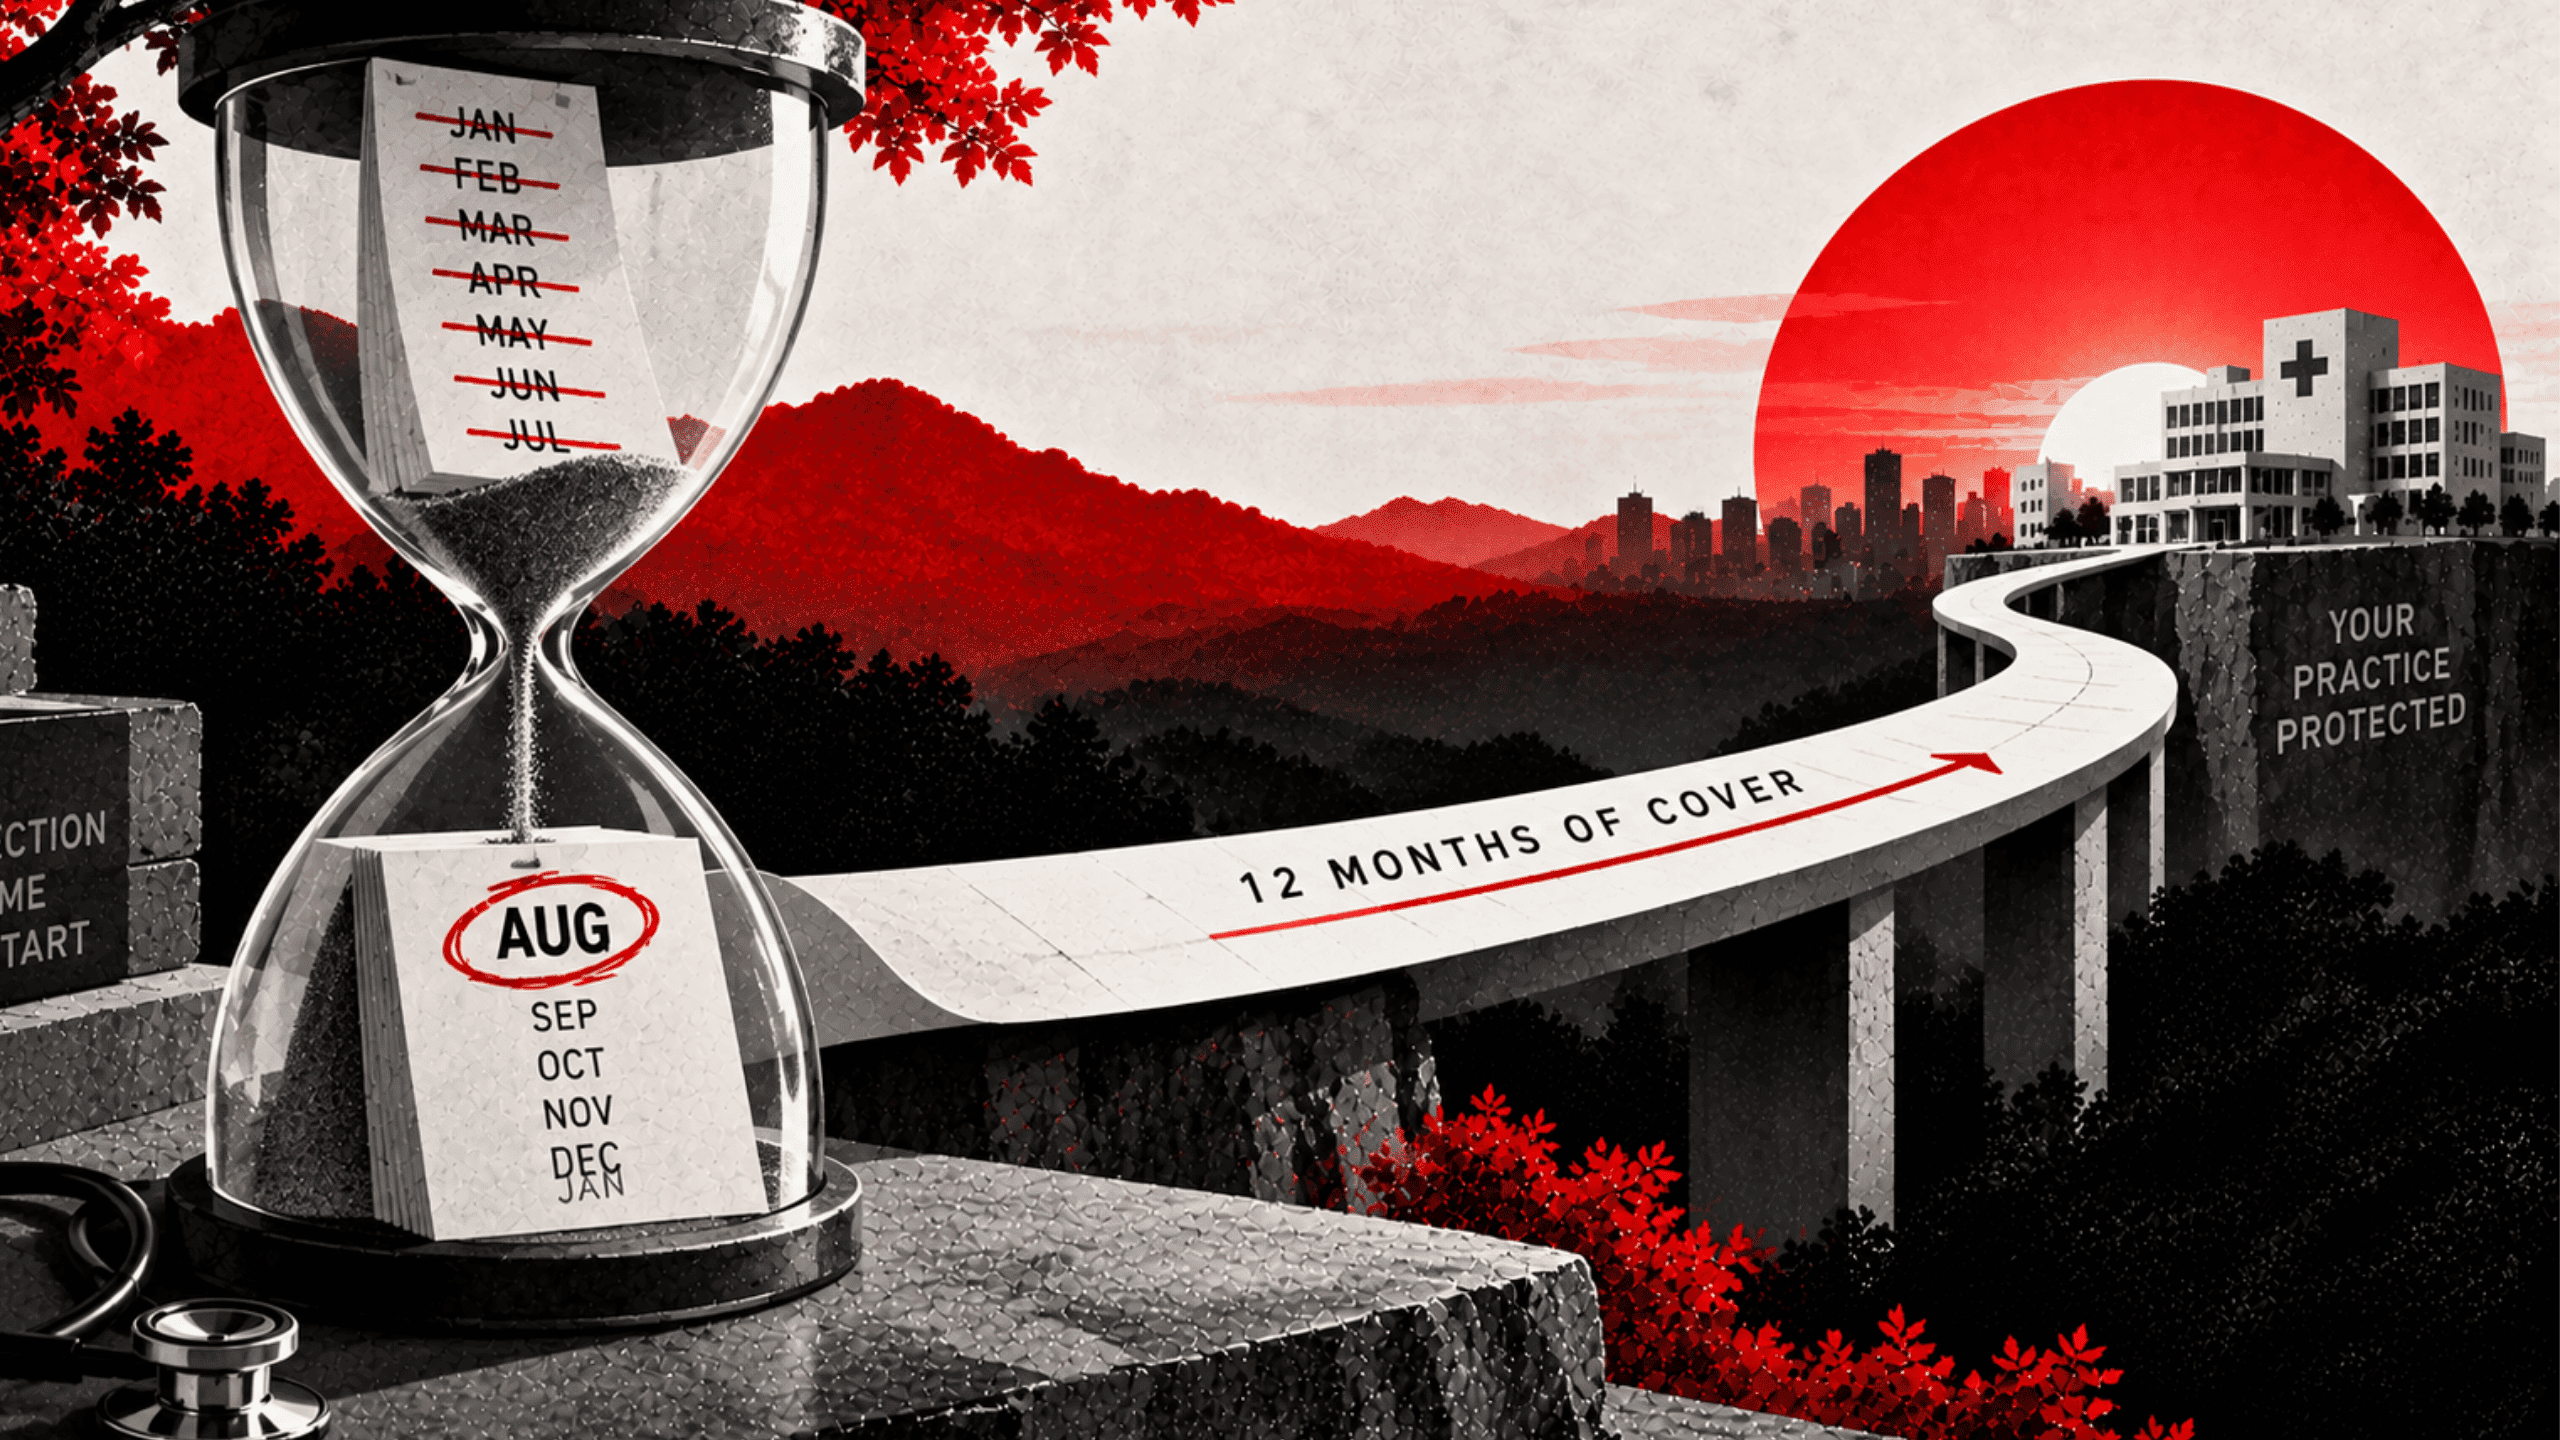
Start right here. Everything else follows from this single fundamental rule. An annual professional indemnity policy bought on 14 August runs until 13 August of the next year. Consequently, it is not a tiny stub of someone else’s financial year. Furthermore, it provides a full twelve months of active protection.
It simply happens to start in August. Therefore, you pay the full annual premium. In return, you get twelve full months of comprehensive cover. There is absolutely nothing to prorate when buying. Specifically, nothing is being cut short. The only thing an August start date changes is your future renewal date.
Doctors who expect a discount often confuse this with other insurance products. For example, household health policies often attach to a fixed annual cycle. However, professional liability coverage has no fixed calendar cycle.
Your policy year is set on the exact day you buy your policy. You can review official regulatory guidelines on the Insurance Regulatory and Development Authority of India (IRDAI) portal. Therefore, evaluating indemnity insurance mid year purchase pro rata details starts with understanding your inception date.
Where Short Period Insurance Premiums Apply
Occasionally, a doctor genuinely wants coverage for less than a full year. Most often, you want to align a new policy with an existing policy. Alternatively, you might want to bridge to a hospital empanelment date. Indian general insurance handles short term policies through a specific mechanism. Specifically, insurers price short period coverage using a short period scale. They do not calculate the cost strictly by counting daily ratios. The core principle is straightforward. A two month policy costs proportionately more than two twelfths of the annual premium.
Why does this happen?
Because fixed administrative costs do not shrink neatly with the calendar. Furthermore, medical malpractice risk does not drop simply because the policy is shorter. Short period scales vary between different insurance companies.
Therefore, if you require a short policy, ask for the exact rate in writing. Specifically, clarify your queries about indemnity insurance mid year purchase pro rata terms before committing.
Where Pro-Rata Actually Applies
The place where proportionate calculation genuinely appears is policy cancellation. The regulatory framework here has updated significantly in recent years. Most questions about indemnity insurance mid year purchase pro rata rules are really questions about mid-term cancellation, arriving one step early. Under IRDAI master circulars, a retail policyholder may cancel at any time during the active term.
Specifically, the insurer refunds premium for the unexpired period where the policy term is up to one year and no claim has been made during the period.
- Proportionate refund: Policyholders who cancel a one-year policy with zero claims receive an unexpired period refund.
- Multi-year policies: For terms over one year, refunds apply to policy years whose risk cover has not commenced.
- Claims effect: A premium refund is generally unavailable once a medical claim is filed.
- Insurer cancellation: Insurers can cancel policies only on grounds of established fraud, with notice.
Older policy contracts printed legacy retention scales of 25, 50, and 75 percent. However, where current circulars apply, the proportionate refund position governs instead.
If your policy document differs from current circulars, ask your insurer to confirm in writing which applies to your policy rather than working it out yourself. You can also read professional conduct guidelines on the official National Medical Commission (NMC) site. Furthermore, verify statutory contract principles on the official India Code repository.
Understanding indemnity insurance mid year purchase pro rata rules during cancellation prevents unexpected financial losses.
What To Do If You Are Buying This Month
Are you purchasing your policy this month? Follow these practical steps to secure your practice properly:
- Buy the full annual policy: Do not wait for a financial calendar cycle.
- Verify your inception time: Some policies start immediately while others start the next day.
- Mark your renewal date: Diarise your specific renewal month in your personal calendar.
- Request short period quotes: Never assume short term policies are strictly proportional.
- Store your schedule safely: Keep your digital schedule accessible for hospital empanelment audits.
Following these steps ensures your medical practice remains protected every single day. Therefore, navigating your policy options becomes simple and transparent.
The Key Takeaway
Mid-year is not a discount and not a penalty. Specifically, it is simply the exact day your twelve months of protection begin. The only date that matters afterwards is your renewal date. Put it in your calendar before you close the browser tab. Consequently, managing your expectations keeps your medical coverage smooth and completely uninterrupted.
5 FAQ SECTION
Do I pay less if I buy indemnity cover in the middle of the year?
No. An annual policy bought mid year runs a full twelve months from its inception date. Therefore, the full annual premium applies regardless of the calendar month.
Can I buy a policy for only a few months?
Short period cover is sometimes available. However, Indian general insurance prices short term policies on a short period scale rather than a daily pro rata rate.
Is a refund available if I cancel mid-term?
Under IRDAI master circulars, a retail policyholder who cancels a policy of up to one year with zero claims receives a refund for the unexpired period.
What if my policy wording shows a 25 or 50 per cent retention scale?
Older policy wordings carried legacy scales. Where current regulatory circulars apply, the proportionate refund rules govern. Ask your insurer to confirm in writing.
Does buying mid-year affect my retroactive date?
Your retroactive date is normally set on the inception date of your first policy. Buying in August simply sets your initial retroactive date in August.