help@coveryou.in
1800-202-6900
Professional Indemnity Insurance
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
Buy Policies
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Term Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How To Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements For Hospital
      • Regulatory Requirements Of Blood
      • Bio-Medical Waste Management
      • Death In OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections Of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases
  • Renew
    • Doctors
      • Renew Professional Indemnity
      • Renew Health Insurance
      • Renew Motor Insurance
      • Renew Terms Insurance
      • Renew Life Insurance
      • Renew Home Insurance
    • Hospitals
      • Renew Professional Indemnity
      • Renew Property Insurance
      • Renew Public Liability Insurance
      • Renew Money Insurance
      • Renew Employee Dishonesty Insurance
      • Renew Comprehensive Package Insurance
  • Claim
    • Claims Assistance
    • Track Claims
  • Support
    • Buy Now
    • Policies
    • Find A Medico-Legal Lawyer
    • Find Senior Doctor
    • Get Help
    • Manage Communication Preferences
No Result
View All Result
Professional Indemnity Insurance
No Result
View All Result
Home Blog

A Pending Case And A New Insurance Policy

coveryouadmin by coveryouadmin
September 16, 2026
in Blog
Reading Time: 5 mins read
0 0
0
One Case Behind You, Future Risk Ahead

A pending case may remain outside the policy while new protection can still begin for the future.

There is a hearing date currently on your calendar.

It is exactly six weeks away.

Between the high advocate fees and the endless paperwork, a practical thought keeps surfacing.

Specifically, you are still seeing forty patients a week.

Every single one of them is a fresh risk.

Furthermore, you are carrying this immense risk entirely alone.

Consequently, you look it up online. Is an indemnity policy for doctor with pending consumer case circumstances actually available? Yes. Will it help with the current case in front of you? No.

Most doctors only hear the second half. Therefore, they rapidly conclude that insurance is completely pointless for them. They spend the next four years entirely uninsured. Meanwhile, the legal matter grinds slowly through the complex system. Conversely, that is the most expensive reading of a very simple rule.

Why The Pending Legal Case Itself Cannot Be Covered

Insurance fundamentally responds to future uncertainty. A legal matter already filed is absolutely not uncertain. Specifically, it is a fully quantified liability with a court case number attached.

Underwriters officially call it a known circumstance. Every professional indemnity wording in India strictly excludes it. Furthermore, that is not hidden fine print. It is the basic logic the financial product runs on. If pending cases could be insured after filing, nobody would ever buy cover early. Consequently, nobody would insure anything until they were actually sued.

The strict exclusion also reaches slightly wider than the case itself. It includes legal appeals and connected civil action on the exact same facts. Furthermore, it covers other related claims from the same episode of treatment. It includes anything you already had clear reason to expect on the application date. You can review standard insurance guidelines on the Insurance Regulatory and Development Authority of India (IRDAI) website for further clarity.

Why You Must Declare The Lawsuit Anyway

This is the critical part that decides everything. It determines whether the rest of the policy actually holds up. Specifically, it takes exactly one paragraph on a standard form.

Some doctors reason differently. They wrongly think that since the case is excluded regardless, mentioning it changes absolutely nothing. However, that dangerous reasoning ends very badly.

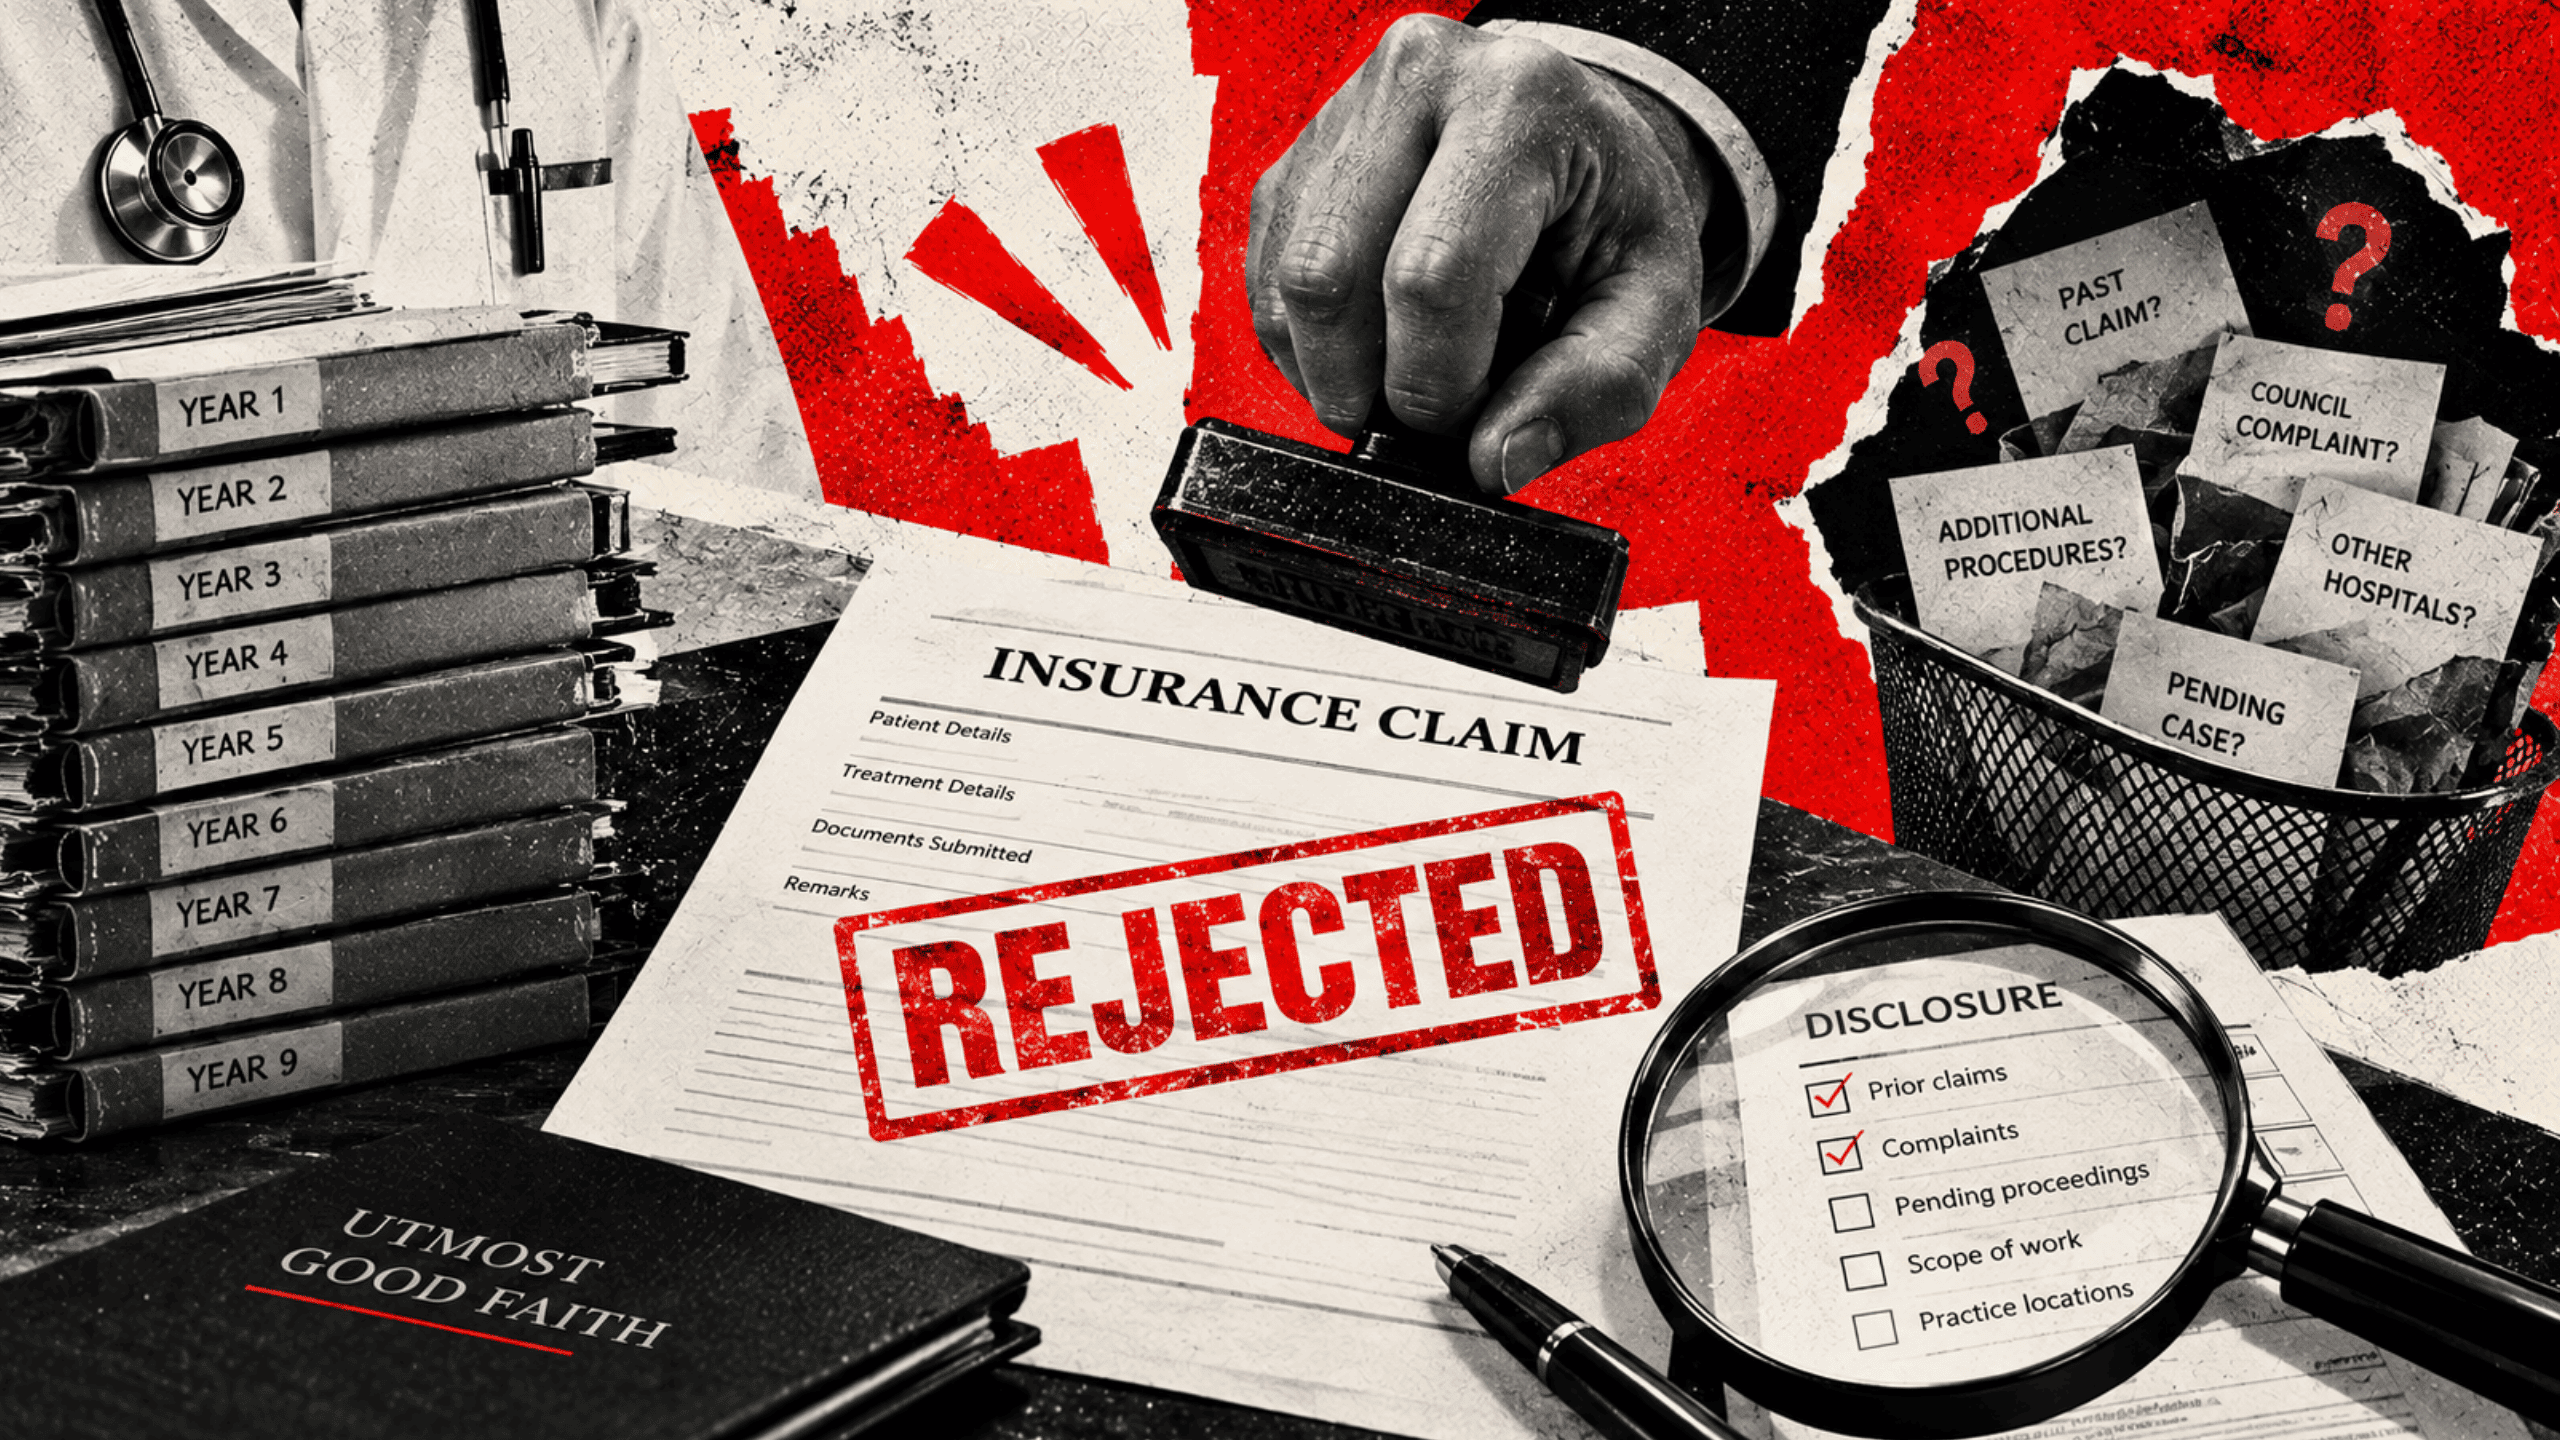
Every proposal form explicitly asks about pending litigation. Furthermore, you are under a strict legal duty of utmost good faith. Concealing an active forum matter is material non disclosure. Therefore, it puts the entire policy at severe risk. It risks much more than just the excluded case.

Let us spell the trade out plainly. Declare it honestly, and you get a valid policy with one named exclusion. Hide it, and you may easily find the policy fails later. Consequently, it could fail on a completely unrelated claim three years later. This devastatingly happens because the legal contract was induced by deliberate concealment.

What The Underwriting Team Will Ask You

Have all the specific answers ready before you actually start. Guessing at any of them creates a serious factual discrepancy. That discrepancy will inevitably surface later.

Expect significantly more questions than a routine application. Expect a day or two of processing rather than minutes. Specifically, a declared matter instantly moves the file into careful manual review.

  • Case details: Provide the specific forum, case number, exact filing date, and current legal stage.
  • The clinical facts: Write a very brief factual account of the medical treatment complained of.
  • Amount claimed: State the exact financial compensation actively sought by the patient.
  • Your defence position: State whether you have officially replied, and outline the broad legal line.
  • Wider history: List any other official notices, complaints, or state medical council matters.

One pending matter rarely results in an outright refusal. Doctors in active litigation are insured every single day of the week. Underwriters actively look for a pattern. They look for several claims in a short period. Alternatively, they look for a recurring clinical issue in one specific procedure. Check the National Consumer Disputes Redressal Commission (NCDRC) to deeply understand how these cases typically proceed.

What An Indemnity Policy For Doctor With Pending Consumer Case Actually Buys

An indemnity policy for doctor with pending consumer case circumstances is entirely legitimate. Furthermore, it is readily available and highly worth buying. However, this is provided you know exactly what you are buying. Set the pending case aside completely. Look carefully at what remains financially exposed. Specifically, the remaining professional exposure is considerably larger.

  • Every future consultation: Protected safely from the exact policy inception date onwards.
  • Defence costs going forward: Fully funded by the insurer rather than self financed.
  • A retroactive date that starts running: Renew without a break. Therefore, it becomes real protected history.
  • Empanelment compliance: Many top hospitals strictly require active cover regardless of pending legal matters.

Consumer matters commonly take three to seven long years. Practising completely uninsured for that entire stretch is incredibly dangerous. Furthermore, doing so while already fighting one active dispute is terrible risk management. It is a risk very few doctors would willingly accept. Therefore, securing an indemnity policy for doctor with pending consumer case is absolutely vital for your peace of mind.

The Essential Lesson Worth Carrying Away

A new insurance policy will not magically rescue the current case you are in. That requires a highly skilled legal advocate. It requires complete clinical records and immense personal patience. Always maintain your professional standards per the National Medical Commission (NMC) guidelines.

What it actually does is stop the next four years from being entirely uninsured. It protects you completely while you vigorously fight the current case. Therefore, declare everything completely. Accept the specific exclusion gracefully. Consequently, get the rest of your medical career safely covered starting today. Finding an indemnity policy for doctor with pending consumer case issues is undeniably the smartest move you can make right now.

5 FAQ SECTION

Can I get indemnity insurance while a consumer case is pending against me?

Yes. Insurers issue policies to doctors in active litigation regularly. The pending matter will definitely carry a specific exclusion. However, cover for all your future practice begins normally.

Will the new insurer pay legal fees for my pending case?

No. Defence costs for a matter that existed before the policy started fall outside the contract. They are treated strictly as a known circumstance. Therefore, they remain your own responsibility.

What if I do not declare the pending case on the proposal form?

You risk far more than the specifically excluded case. Non disclosure can void the entire policy immediately. Consequently, even unrelated future claims could be firmly refused years later.

Does a pending case increase my premium?

It can certainly happen, though often only modestly. Underwriters deeply look at frequency and severity across your history. Conversely, they avoid aggressively reacting to one single matter in isolation.

Can I buy cover after a legal notice but before a case is filed?

Yes, and you absolutely should. The notice itself will be firmly excluded as a known circumstance. Furthermore, everything else you legally do from that date onwards can still be protected.
Tags: active lawsuit insuranceconsumer court medical negligenceconsumer forum doctor casedoctor lawsuit coverdoctor legal defensedoctor liability protectiondoctor risk managementhealthcare insurance Indiaindemnity policy for doctor with pending consumer caseIRDAI insurance guidelinesknown circumstance exclusionmedical defense fundmedical legal riskmedical malpractice Indiaprofessional indemnity coverage
Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote
Previous Post

Eleven Days Uncovered: An Indemnity Policy Lapse

Next Post

Covered By Tonight? Policy Activation Timelines Explained

coveryouadmin

coveryouadmin

Professional Indemnity- Our expertise lies in safeguarding the interest & reputation of our esteemed Medical Fraternity with our revolutionary product- Doctors Professional Indemnity Insurance. Given the complex & high-stakes nature of healthcare operations, doctors are certainly exposed to medical negligence risks at all times. It is very important to protect your high-responsibility profession with a Professional Indemnity Cover that will act as a safety net against any malpractice claim. Our Professional Indemnity is best suited for all your medical practice requirements. CoverYou’s Customised Professional Indemnity Insurance will not only safeguard your finances but also your hard earned reputation. We provide customised benefits exclusively tailored to meet the needs of Doctors & Hospitals. Our Professional Indemnity is guaranteed to provide comprehensive medical negligence coverage with an expert lawyer panel & renowned senior doctors present all across India. We are known to offer handheld support to our customers throughout their journey with us especially during claims!

Related Posts

Protection Beyond the Age Barrier
Blog

Still Practising At 68? The Age Limit Myth

September 16, 2026
Racing the Clock to Get Covered
Blog

Covered By Tonight? Policy Activation Timelines Explained

September 16, 2026
The Gap That Breaks Your Protection
Blog

Eleven Days Uncovered: An Indemnity Policy Lapse

September 16, 2026
Switching Insurers? Read This First
Blog

Switching Insurers? Read This First

September 16, 2026
The Complaint That Comes Back
Blog

One Old Complaint. Declare It Or Not?

September 16, 2026
The Claim That Never Gets Through
Blog

Paid Every Premium, Still Rejected

September 16, 2026
Next Post
Racing the Clock to Get Covered

Covered By Tonight? Policy Activation Timelines Explained

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

Professional Indemnity Notice

Protect Your Medical Practice

Comprehensive Professional Indemnity Insurance tailored for doctors. Safeguard your career, practice, and reputation against unforeseen liabilities.

Get a Free Quote

Categories

  • Abroad
  • AI & Digital Health
  • Alternative Careers
  • Blog
  • casestudy
  • Clinic & Practice
  • Doctor Finance
  • Doctor Psychology
  • Early Career
  • Finance & Insurance
  • Healthcare Business
  • Leadership & Management
  • Legal & Risk
  • Lifestyle & Mindset
  • Medical Lega
  • Medical Legal
  • Medical Registration
  • Medical Student
  • Patient Acquisition
  • Personal Branding
  • Personal Life
  • Specialization
  • Specialization Growth
  • Technology & Future

Recent Posts

  • Still Practising At 68? The Age Limit Myth
  • Covered By Tonight? Policy Activation Timelines Explained
  • A Pending Case And A New Insurance Policy
  • Eleven Days Uncovered: An Indemnity Policy Lapse
  • Switching Insurers? Read This First

© Alexa Insurance Broker Pvt. Ltd. All Rights Reserved

Insurance

  • Doctor's Insurance
  • Hospital Insurance
  • Health Insurance

Resources

  • Press Release
  • Customer Reviews
  • Blogs

Company

  • About Us
  • Contact
  • Career
Alexa Insurance Broker Private Limited
IRDAI License Number: 825
CIN: U66010DL2020PTC371173
Direct Broker (Life and General)
Valid Till: 08/06/2025
Principal Officer- Mr. Deepanker Mahajan

Payment Methods

Secured With

DMCA.com Protection Status

Follow us on

*Standard T&C Apply. All products information and offerings are authentic and solely based on the information received from the insurers. For more information on the risks associated with purchasing insurance, please read the sales brochure of the insurer carefully. Tax benefits are subject to changes in the applicable tax laws. Visitors are hereby informed that their information submitted on the website may be shared with Insurers. You authorise Alexa Insurance Broker Pvt. Ltd. (CoverYou) to contact you through Call, SMS, Email, WhatsApp or any other mode in the future. You hereby override your NDNC registration.
Alexa Insurance Broker Private Limited, CIN: U66010DL2020PTC371173, Regd. Off: RZ 129/A, Shiv Mandir Marg, Raj Nagar 1, Palam Colony, New Delhi - 110077; Corp. Off: Plot No. 15 & 16 - C, Udyog Vihar, Phase 5, Gurgaon, Haryana – 122022.
IRDAI License no. 825; Direct Broker (Life & General) valid till 08th, June, 2025. Email - help@coveryou.in; Helpline number: 1800-202-6900.

Copyright © CoverYou All Rights Reserved

  • Refund & Cancellation
  • Policy Statements
  • Terms & Conditions
No Result
View All Result
  • Doctors
    • Professional Indemnity
    • Health Insurance
    • Motor Insurance
    • Terms Insurance
    • Life Insurance
    • Home Insurance
  • Hospitals
    • Professional Indemnity
    • Property Insurance
    • Public Liability Insurance
    • Money Insurance
    • Comprehensive Package Insurance
  • Knowledges
    • Doctors
      • Do’s
      • Don’t
      • Bail & Anticipatory Bail
      • How to Prevent Mishap
      • Supreme Court
      • Criminal Liability
      • Indemnity
    • Hospitals
      • Requirements for Hospital
      • Regulatory Requirements of Blood
      • Bio Medical Waste Management
      • Death in OT
      • Vicarious Liability
      • Risk Management
    • Acts
      • Sections of India
      • CPA
    • Case And Judgment Summaries
    • Press Release
    • Recent Medico-Legal Cases

Copyright © 2022 CoverYou All Rights Reserved

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In