Your medical registration finally came through in March.
You have just started working as a junior consultant.
Specifically, you are seeing patients on your own for the very first time.
Suddenly, a senior colleague tells you something concerning over lunch.
They advise you not to bother with insurance yet.
Consequently, they claim insurers will ignore you completely.
They say you need three or four years behind you.
It sounds highly plausible.
However, is there an actual minimum experience required to buy indemnity insurance in India?
What The Rules Actually Say About Doctor Insurance
No Indian regulation sets a strict experience threshold. Specifically, nothing in the official framework requires it. You can verify this directly through the Insurance Regulatory and Development Authority of India (IRDAI). Furthermore, nothing in the medical council conduct regulations makes practice years a strict condition.
Therefore, you must clear up a related myth immediately. Professional indemnity insurance is not legally mandatory for doctors under Indian law. Conversely, hospitals and employers frequently require it. Consequently, this is a commercial requirement rather than a legal one.
The Gate That Does Exist For Medical Indemnity
So, if not experience, what is the insurer actually testing? What insurers consistently ask for is valid registration. They absolutely do not demand seniority. Proposal forms ask for your medical registration number. Furthermore, they ask for your exact year of registration.
Read those two specific questions very carefully. They firmly establish that you are legally entitled to practise. Additionally, they formally date the start of your professional life. Neither question is phrased as a minimum threshold. You can easily check your registration status via the National Medical Commission (NMC).
- Qualification: Your MBBS, BDS, or any equivalent postgraduate degree.
- Registration: A completely valid registration with the relevant state medical council.
- Scope of practice: The actual clinical procedures you physically perform.
- Practice setting: A private clinic, hospital, or visiting attachment.
Consequently, securing cover simply requires the right paperwork. The actual minimum experience required to buy indemnity insurance is practically zero days.
Where Clinical Experience Genuinely Comes In
Proposal forms definitely ask how long you have been practising. However, this specifically affects your file as a pricing input. It is an underwriting judgement tool. Conversely, it is absolutely not a strict pass mark.
A doctor two years into practice is assessed carefully. A doctor twenty years in is assessed on the exact same factors. These include specialty, procedure mix, patient volume, and past claims. Experience is just one single line in that complex assessment. Furthermore, for most specialties, it is not the decisive one.
A junior surgeon performing high risk procedures carries massive exposure. A senior physician simply consulting carries significantly less. Therefore, fixating on the minimum experience required to buy indemnity insurance is highly misguided. The question that truly changes your position is what you do clinically. It is absolutely not how long you have been doing it.
Cases Worth Asking About Directly
Two specific situations are genuinely worth a direct phone call. Never rely on a blind assumption.
- Still in training: An intern or a resident might hold individual cover. However, this varies heavily between different insurers. Some training posts are safely covered under the institution directly. Therefore, ask clearly rather than assuming either way.
- Newly registered and about to start: Eligibility terms can differ for a doctor with absolutely no practice history. Consequently, thoroughly confirm the legal position before your first independent consultation. Always review your contractual rights under the Indian Contract Act.
In both specific cases, the most useful step is identical. Ask the insurer or broker what their exact eligibility position is. Furthermore, get this securely in writing before you actively rely on it.
Why Delaying Insurance Costs More Than The Premium
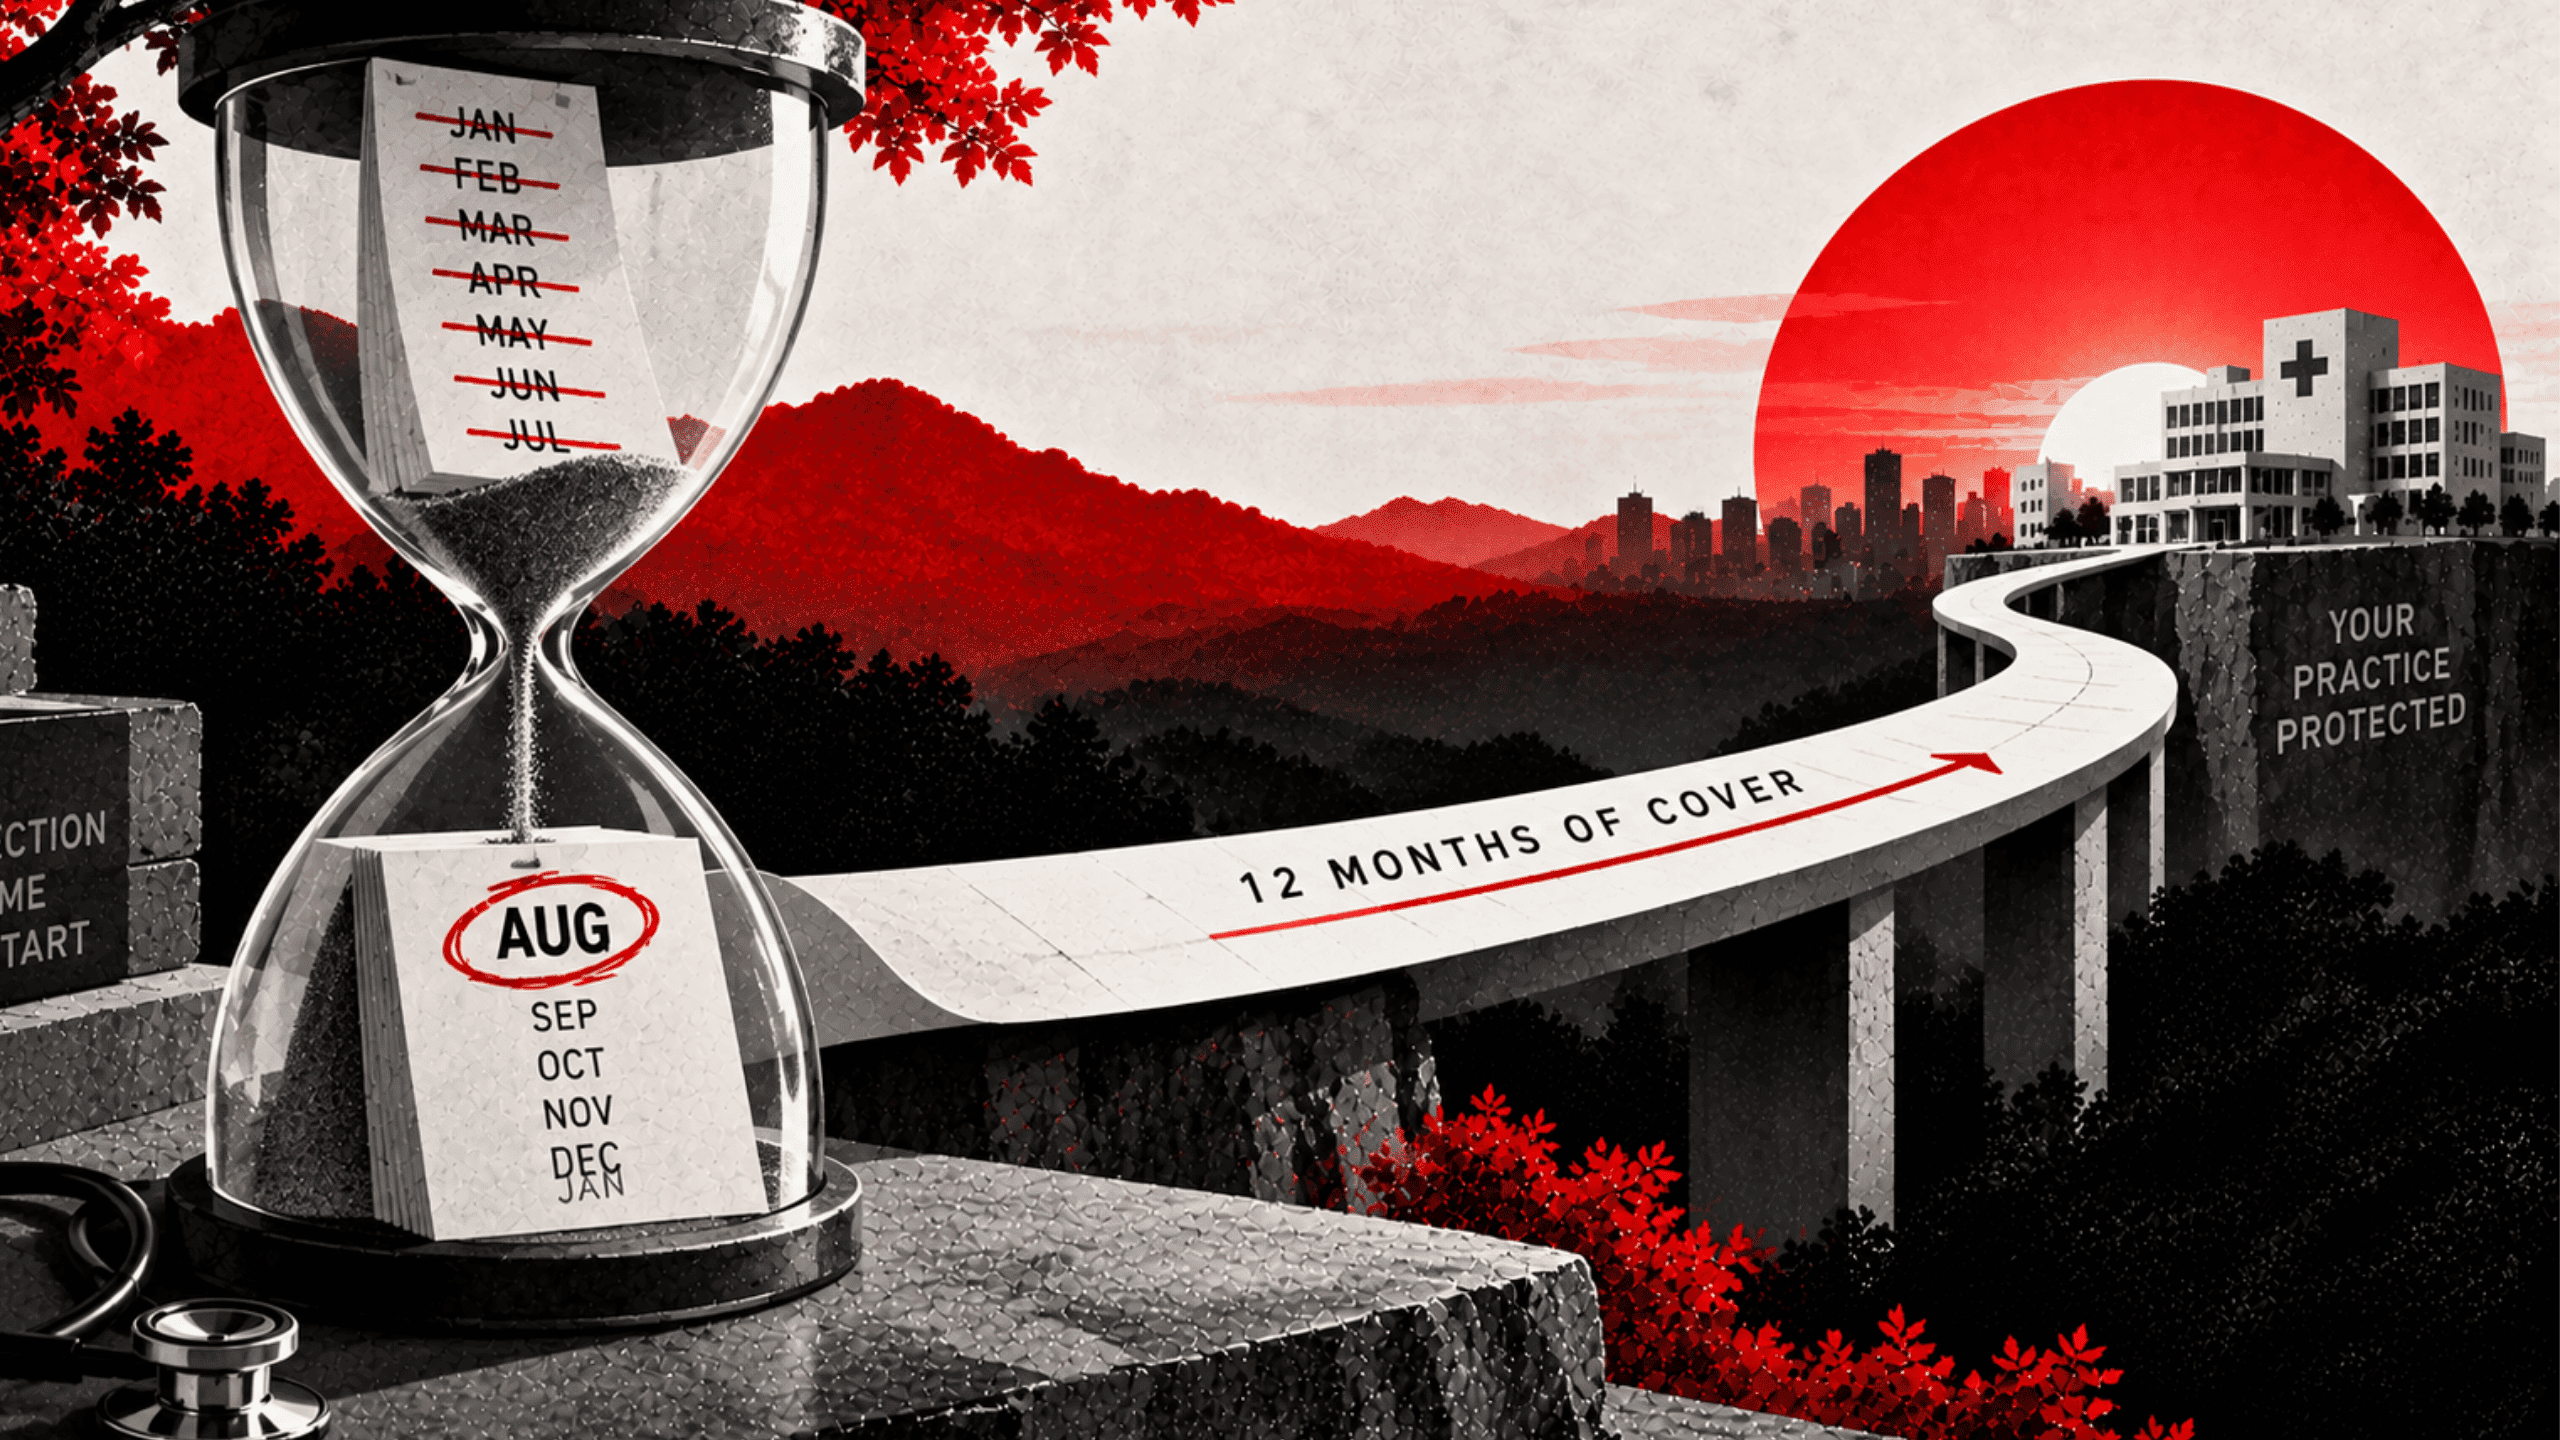
Here is the critical part your senior colleague completely left out. Professional indemnity in India is strictly written on a claims made basis. Every single policy carries a vital retroactive date. Specifically, this is the exact point from which your medical work becomes insurable.
Wait three full years to buy a policy. Consequently, your retroactive date will be set exactly three years from now. Those first three years of consultations stay completely outside any policy you buy afterwards. They remain excluded permanently.
Waiting does not magically delay the cost of cover. Conversely, it permanently removes cover from the entire period you waited.
The Final Takeaway For Junior Doctors
Registration is the actual gateway. Experience is merely a premium rating factor. It is absolutely not a qualifying one.
Buy the protective policy the exact moment you start practising. Do not wait until you feel senior enough to need one. Consequently, your third year self will be incredibly grateful to your first year self. The true minimum experience required to buy indemnity insurance is absolutely nothing. Protect your hard earned medical practice immediately.
5 FAQ SECTION
Is professional indemnity insurance mandatory for doctors in India?
Not under Indian law. The medical council regulations currently in force do not explicitly require it. However, hospitals, employers, and empanelment contracts frequently do. Consequently, it is a contractual requirement rather than a legal one.
Do insurers in India set a minimum number of years of practice?
No published eligibility rule of that kind actually exists. Proposal forms strictly ask how long you have practised as an underwriting input. Confirm the exact position with the insurer you approach.
Can a doctor buy cover in their first year of independent practice?
Yes. Eligibility turns entirely on valid registration and an accurate description of your practice. Terms for a doctor with zero practice history can differ. Therefore, ask before you assume.
Can interns or residents hold their own indemnity policy?
This varies significantly by insurer and by exact wording. Training posts are sometimes actively covered under the institution arrangement. Ask the insurer directly rather than simply relying on general guidance.
Does buying early make the policy more expensive?
Premium follows your specialty, procedure mix, and practice volume rather than your start date. Buying early is exactly what fixes an earlier retroactive date. Consequently, this is where the real value sits.